Q2/Q3 2024 Earnings Review - 2
Read part 1 here
In this post we will focus on
-
Laurus Labs
-
Ami Organics
-
Piramal Pharma
Laurus Labs
Laurus Labs had another soft quarter both from top line and bottom line perspective.
Some background for some folks who are wondering why price is not dropping even though results on face value look bad
In FY23, Laurus received a one-time order from a Pharma giant. In the absence of such an order in FY24, the company’s overall revenue declined significantly. The company nevertheless anticipated significant revenue from the CDMO segment for FY24 based on the agreement signed with innovator companies for product development and commercialisation, however, in FY24, the innovator companies have gone slow in terms of validation and filing of approval for the product, which in turn, impacted the revenue for Laurus. This revenue is expected to flow in FY25 along with hopefully repeat of FY23 repeat order from Pharma giant.
So the company is going to test patience and CDMO business are lumpy in nature so you expect few bad quarters followed by exceptional quarters
Some notes their business division
-
CDMO
-
90 active projects in total now up from a 70 last year
-
Early traction visible driven by advancing clinical projects, Laurus is banking on this drive future growth
-
-
API & FDF
-
API revenues were flat and are expected to remain like that for this year
-
FDF business which is also dependent on ARV remained flat
-
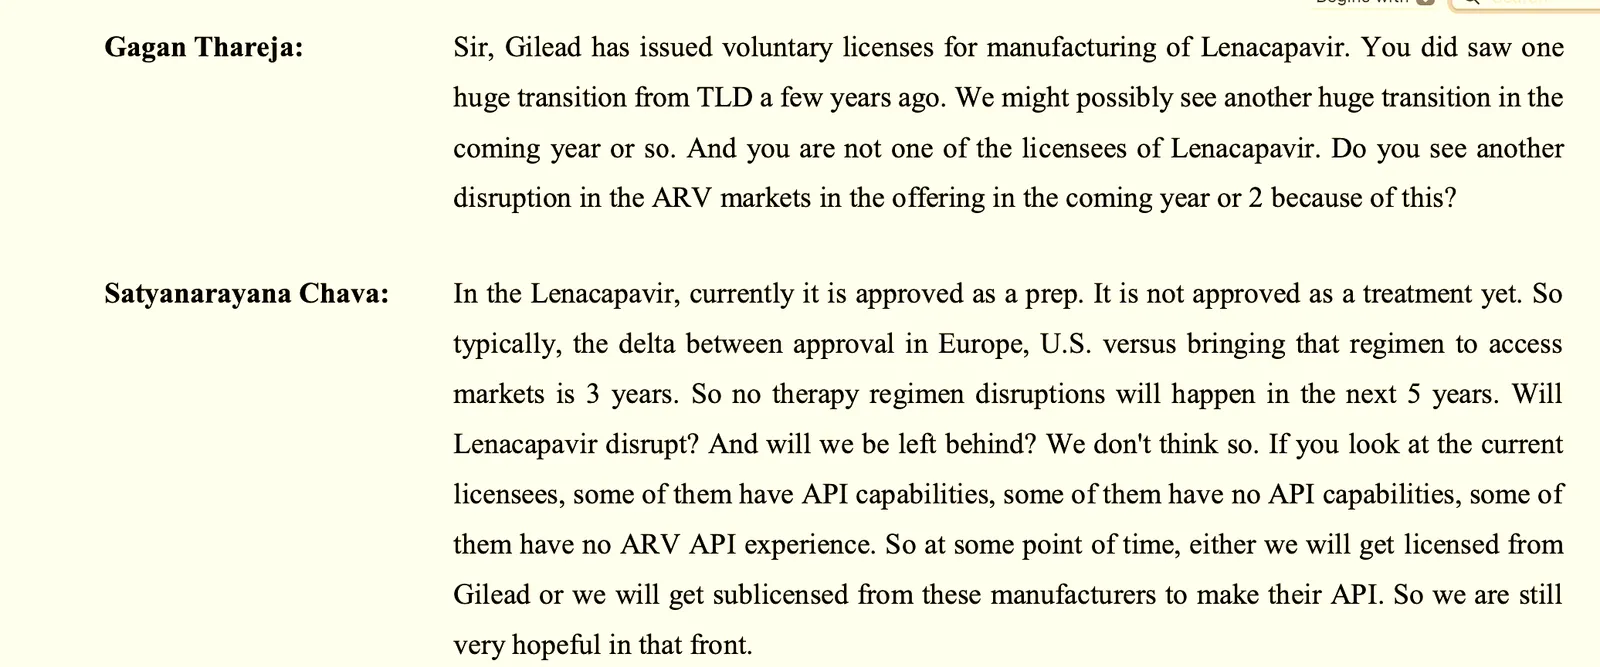
On Concall management indicated that they have time to plan if there ARV business in impacted and they can possible mitigate this by putting a sterile manufacturing facility
-
-
Bio
- Bio business is scaling up, but not to my expectations. The company has built capacity and now are waiting market traction
We will next revisit Laurus next year at conclusion of Q4 (Mar’25), full press release can be read here
Ami Organics
Watch this YouTube video to understand business of Ami Organics. They reported excellent numbers
-
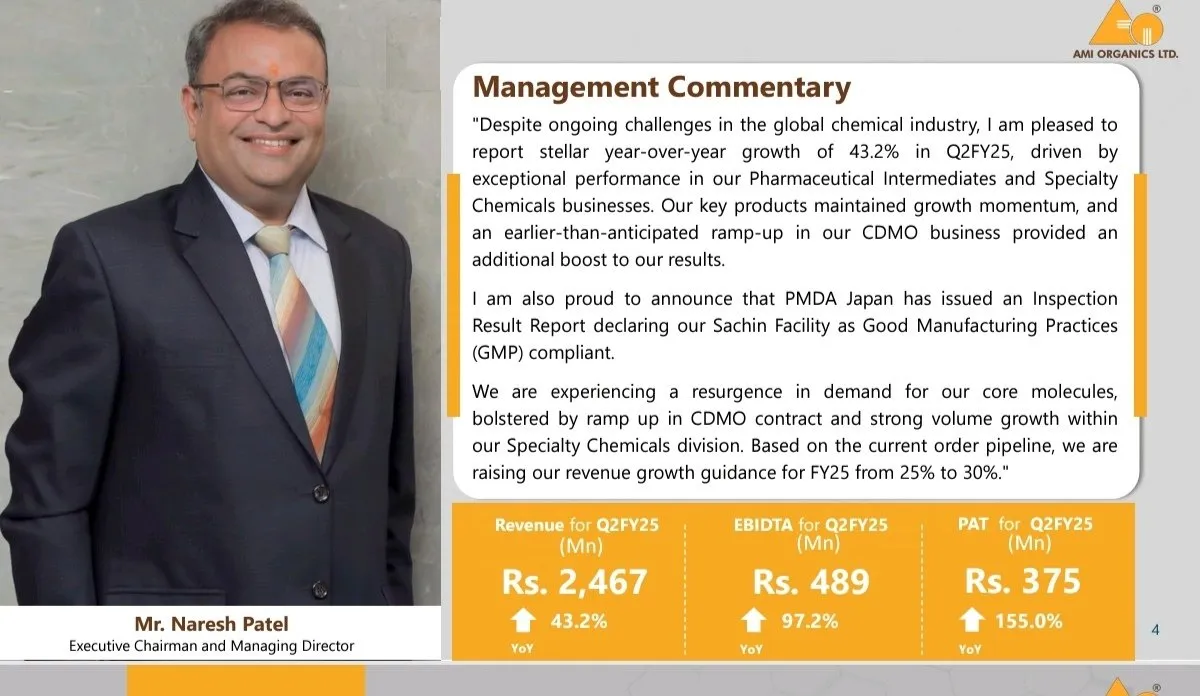
Revenue grew by 43.2% YoY in Q2 FY25, reaching INR 247 CR
-
Gross Margin improved to 43.4%, up from 41.0% YoY.
-
EBITDA increased by 97.2% YoY to INR 49 CR, with an EBITDA margin of 19.8%. PAT rose by 155% YoY to INR 38 CR , achieving a PAT margin of 15.2%.
-
Export Revenue contributed 76%, with the domestic business at 24%.
However what excited markets is that revenue growth guidance for FY25 raised to 30% due to high demand in core products.
This is Niche high margin business with long runway but now is getting priced for that as well.
Piramal Pharma
I have written extensively on Piramal group you can find it here
Piramal Pharma Limited (PPL) is a prominent player in the pharmaceutical industry. It offers a comprehensive range of products and services across the drug development lifecycle. PPL operates under three business verticals -
(i) Piramal Pharma Solutions (“PPS”), an integrated contract development and manufacturing organisation (“CDMO”);
(ii) Piramal Critical Care (“PCC”), a complex hospital generic (“CHG”) business; and
(iii) India consumer healthcare (“ICH”) business, selling over-the-counter (“OTC”) products. Alongside established brands, PPL is among the leading players in the self-care domain in India
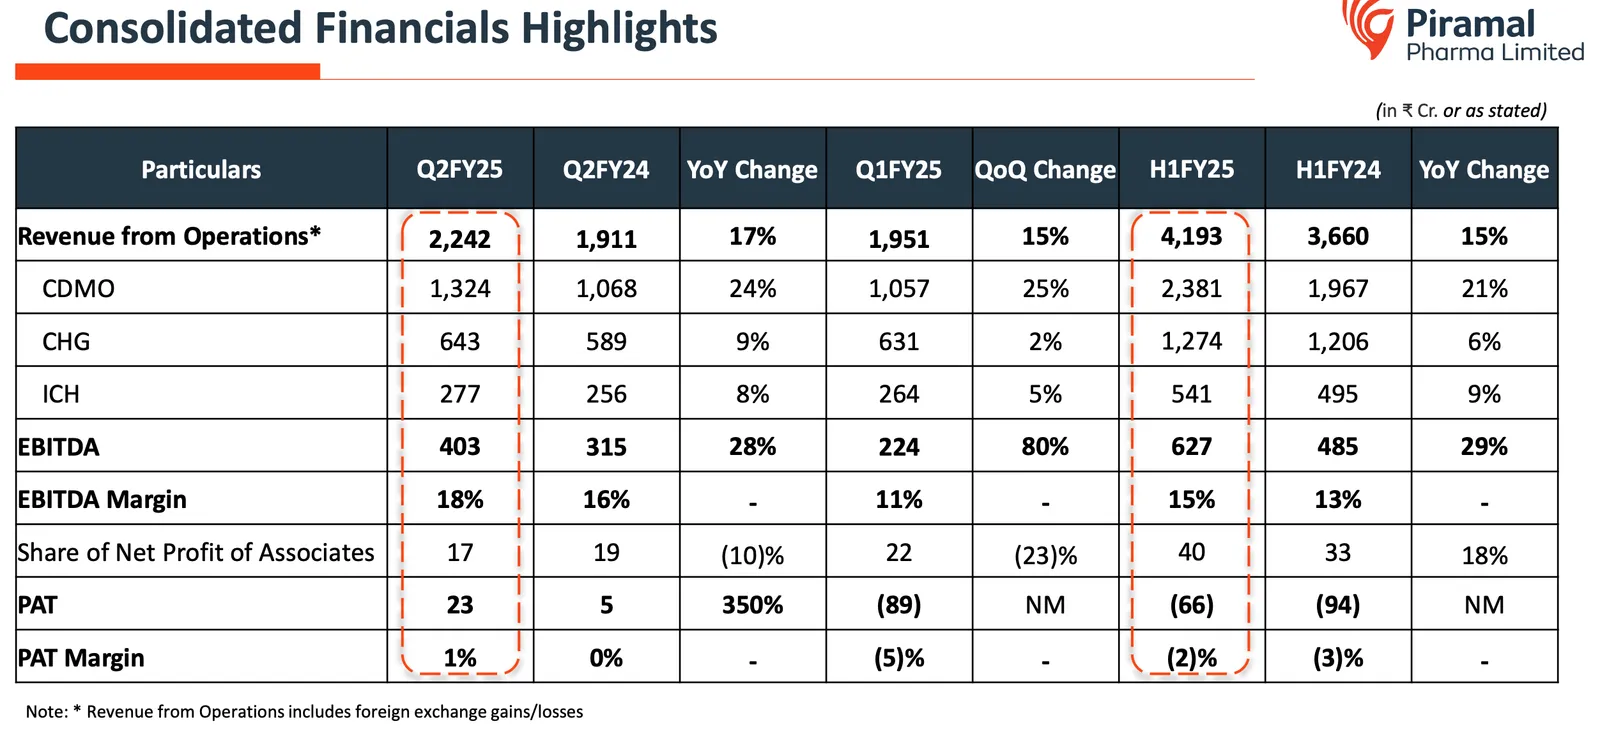
The company reported a very good quarter, increasing overall revenue by 17% and reducing losses and similar to other companies their CDMO division was key performer
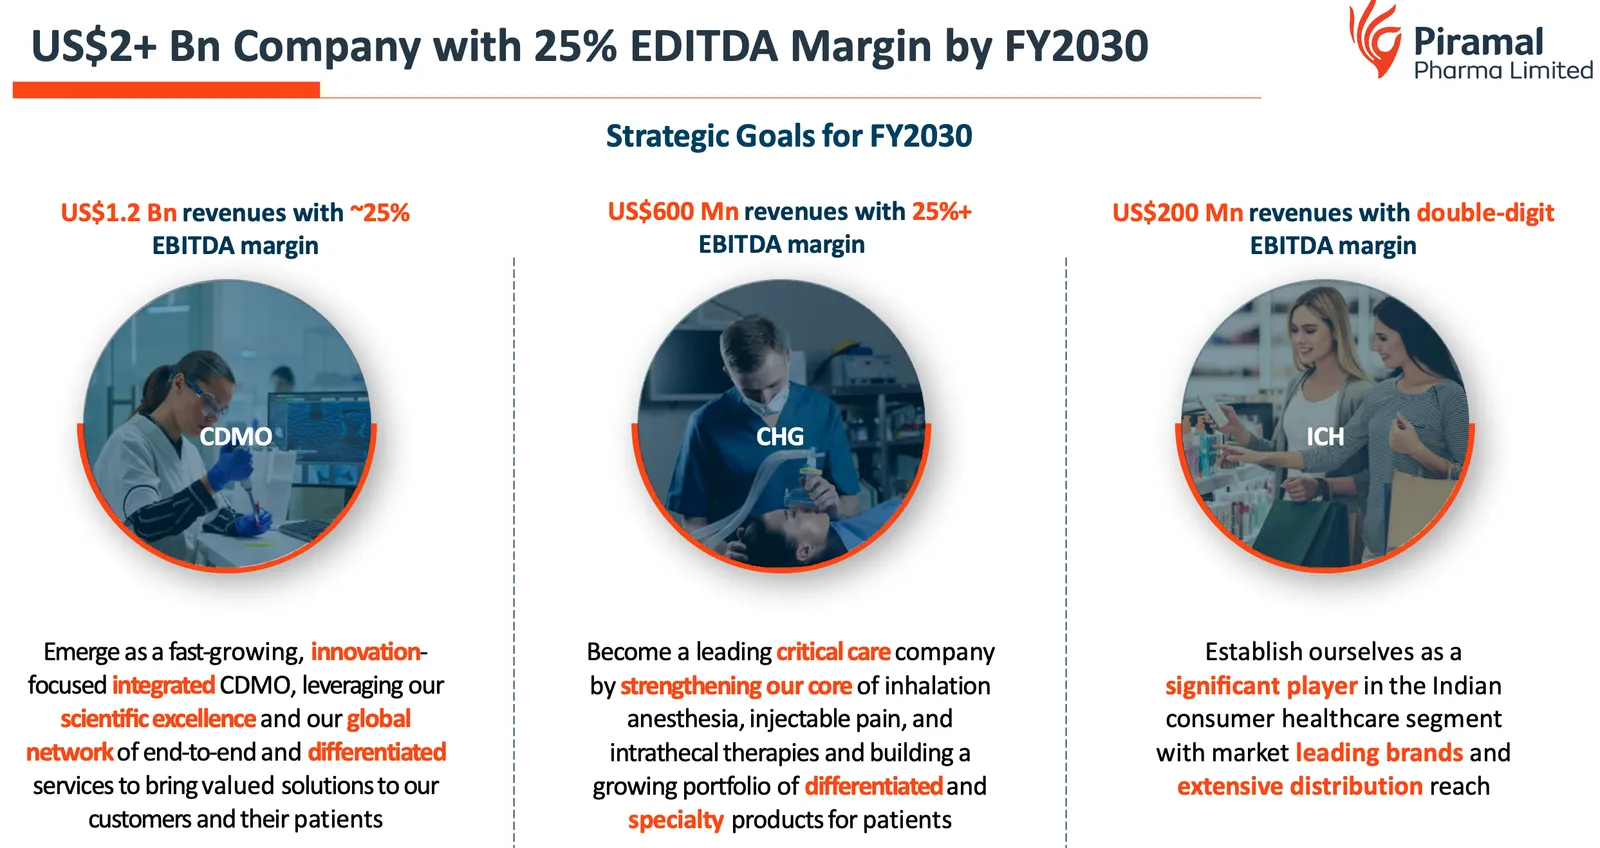
What was interesting that company shared some lofty financial aspiration for 2030 in their earnings presentation (link now broken)
we need monitor their execution debt reduction as most capex has been done and borrowing should start reducing from next year
I try and end every post something with gallery
This is a record of the author's thinking in November 2024, kept as written. It is not a recommendation to buy or sell, and the author may hold the securities discussed. See the disclosures.