India : State of Banking
Best viewed on Desktop
Source of all data is RBI
1 Credit growth bottomed at 9.0% in May 2025 and has almost doubled to 17.7% in the twelve months since.Deposit growth moved too, but far less — from 9.9% to 12.2%. The result is a 5.4 percentage point wedge that banks have to fund from somewhere other than retail deposits:
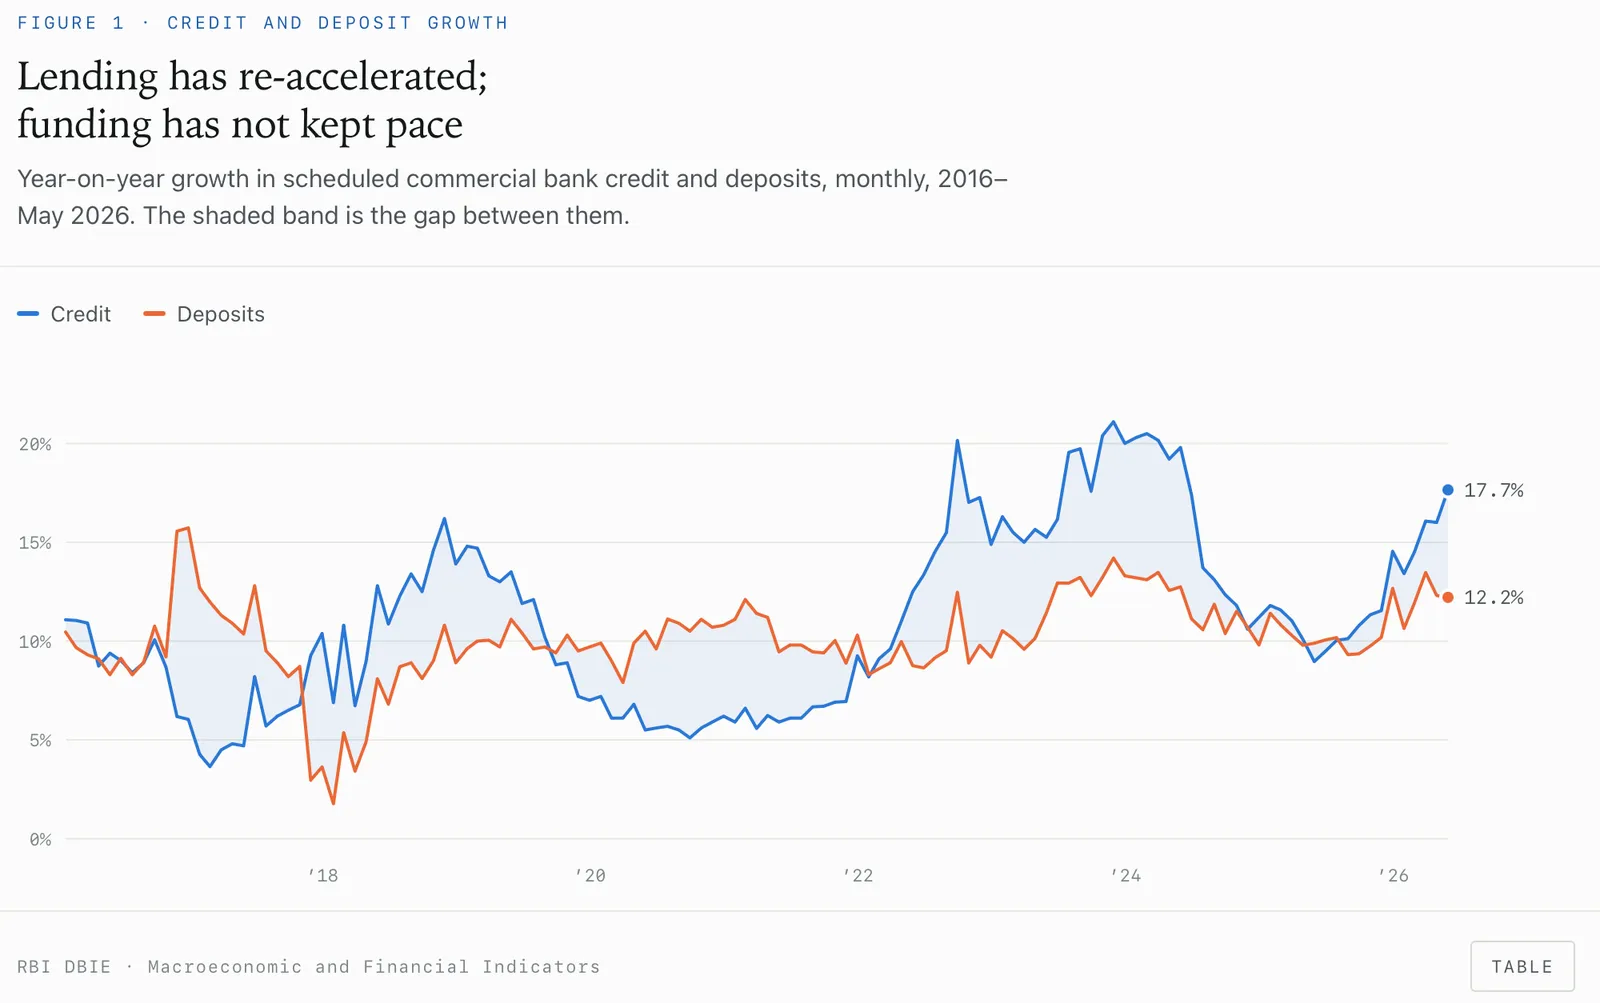
The banks least hurt are those with the highest CASA ratio (current and savings balances as a share of deposits), because their funding cost barely moves. Banks plugging the gap with bulk money see margins compress first.
2
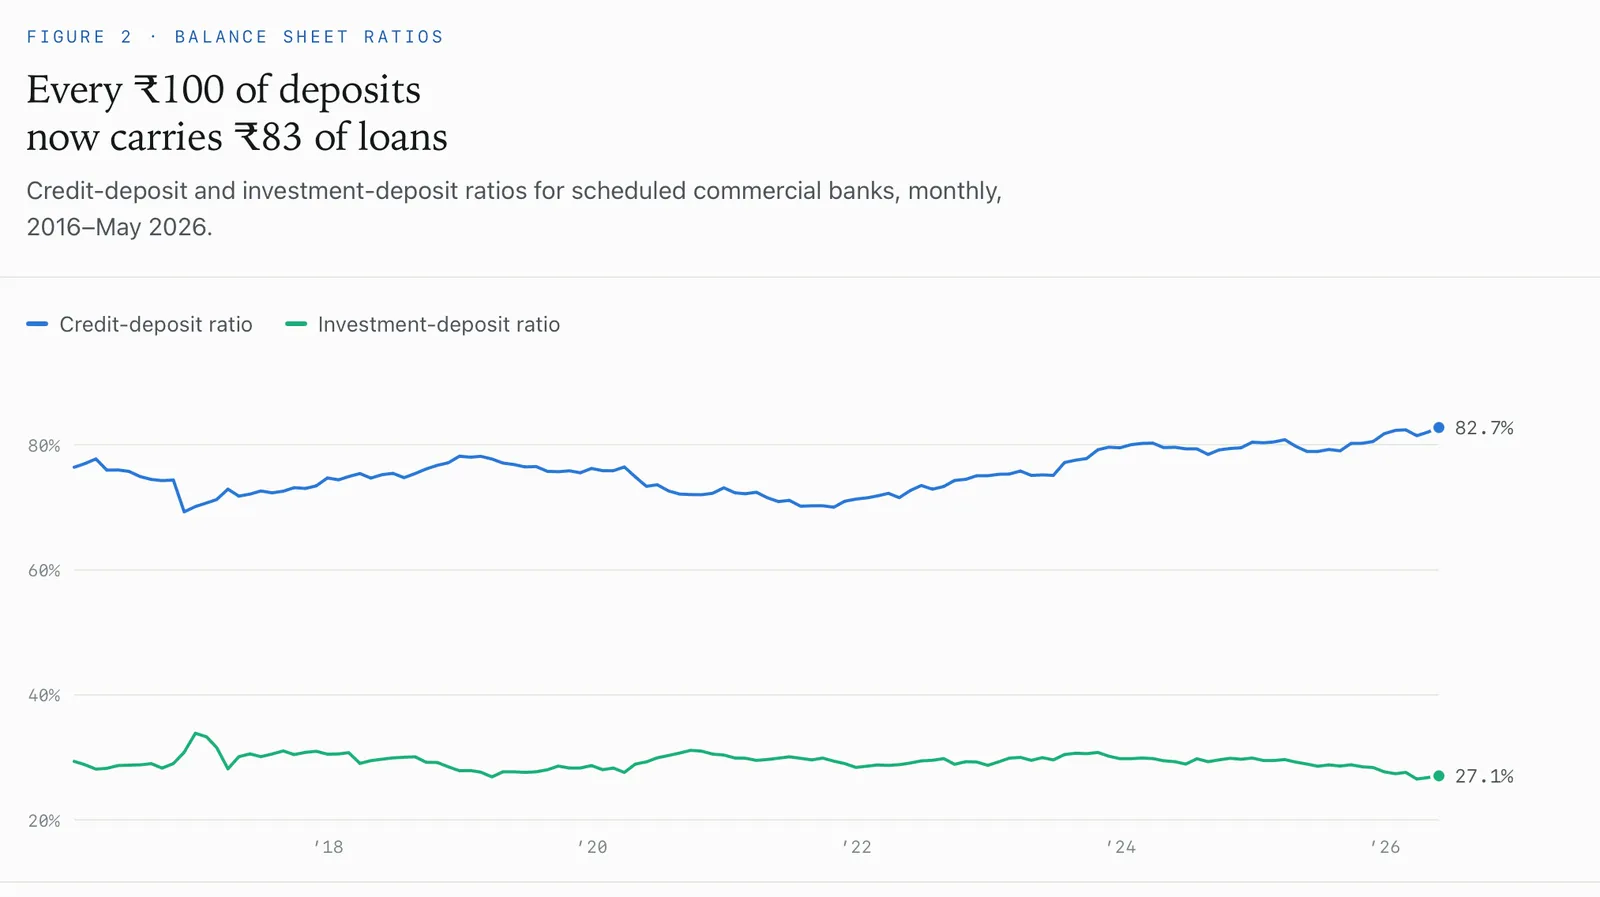
At 82.7% the system has limited room to keep growing loans faster than deposits without paying up for funding. Historically, a high CD ratio resolves one of two ways: banks compete harder for deposits which raises funding costs and squeezes net interest margins or credit growth slows to meet deposits. Both are margin events; only one is also a growth event.
3 The pools that grew fastest, personal loans and lending to non-bank finance companies, are the least seasoned.
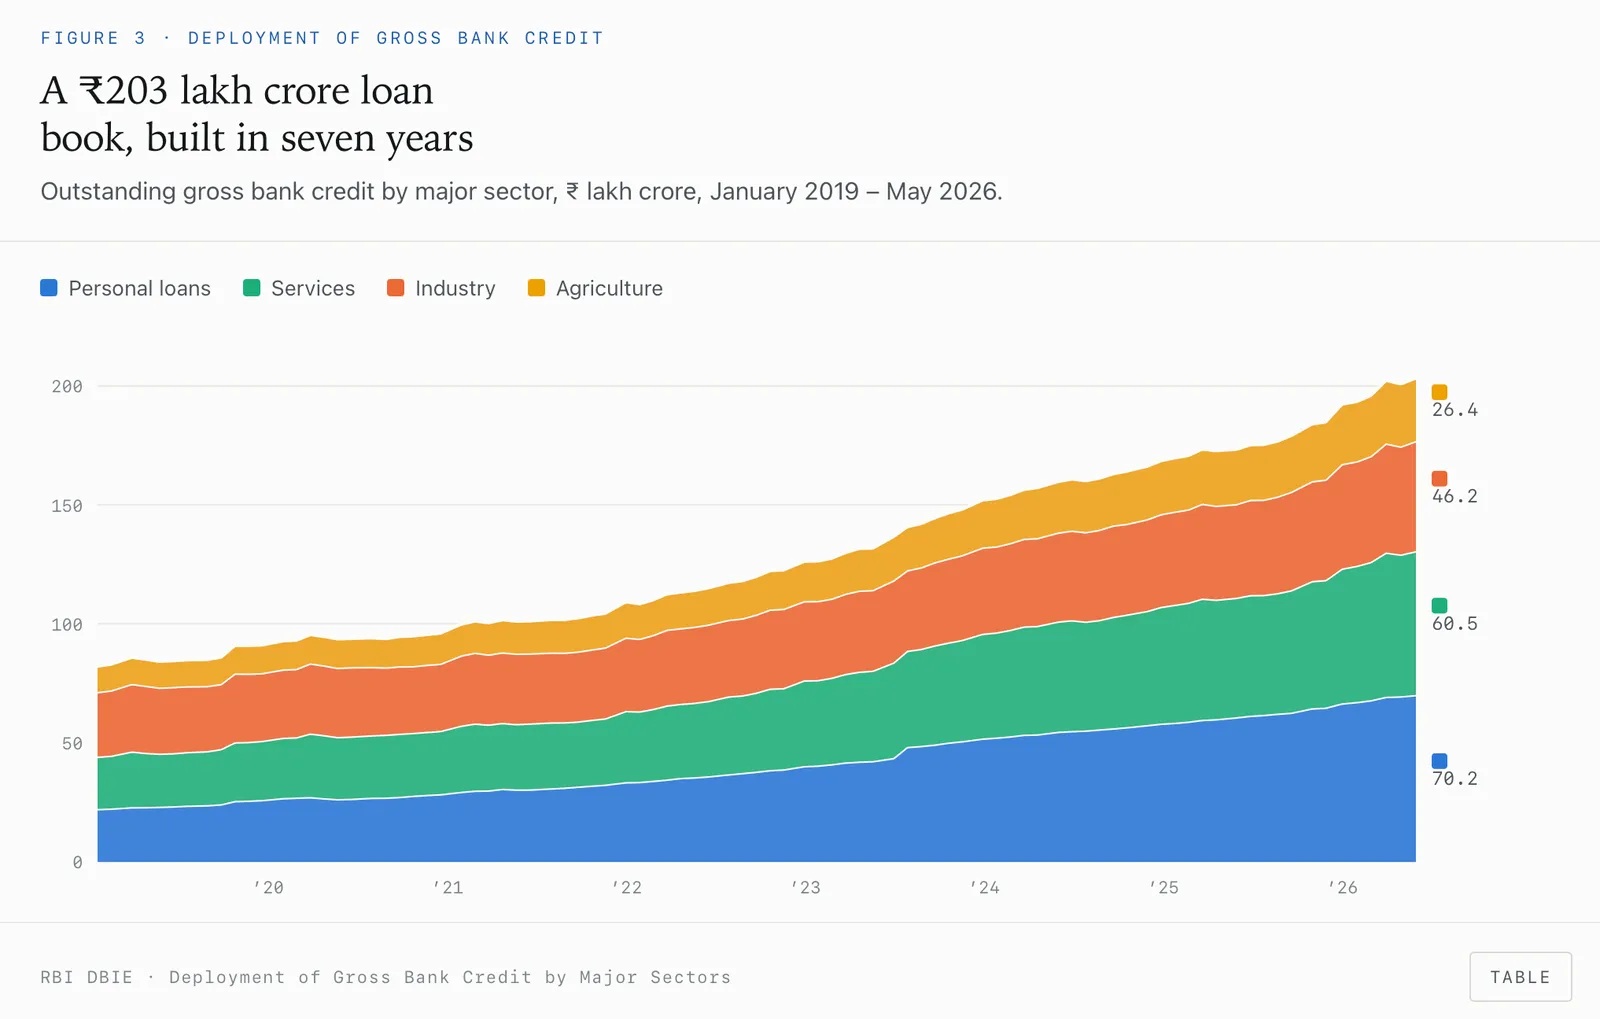
Expect continued growth in personal loans
4
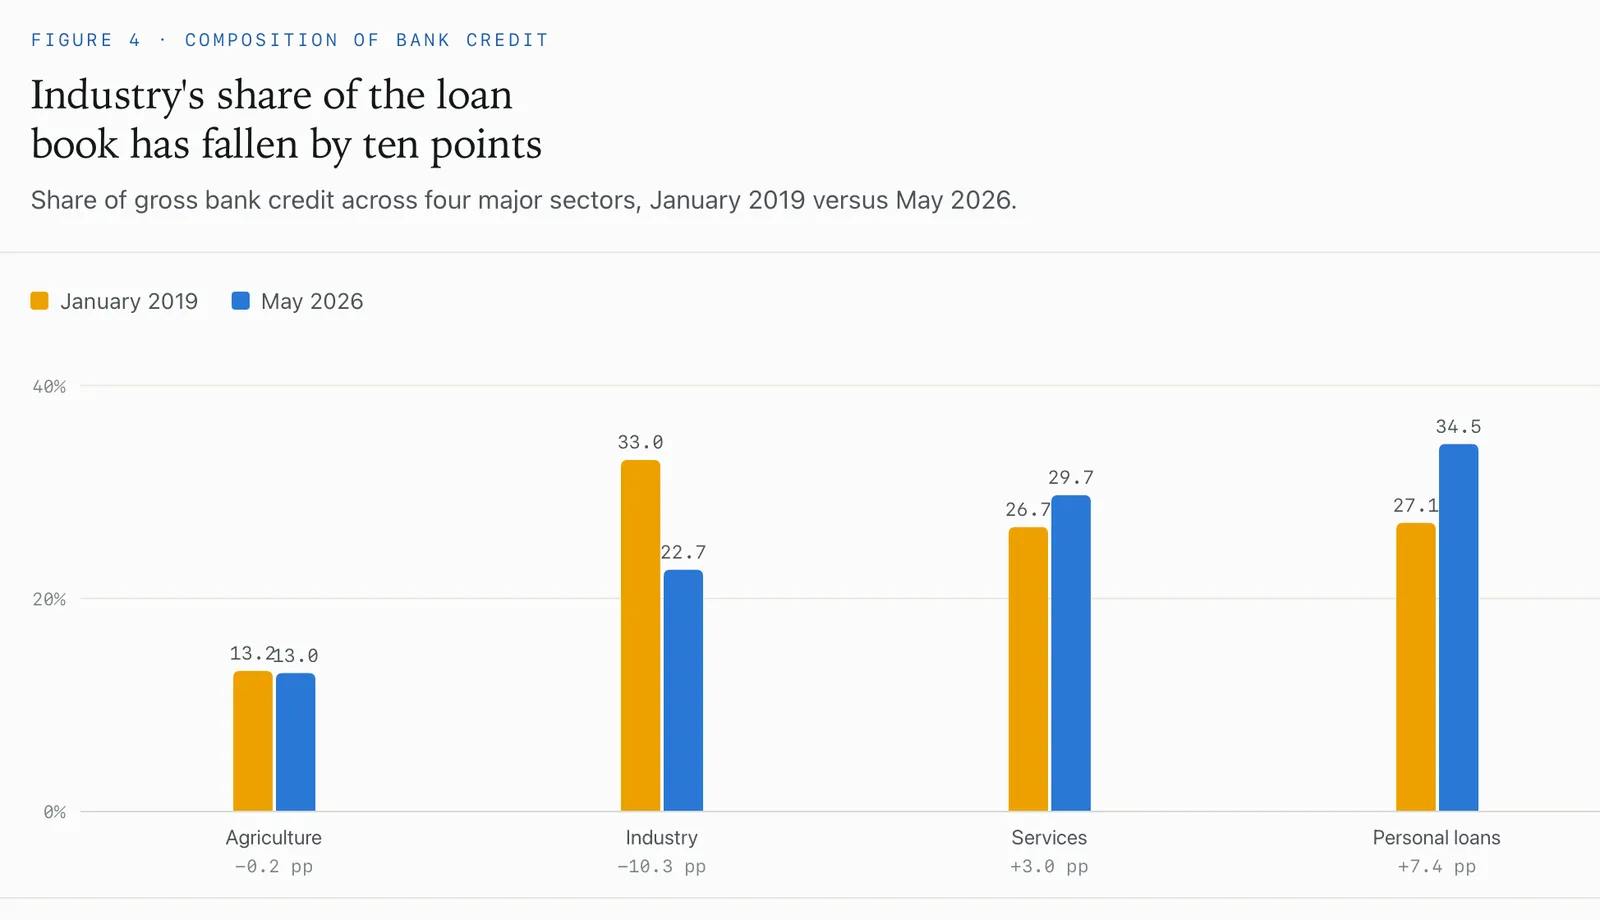
unsecured retail is the highest-yield and highest-risk slice of that growth, and the RBI has already intervened once by raising risk weights on it — regulatory action is a live variable, not a tail risk. Second, the mirror image of industry’s decline is that corporate credit is now the underpenetrated pool. If a private capex cycle does arrive, the banks positioned in corporate lending have the most room to grow into it.
5
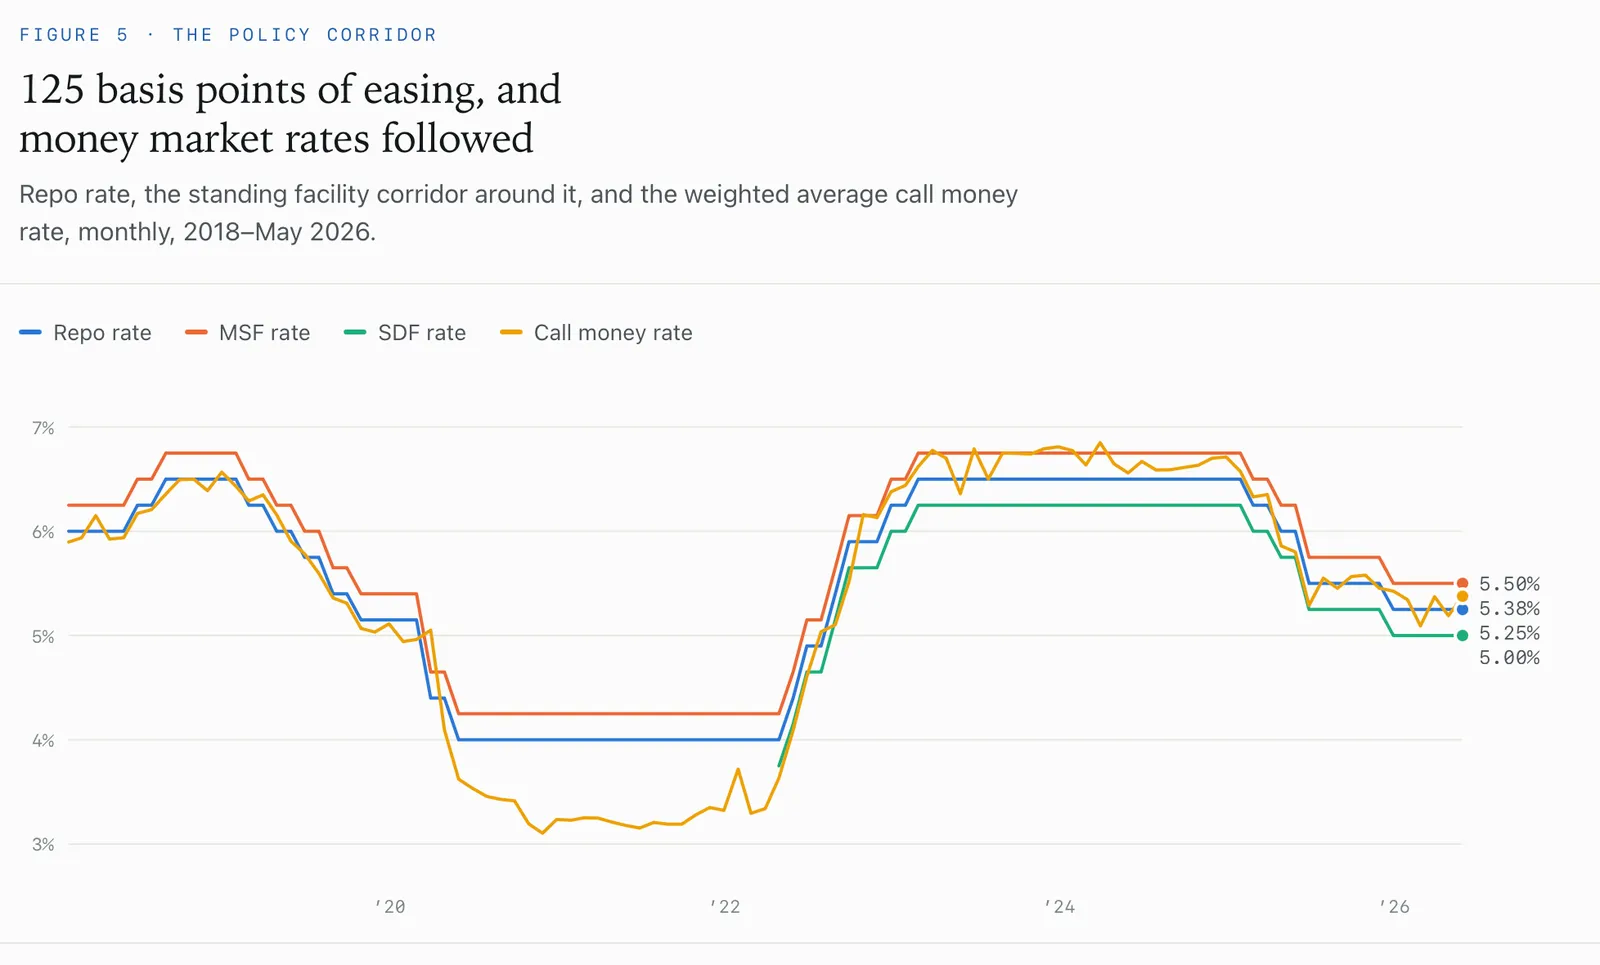
Falling policy rates cut both ways for a bank. They lift the value of the government bonds it already holds treasury gains, which flow to reported profit while lowering the yield on everything it lends from here.
6 savers are being paid very little to stay.
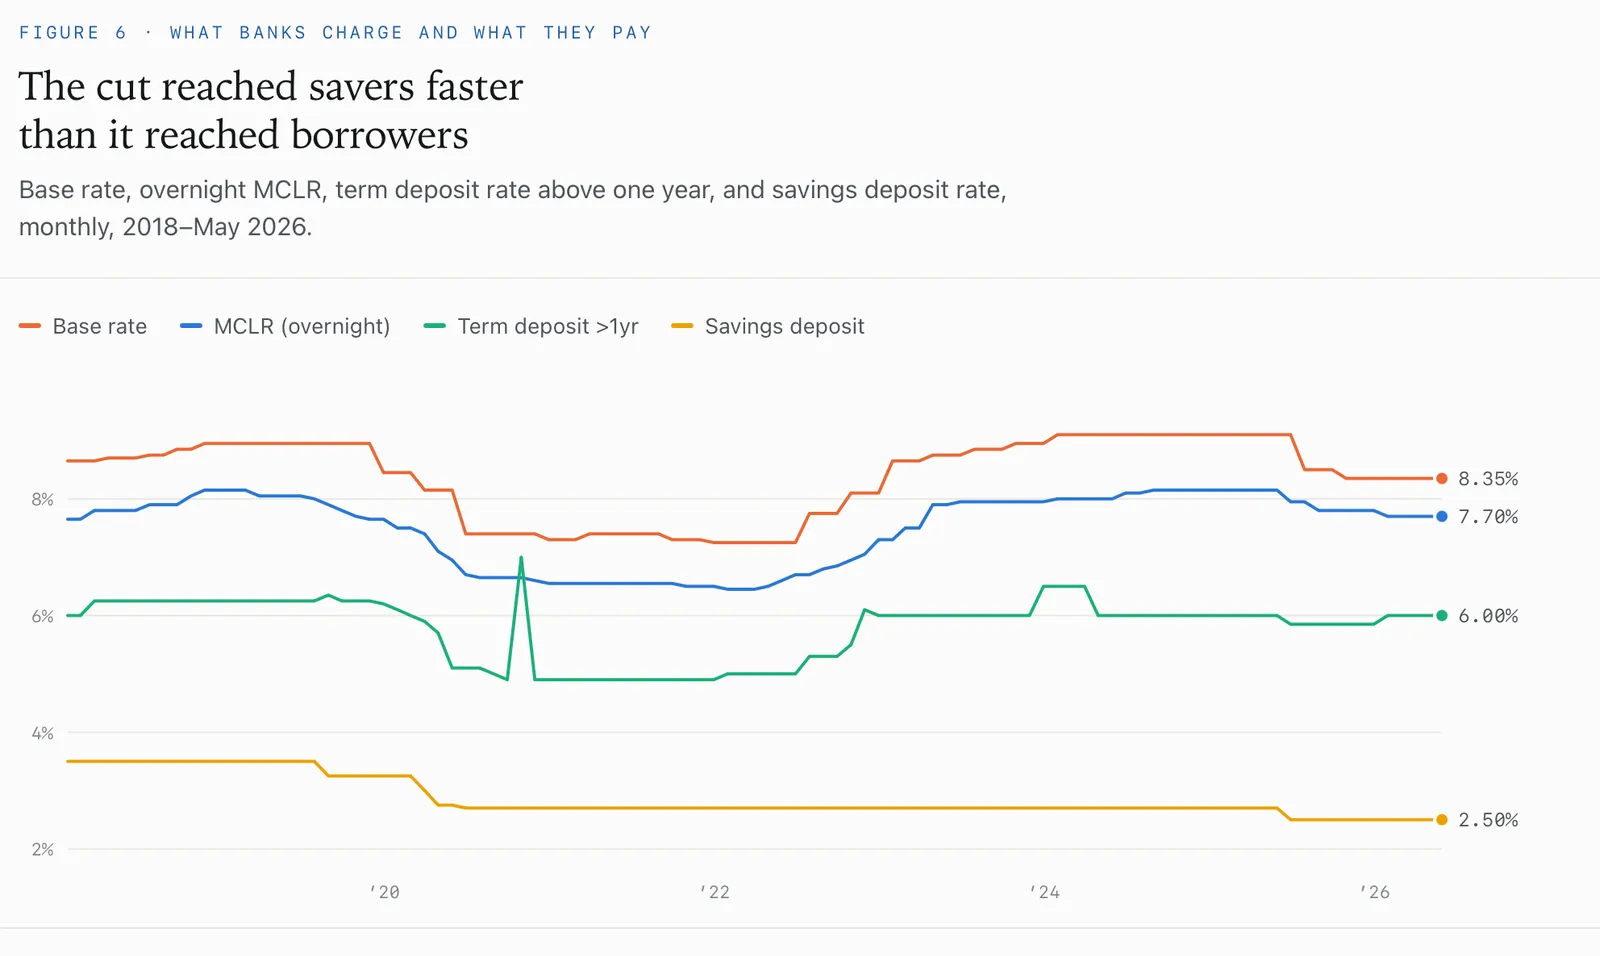
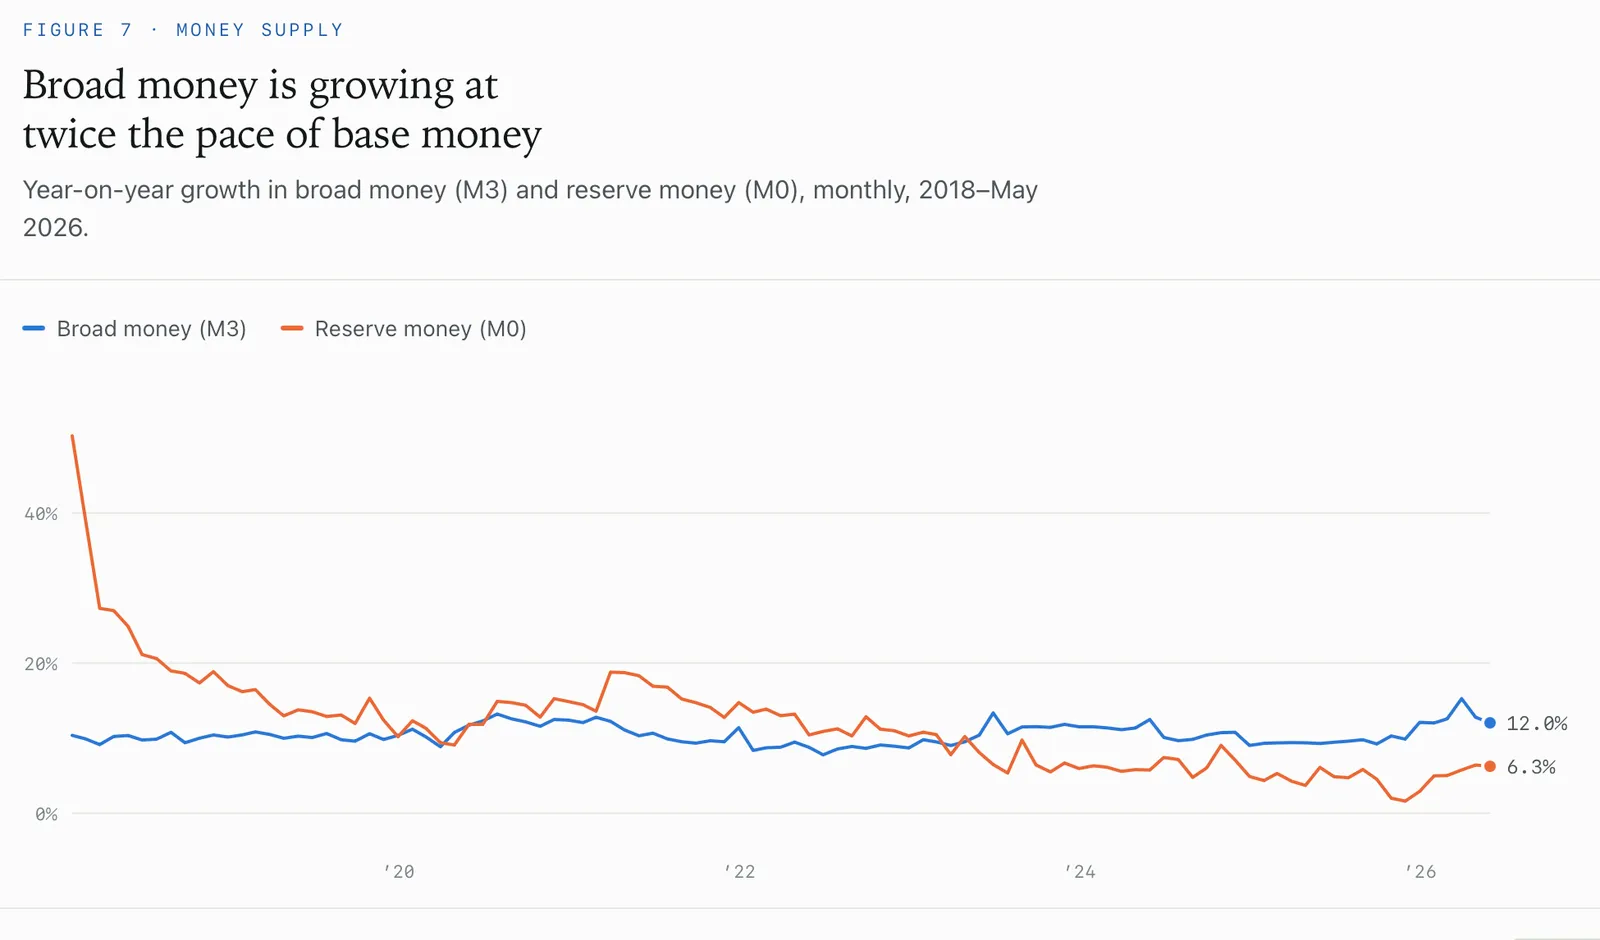
savers respond: a 2.5% savings rate against 12% broad money growth is a strong push into mutual funds, equities and insurance.
7 credit expansion in Figure 1 is being driven by commercial bank lending, not by central bank liquidity.
8
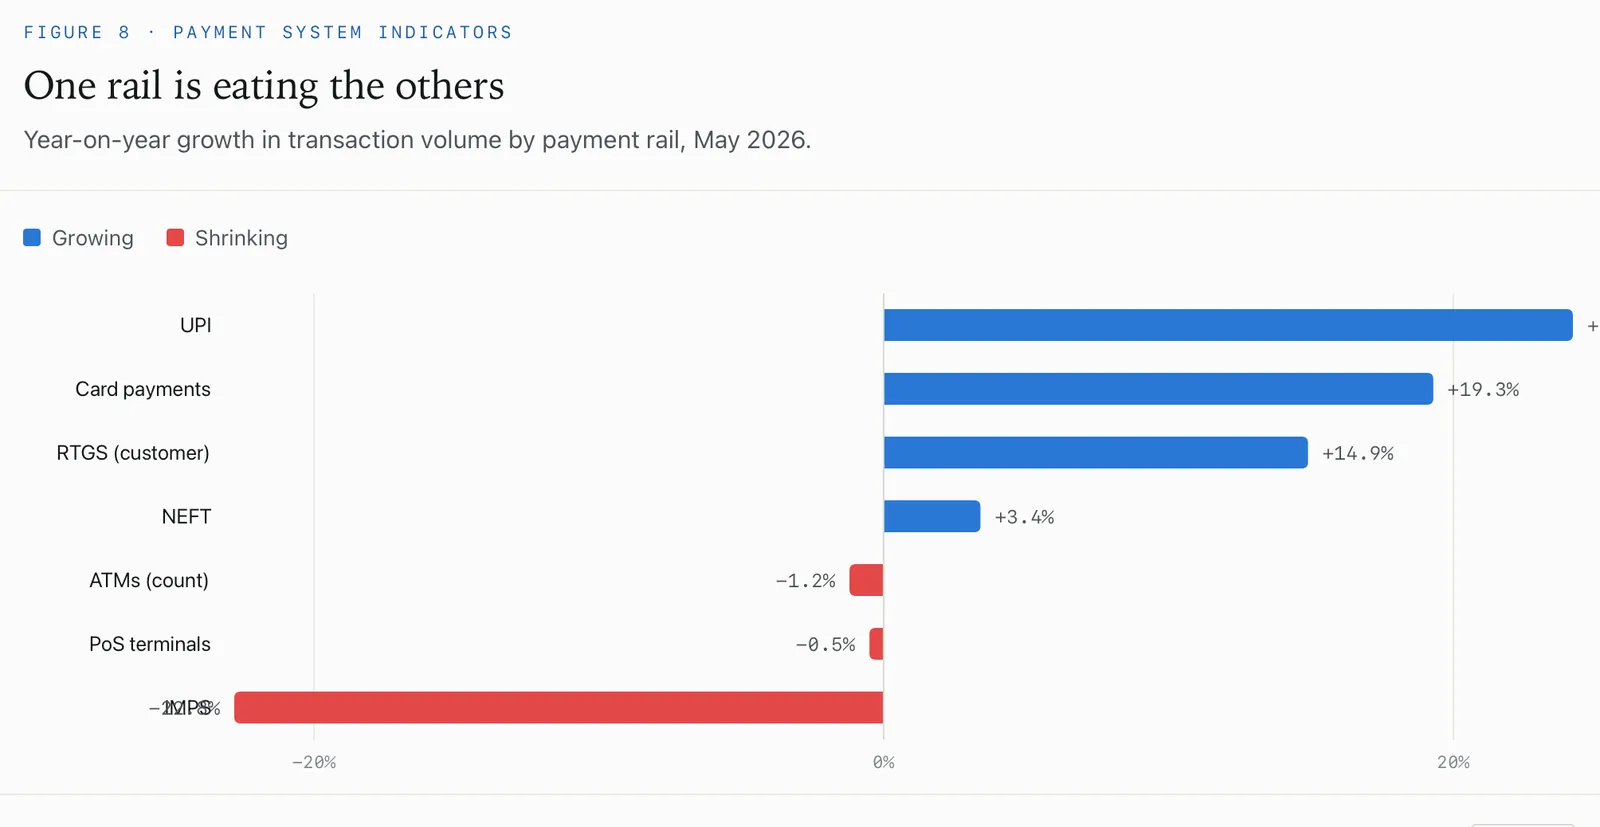
UPI is king and any new business has to ensure UPI is offered to stay relevant
Putting it all together
Credit demand is running ahead of deposit supply (Figures 1 and 2), and banks are managing the gap by paying savers very little (Figure 6) rather than by slowing lending. That is why margins look healthy today.
It also creates the two things worth tracking. Savers are leaving the deposit shortfall and the flows into mutual funds and insurance are the same phenomenon seen from two sides. And the loan book absorbing all this funding is now a household book, not a corporate one (Figure 4), which means the system’s asset quality is tied to jobs and wages rather than to the capex cycle, on loans too young to have been tested (Figure 3).
The near-term picture is good: rates are still falling (Figure 5), liquidity is ample (Figure 7), and growth is real. The questions are what deposits cost when the competition for them starts in earnest, and how the 2025–26 vintage of retail loans performs when it seasons.
Before you leave
Tremendous amount of work goes in producing content like this consider upgrading.
This is a record of the author's thinking in September 2026, kept as written. It is not a recommendation to buy or sell, and the author may hold the securities discussed. See the disclosures.