Shilpa Medicare
First the disclaimer
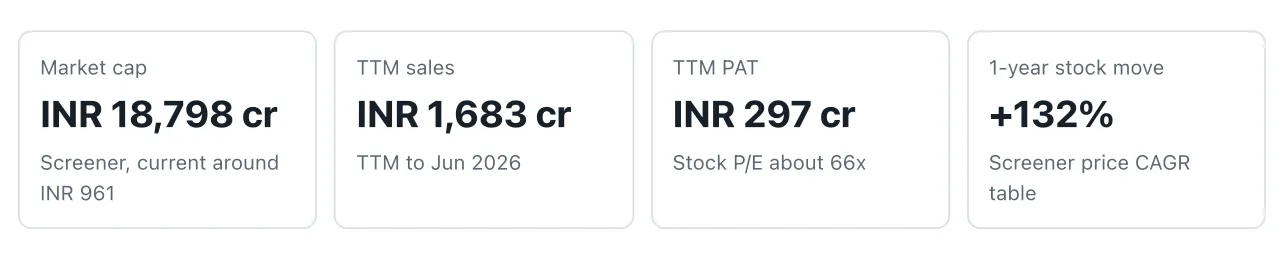
Prepared for: personal research use. Date: September 2026 Price: INR 961.15
Business Snapshot
Shilpa began as an API manufacturer and has long been associated with oncology. The current company is trying to become a broader specialty pharma and integrated CDMO platform across small molecules, formulations, biologics, ADCs, peptides and recombinant albumin.
Where the business is today
Q1 FY27 was the fourth consecutive record quarter for revenue and EBITDA. Consolidated revenue was INR 469 cr, EBITDA INR 139 cr, and EBITDA margin 30%. Reported PAT was INR 101 cr, helped by a tax reversal; management said normalized tax should move toward about 25%.
Segment evidence
Q1 FY27 segment momentum was broad: API revenue was INR 260 cr including captive demand, formulation revenue was INR 198 cr with more than 100% YoY growth, and biologics revenue was INR 52 cr with 42% YoY growth. The official presentation’s consolidated revenue breakup shows API INR 216 cr, formulations INR 198 cr and biologics INR 52 cr.
Why Capability Could Be Real
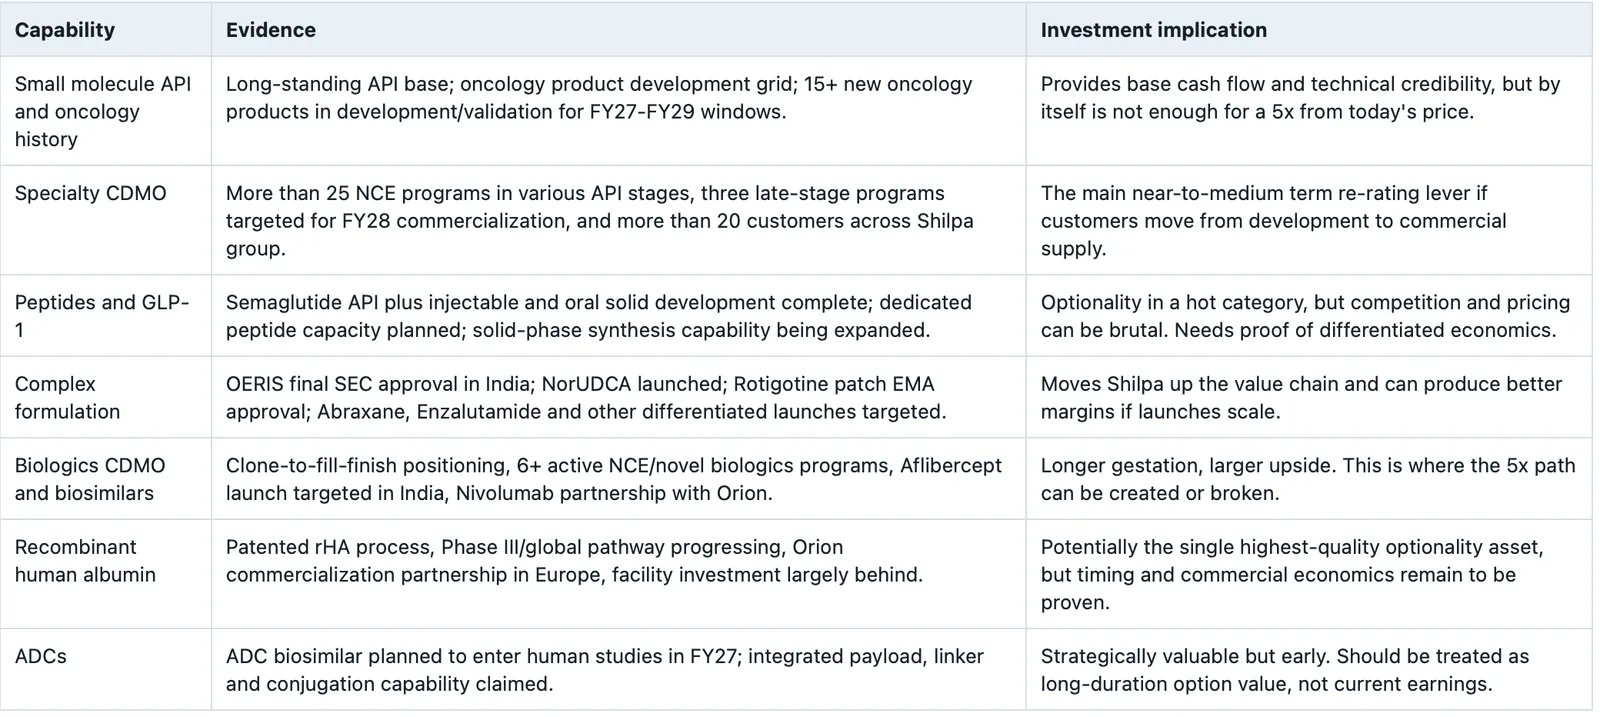
Shilpa’s positive case rests on breadth plus integration. Many Indian pharma companies can claim one piece of the puzzle: API chemistry, formulation development, injectables, biologics, or manufacturing services. Shilpa is unusual because it is attempting several of these under one operating architecture.
Peer Comparison
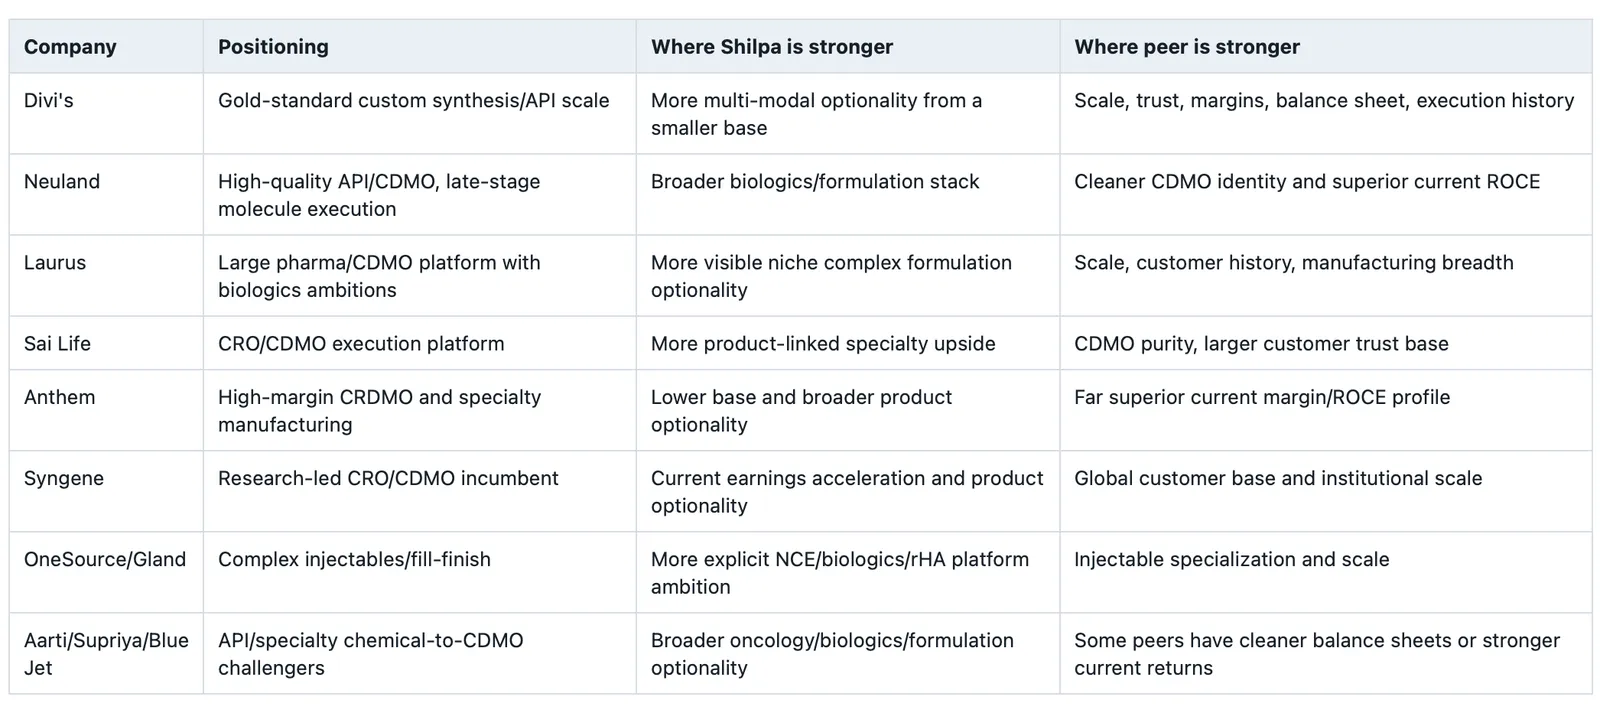
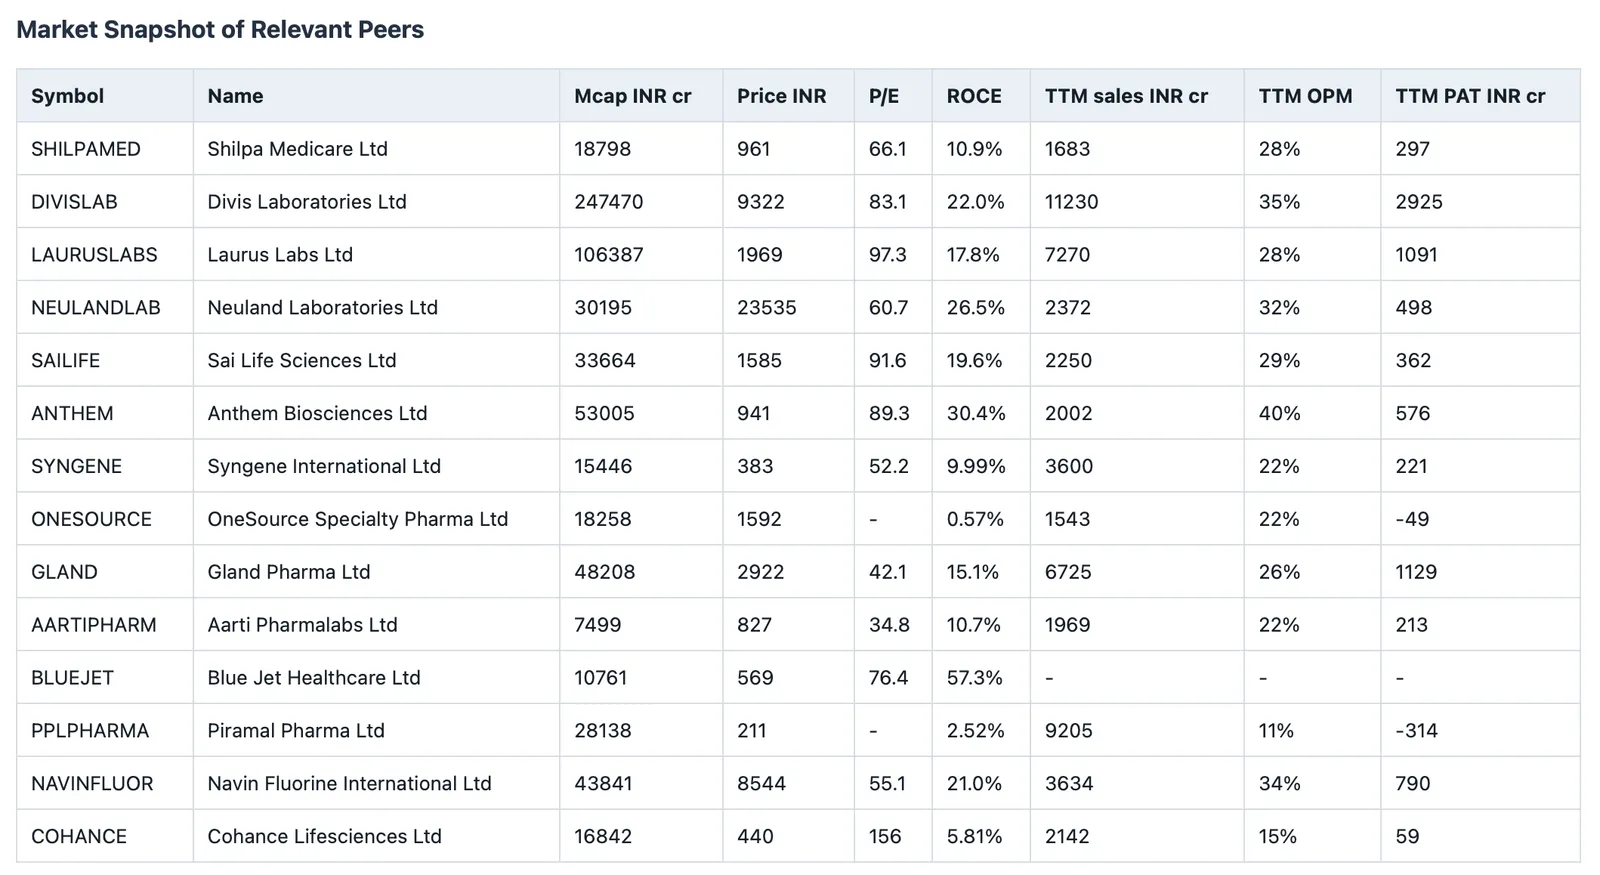
Shilpa should be benchmarked against several different peer sets, not one. Against Divi’s/Anthem/Sai/Neuland, Shilpa is much smaller and less proven in commercial CDMO scale. Against Aarti/Supriya/Blue Jet-type challengers, Shilpa has broader modality breadth. Against OneSource/Gland, it has less scale in injectables but more disclosed novel-product optionality.
Financial Quality
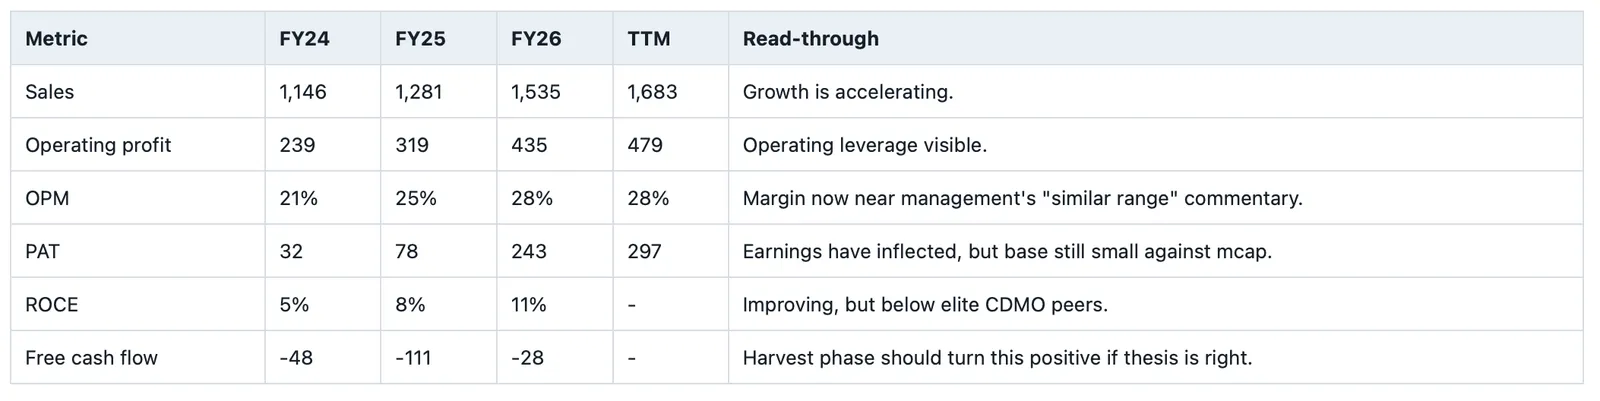
The recent numbers are excellent, but the historical financial quality is mixed. Sales grew from INR 1,146 cr in FY24 to INR 1,535 cr in FY26 and INR 1,683 cr TTM. Operating margin improved from 21% in FY24 to 28% in FY26/TTM. PAT moved from INR 32 cr in FY24 to INR 243 cr in FY26 and INR 297 cr TTM.
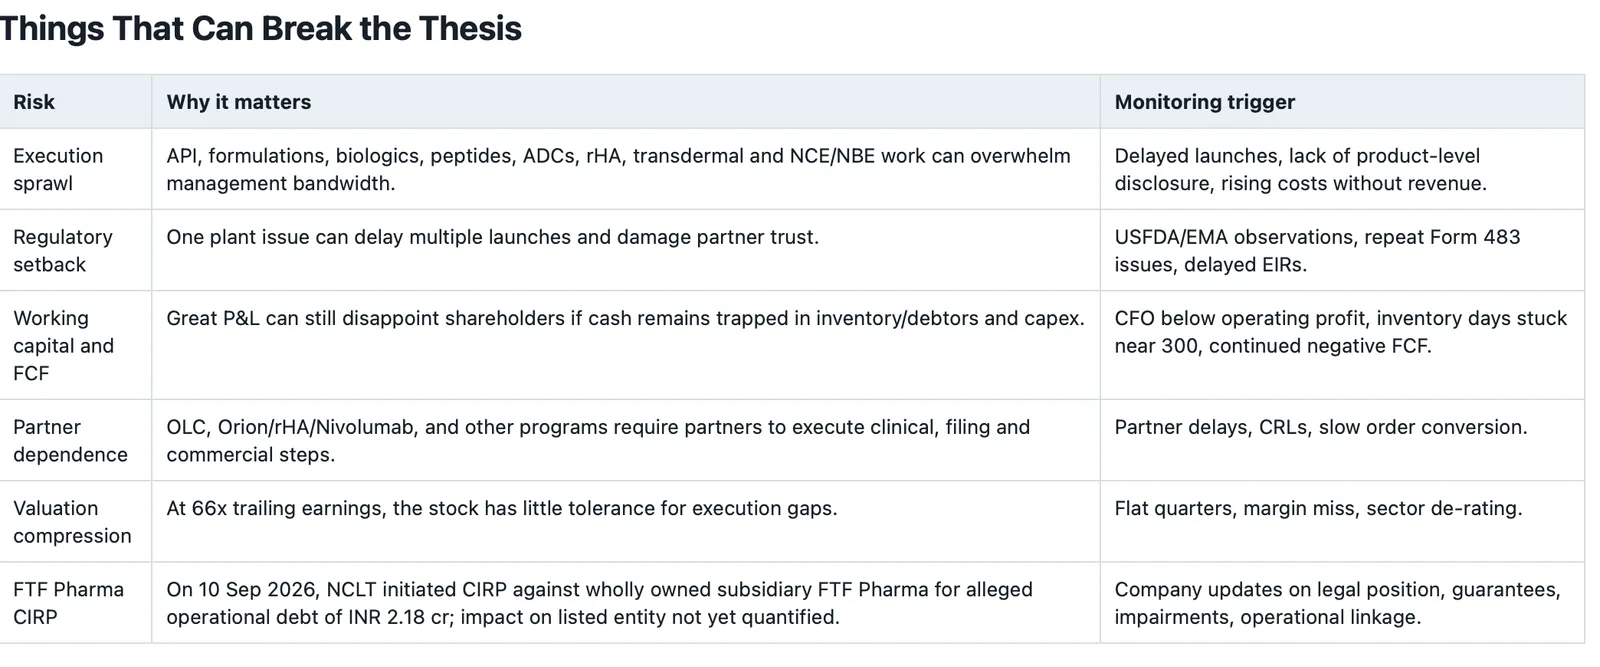
The flip side is capital intensity. Borrowings remain material at INR 660 cr in FY26, CWIP was INR 884 cr, and free cash flow has been negative for most of the last decade because Shilpa has been building capacity ahead of revenue. Working-capital metrics are not light: FY26 debtor days were 123 and inventory days were 291. That is manageable only if the new assets really scale.
Hard Answer
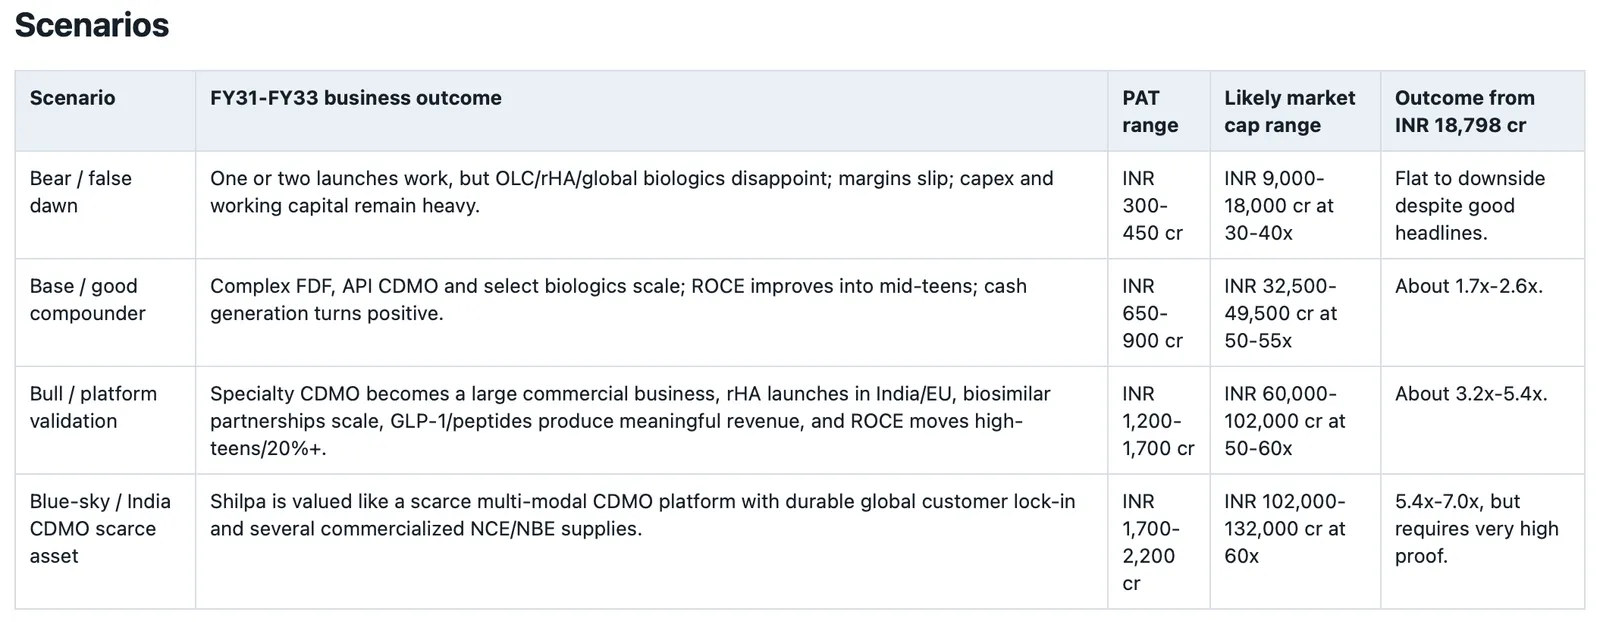
Can Shilpa be 5x in 5-7 years? Yes, but it is not a base-case outcome from INR 961. It requires multiple options to mature together: specialty CDMO, complex formulations, biologics, recombinant albumin, peptides/GLP-1, and at least one or two globally relevant partnerships.
Has price moved too fast? For an easy 5x, yes. The stock is no longer priced like a neglected turnaround. It is now priced like a company entering harvest mode, but before the full harvest is proven in free cash flow and high-teens/20%+ consolidated ROCE.
Most realistic framing: Shilpa looks like an asymmetric, execution-heavy compounder where 2x in 2-4 years is much easier to underwrite than 5x in 5-7 years. A 5x remains possible if the market keeps valuing it like a scarce Indian CDMO/complex-biologics platform and PAT compounds above 30% for long enough.
What Must Be True for 5x
1. CDMO must become commercial, not just developmental. Management says there is only one commercial CDMO product today and more than 25 NCE programs in development. For 5x, this must convert into recurring commercial manufacturing revenue, not just milestone/service income.
2. Biologics must move from option value to revenue engine. INR 52 cr Q1 FY27 biologics revenue is promising, but a 5x equity outcome likely needs biologics revenue to be several multiples of today’s run-rate, with global partners and acceptable margins.
3. Recombinant albumin must validate. rHA is the cleanest “Sajal-type” optionality: difficult, long-gestation, potentially differentiated, and not easy for every peer to copy. But it must clear clinical/regulatory/commercial hurdles.
4. Free cash flow must turn decisively positive. The historic criticism has been capex without enough cash conversion. A genuine platform should start self-funding growth, reducing the need for frequent equity/debt support.
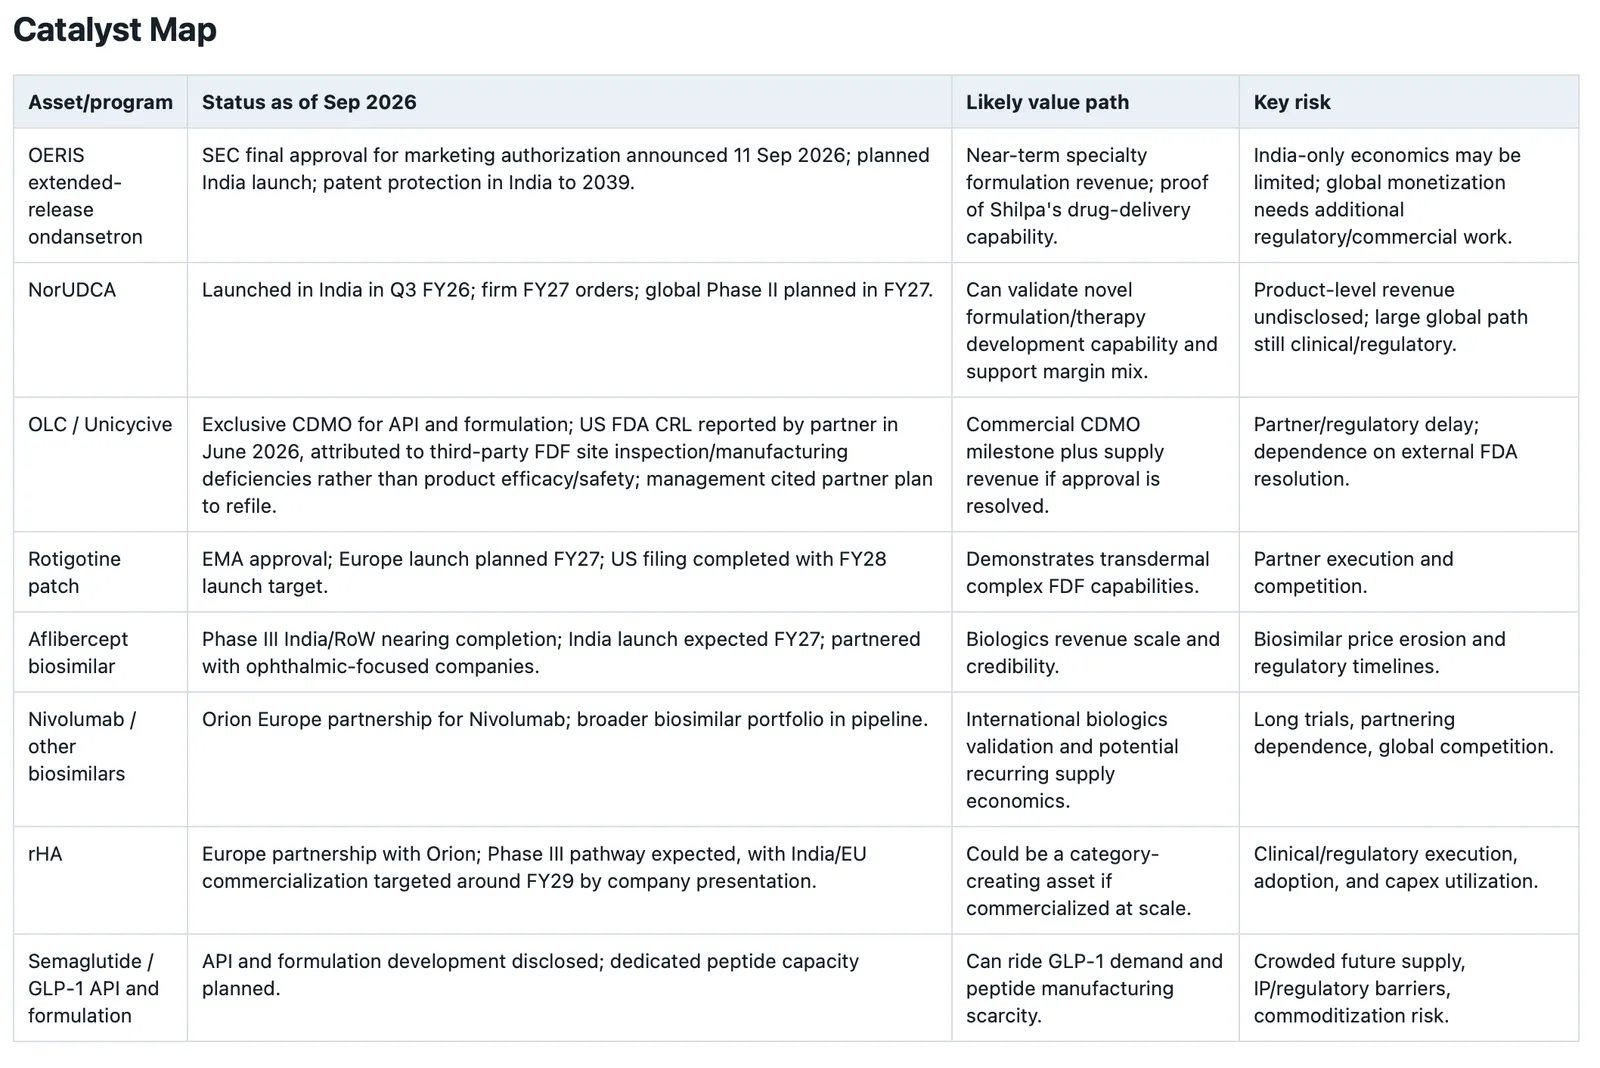
5. Regulatory execution must stay clean. Shilpa’s own management named regulatory surprise as the major thing that can slow growth. Given the old Jadcherla experience and current complexity, this remains the most important non-financial risk.
Conclusion
Shilpa is one of the more interesting Indian pharma capability stories because it combines oncology history, CDMO optionality, complex formulations, biologics, peptides and recombinant albumin. The Sajal framework fits unusually well: this is about whether years of reinvestment are now turning into a higher-return platform.
But the stock has already moved from “the market is ignoring the setup” to “the market is paying for early proof.” At INR 961, Shilpa needs sustained execution to justify even the current multiple, and needs exceptional execution to become a 5x in 5-7 years. I would underwrite it as a serious 2x-to-3x candidate if evidence continues, with a 5x path only in the bull case where rHA, biologics and commercial CDMO all work.
Not a recommendation but my attempt to understand the position wrt to future
Sources

ValuePickr Shilpa Medicare thread
Shilpa investor presentation and transcript page, including Q1 FY27 presentation and Q1 FY27 concall transcript dated 5 Aug 2026.
Shilpa Q1 FY27 earnings call transcript.
Shilpa Q1 FY27 investor presentation.
Shilpa FY26 annual report.
BSE/Shilpa OERIS SEC approval announcement, 11 Sep 2026.
BSE/Shilpa FTF Pharma CIRP disclosure, 10 Sep 2026.
Unicycive investor relations, including 30 Jun 2026 OLC CRL update and subsequent business updates.
Screener Shilpa Medicare consolidated financials and peer Screener pages for market snapshot.
This is a record of the author's thinking in September 2026, kept as written. It is not a recommendation to buy or sell, and the author may hold the securities discussed. See the disclosures.