Q2/Q3 2024 Earnings Review - 1
I review business I am interested in quarterly, once in six months or yearly, Here is my take on each one
We will do over 3 or 4 posts in some logical grouping and as results are announced
-
Paypal
-
Google
-
Zomato
-
Technology One
-
E2E Networks
-
Laurus Labs
-
Ami Organics
-
Piramal Pharma
-
Neuland Labs
-
JM Financial
-
CDSL
-
EPCAK
-
Swiss Military Consumer
-
KPR Mills
-
Aditya Vision
Paypal
To understand the business read this , Q3 earnings presentation is available here and the earnings release is available here
Summary
-
Payment volume increased by 9%
-
Revenues increased by 6%
-
Net income decreased by 1%
-
EPS diluted increased by 6% due to buy back done by management, they have reduced number of shares by 7% in a year
As a investor we would like to see progress on few key variables
- Increasing active account and transaction volumes
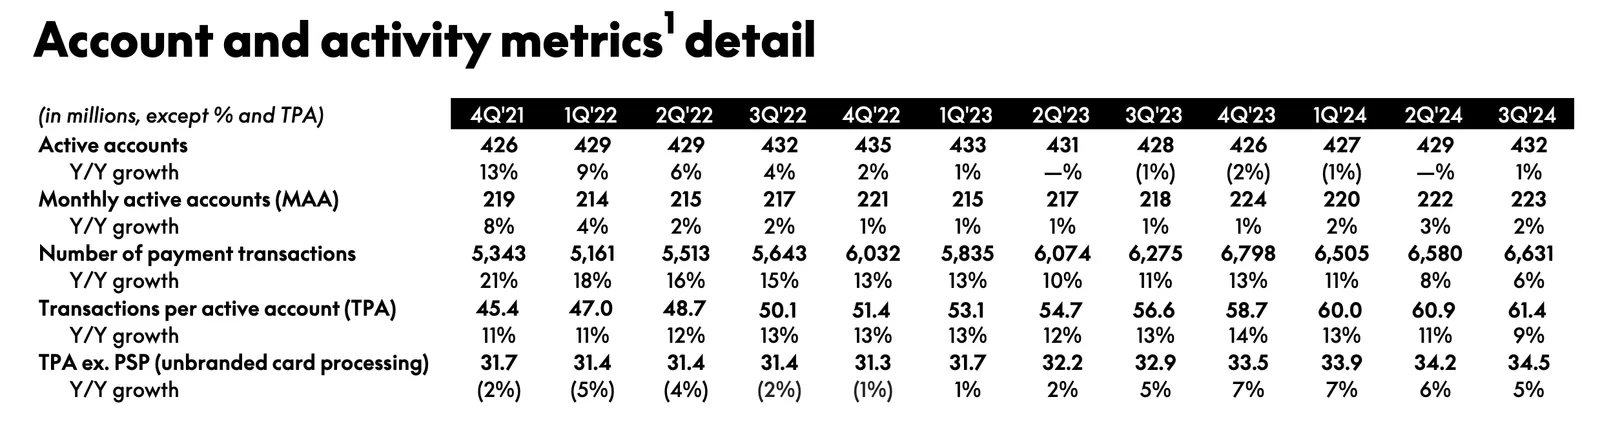
Active accounts are flat, however number of payments and transactions per active accounts are heading in right direction
- Take rate improving or not declining
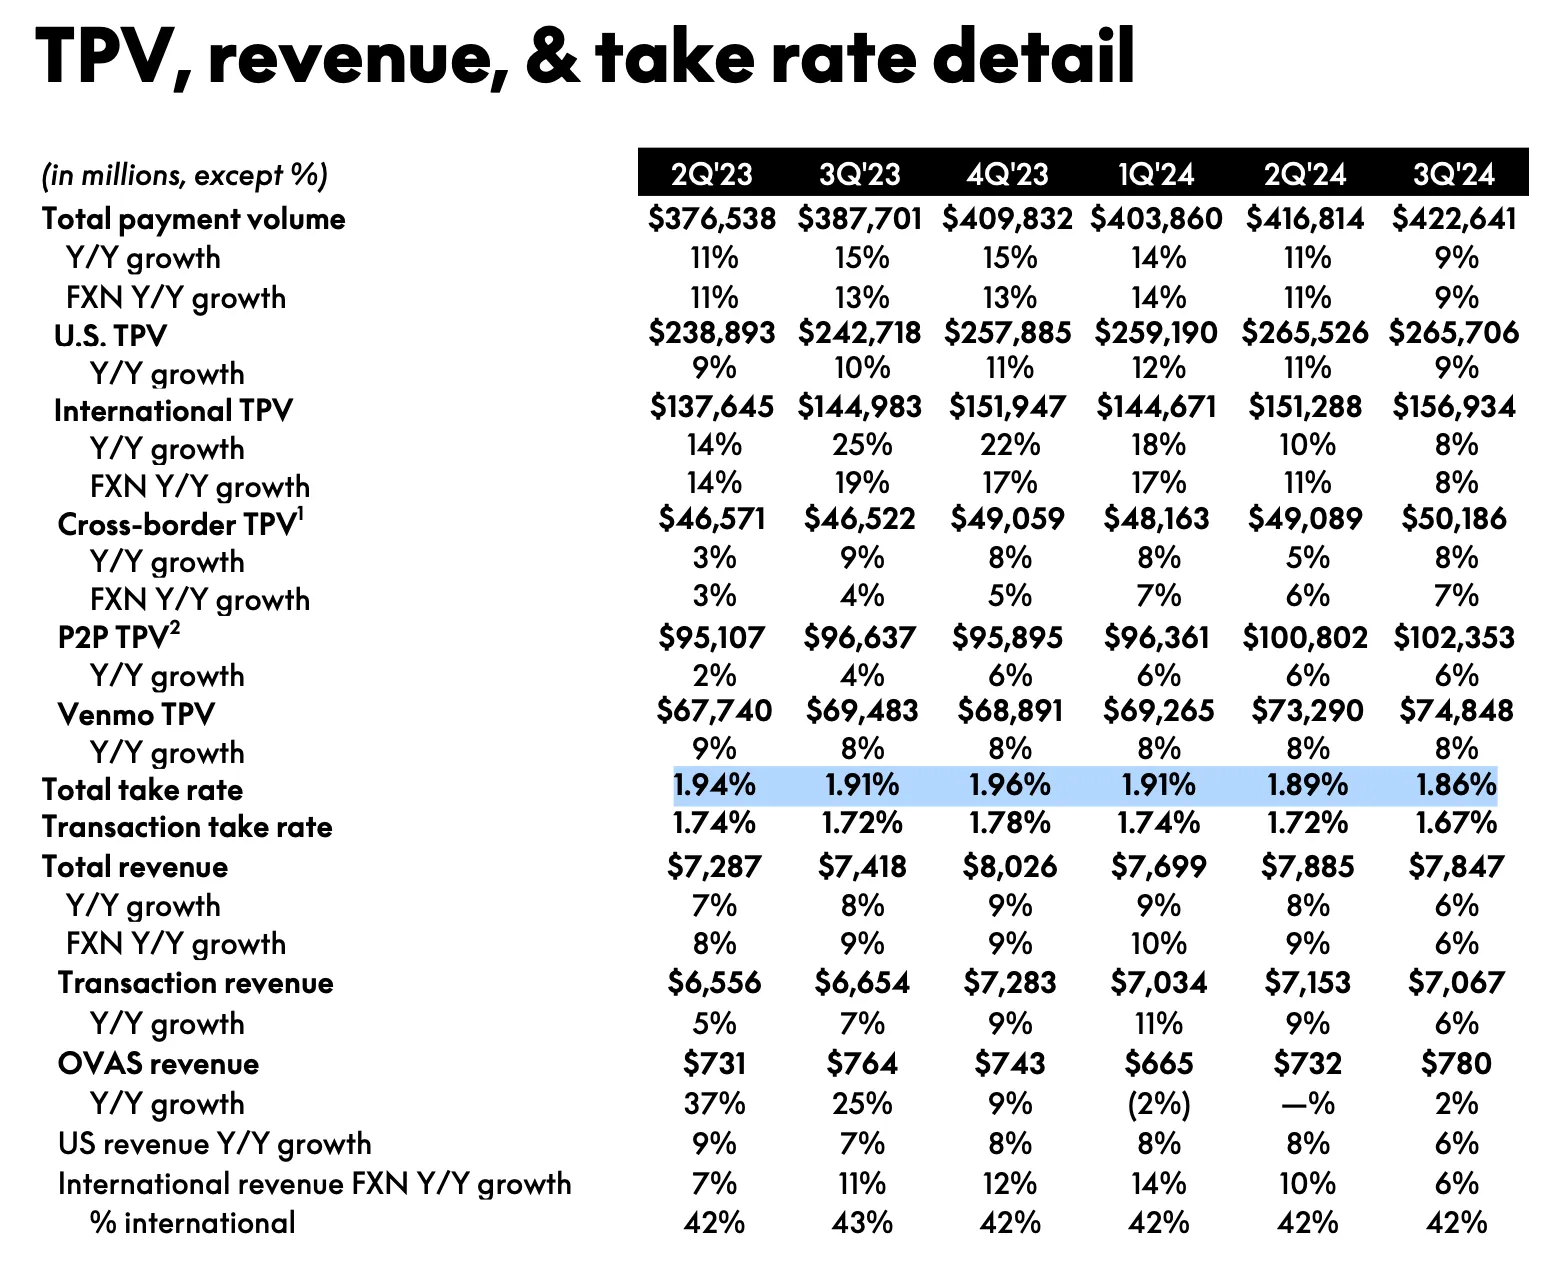
Paypal’s take rate is sliding down, the management indicated that Transaction take rate negatively impacted as branded checkout is becoming a lower proportion of overall revenues.
- Capital allocation
Paypal is continuously using free cashflow to buy back shares which is a great use of their cash
Overall the decent quarter for them.
To understand this business read this , there earnings release is available here and the Sundar’s note is available here
Summary
Revenue
-
Total Revenue: $85.2 billion (13% year-over-year growth)
-
Google Services: $76.5 billion (13% growth)
-
Google Cloud: $11.4 billion (35% growth)
-
YouTube Ads: 12% growth (brand and direct response)
-
Network Revenues: -2% growth
Operating Results
-
Operating Income: $25.9 billion (21% margin)
-
Net Income: $20.6 billion
-
Earnings Per Share (EPS): $30.69
Growth Metrics
-
Search Queries: Increased due to AI-powered features
-
YouTube Engagement: 2 billion+ monthly active users
-
Google Cloud Growth: 30% deeper product adoption with existing customers
-
Waymo: 1 million+ fully autonomous miles weekly, 150,000+ paid rides
Capital Expenditures
-
Q3 CapEx: $8.1 billion (data centers, AI infrastructure)
-
YTD CapEx: $23.4 billion
Cash and Liquidity
-
Cash and Equivalents: $178 billion
-
Free Cash Flow: $16.4 billion (Q3), $45.6 billion (YTD)
Guidance
-
Q4 Revenue Growth: 12-15% (year-over-year)
-
Full-Year CapEx: $30-33 billion
the results were better than my anticipation. For Google they key item is to check how can they combat attack on their search revenues from ChatGPT and others
The other key tracking item is monetisation of Waymo and Wing, as they will bring back top line growth to 20%+
Waymo is now a clear technical leader within the autonomous vehicle industry and creating a growing commercial opportunity.
Over the years, Waymo has been infusing cutting-edge AI into its work. Now, each week, Waymo is driving more than 1 million fully autonomous miles and serves over 150,000 paid rides — the first time any AV company has reached this kind of mainstream use.
Wing, our drone delivery company, recently passed the 1-year anniversary of scaling its partnership with Walmart in the Dallas-Fort Worth area, now operating in 11 stores and serving 26 different cities and towns.
Overall a fantastic quarter for them
Zomato
To understand the business read this ignore valuation done by Sir
Impressive topline growth continues, their earnings release can be found here
-
Food delivery Gross Order Value (GOV) grew 21% YoY (5% QoQ)
-
Quick commerce GOV grew 122% YoY (25% QoQ), and
-
Going-out GOV grew 171% YoY (46% QoQ); like-for-like GOV grew 139% YoY (29% QoQ)
-
B2B business Hyperpure’s Revenue grew 98% YoY (22% QoQ)
My thinking is that quick commerce is probably having its UPI moment, let me expand that thought.
When UPI was introduced at least I thought it would be only used for micro payments (under INR 1,000) but today I am seeing this is become default payment method for all payments under INR 100,000 - 200,000 similarly for quick commerce my initial thinking was that it would be used for small items which someone needs quickly to accomplish a task.
I think with its adoption and expanding categories it may become a default way to shop, read below deep dive
and just like UPI we have three big winners - Paytm, Phonepe and Google pay. In 4-5 years we may have 4-5 quick com players becoming very big
Technology One
Technology reports detailed results once in 6 months , my write up (paid) includes review of them. We will revisit this company in February next year
E2E Networks
This company is growing fast and thats why there is certain hype about it, you can read my take on it here
Who are they comparing themselves, clearly lofty comparison
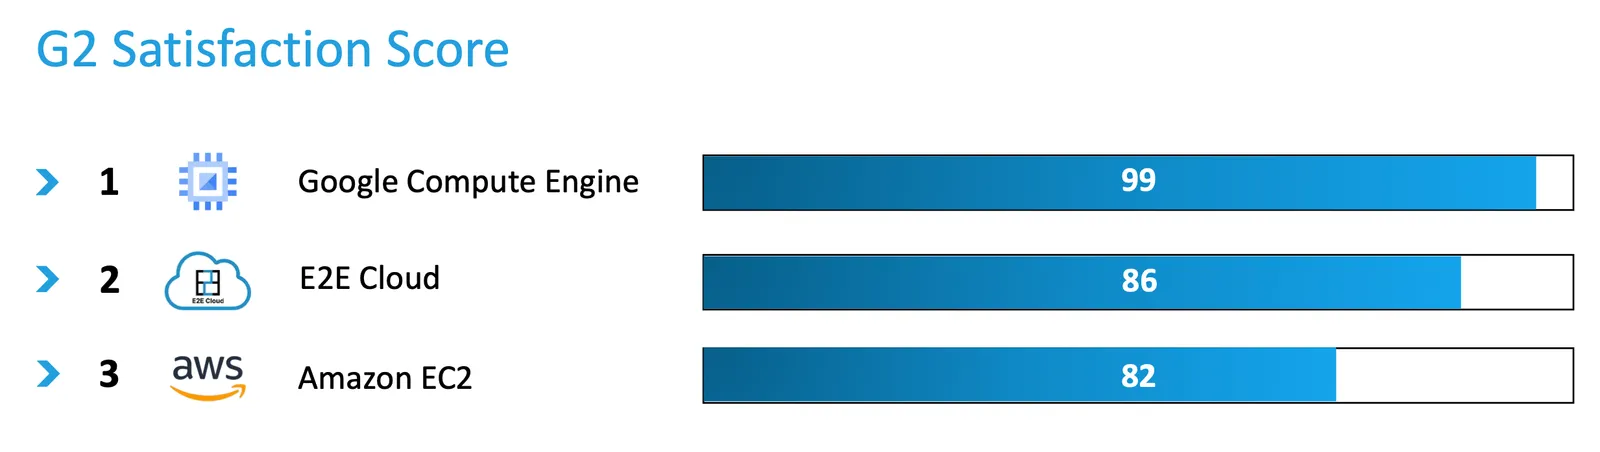
Key Highlights
-
Revenue Growth: Total revenue for Q2 FY25 was ₹484 million, reflecting 120% year-over-year growth.
-
EBITDA Growth: EBITDA for the quarter was ₹314 million, showcasing 81% year-over-year growth with a margin of 66.1%.
-
Net Profit Growth: Net profit reported was ₹121 million, demonstrating 108% year-over-year growth with a 25% margin.
-
Earnings Per Share (EPS): Valuated EPS for the quarter was ₹7.8, marking a 98% increase year-over-year.
-
Fundraising: Successfully raised ₹456 million through the issue of equity shares
GPU Expansion
-
Recent Procurement: 256 H100 GPUs added to inventory.
-
Non-H100 GPU Expansion: Increased offerings of A40, A40s, L4 and L4s GPUs.
-
Total GPUs: Approximately 700-800 GPUs (including recent additions).
-
GPU Utilization Rates: Continues to see robust demand, with utilization rates although decreased from last quarter
Ground reality
However it has only 3 open Job positions on its website, that too just 1 tech position offering 3-6 lakhs per annum. Specialized AI/ML and cloud GPU solutions require skilled professionals
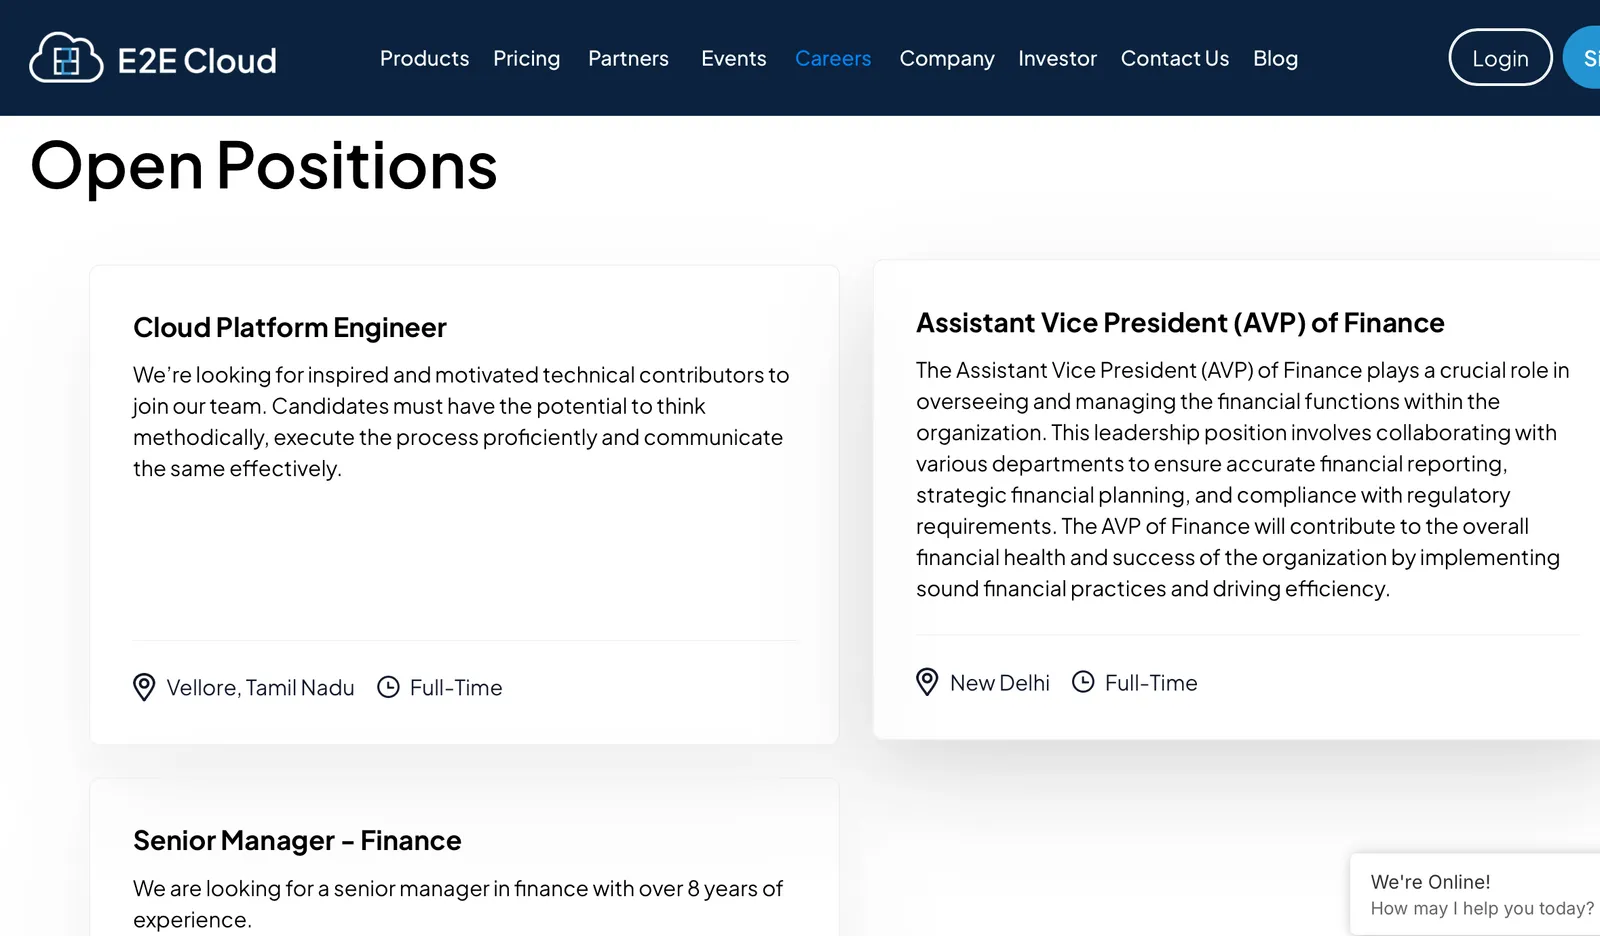
I would be valuing it more as a company who is renting NVIDIA’s GPU. my assessment may be harsh or wrong
I try to end every post with something from gallery
This is a record of the author's thinking in October 2024, kept as written. It is not a recommendation to buy or sell, and the author may hold the securities discussed. See the disclosures.