ASX PXA
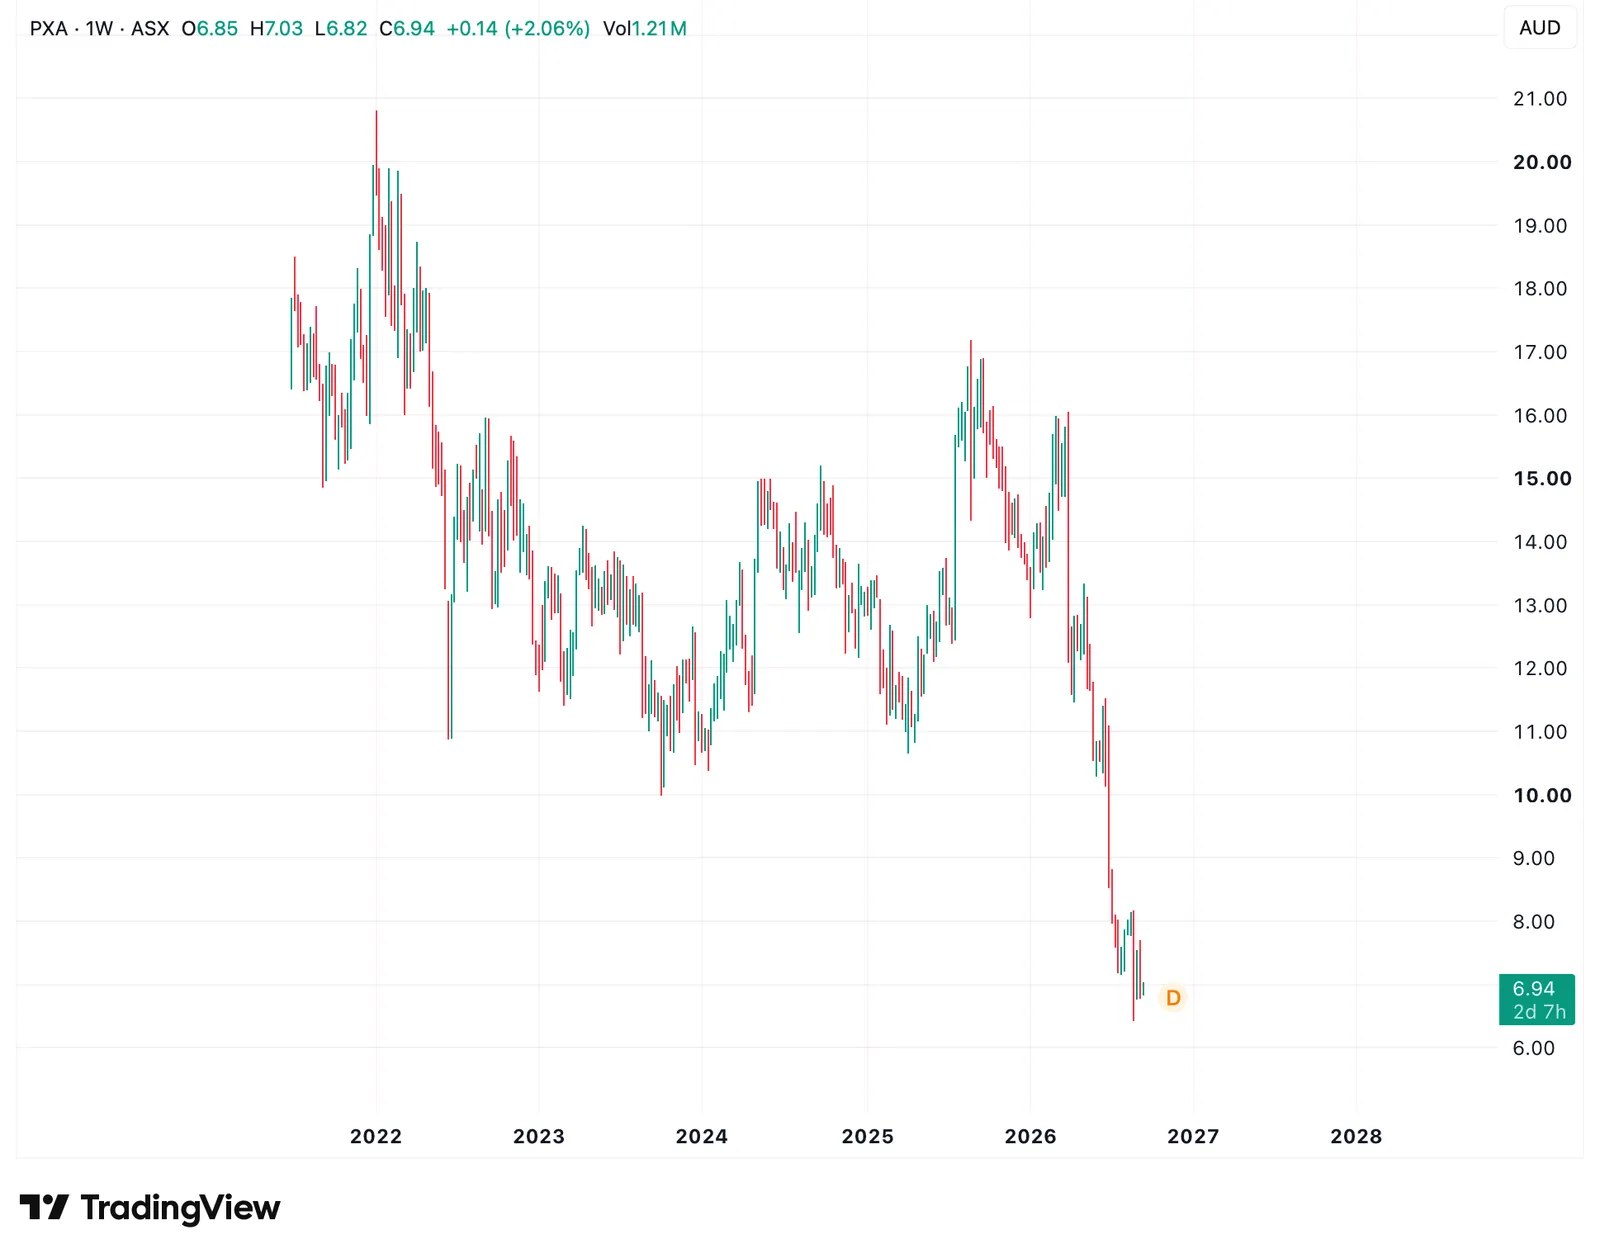
A look at PEXA Group stock ticker and the fall looks like is only going to stop at 0 :)
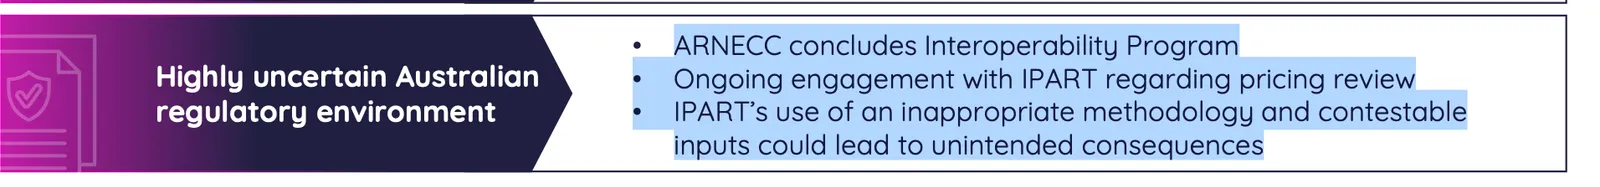
reason is this from page 4 of their FY26 presentation
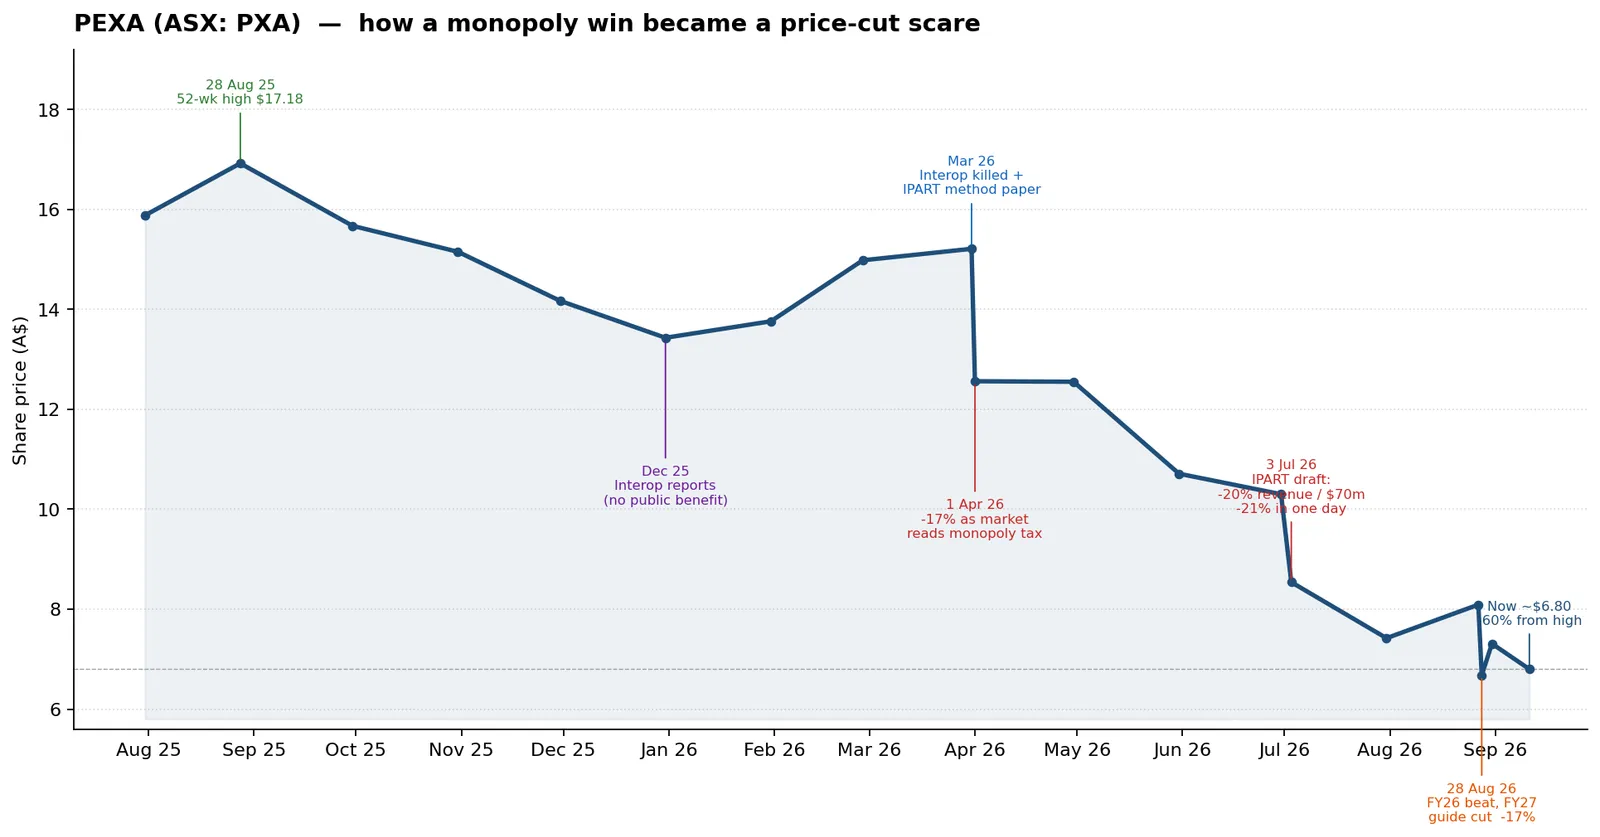
A better price graph is this
2010–2019: The Foundation years
PEXA was set up by governments and the banks to replace paper property settlements and bank cheques with an electronic system.Fees were kept fairly low while everyone was being moved onto the platform. IPART (the regular is who is reason for current meltdown) reviewed pricing in 2019 and said the fees were reasonable.PEXA was then sold for about $1.6bn.
2020–2024: Govt lets build a competitor
Governments then spent years trying to make PEXA and Sympli (almost zero market share) interoperable, so that both platforms could be used in the same property settlement. It didn’t work,The whole thing was paused in June 2024.
2025: SaaS monopoly
PEXA is an effective monopoly (99% of e-conveyancing, 90% of all conveyancing). This was probably the high point for the investment case.The Australian business was strong. In UK the NatWest had committed to the UK platform so revenue will flow in future. Transaction volumes were doing fine too!
Investors viewed PEXA as:
Australian monopoly + UK growth option.
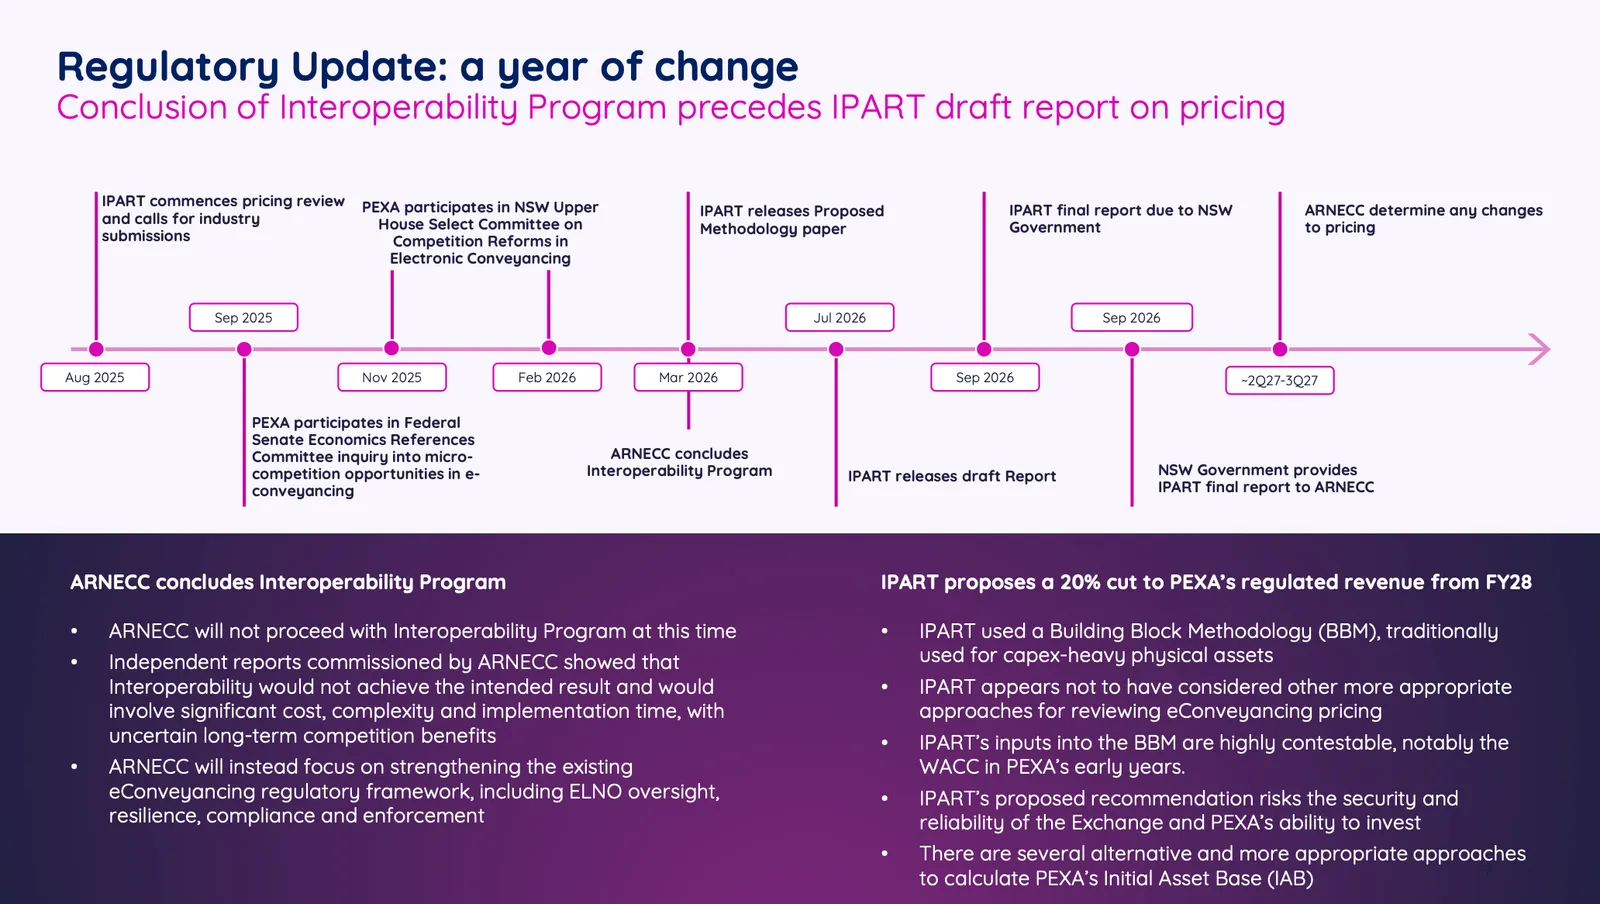
2025: Regulators propose cuts and add regulation
The IPART draft proposed:
-
roughly 20% less Australian revenue from FY28
-
about $70m less revenue
-
the main transfer fee falling from $146.30 to $92.71
-
prices then broadly moving with CPI from next FY
-
regulation applying to PEXA, but not to tiny competitor Sympli
PEXA thinks it is getting the hard end of the bargain
2026 and beyond
Assuming that in 2028 the worst case scenario plays out, and EBITDA would still be in range of AUD ~150mn so the stock is trading ~6 times if we take in EV/EBITDA and today’s price. Note no pricing impact till FY2027
The street has modelled quite a few pricing outcomes in a year
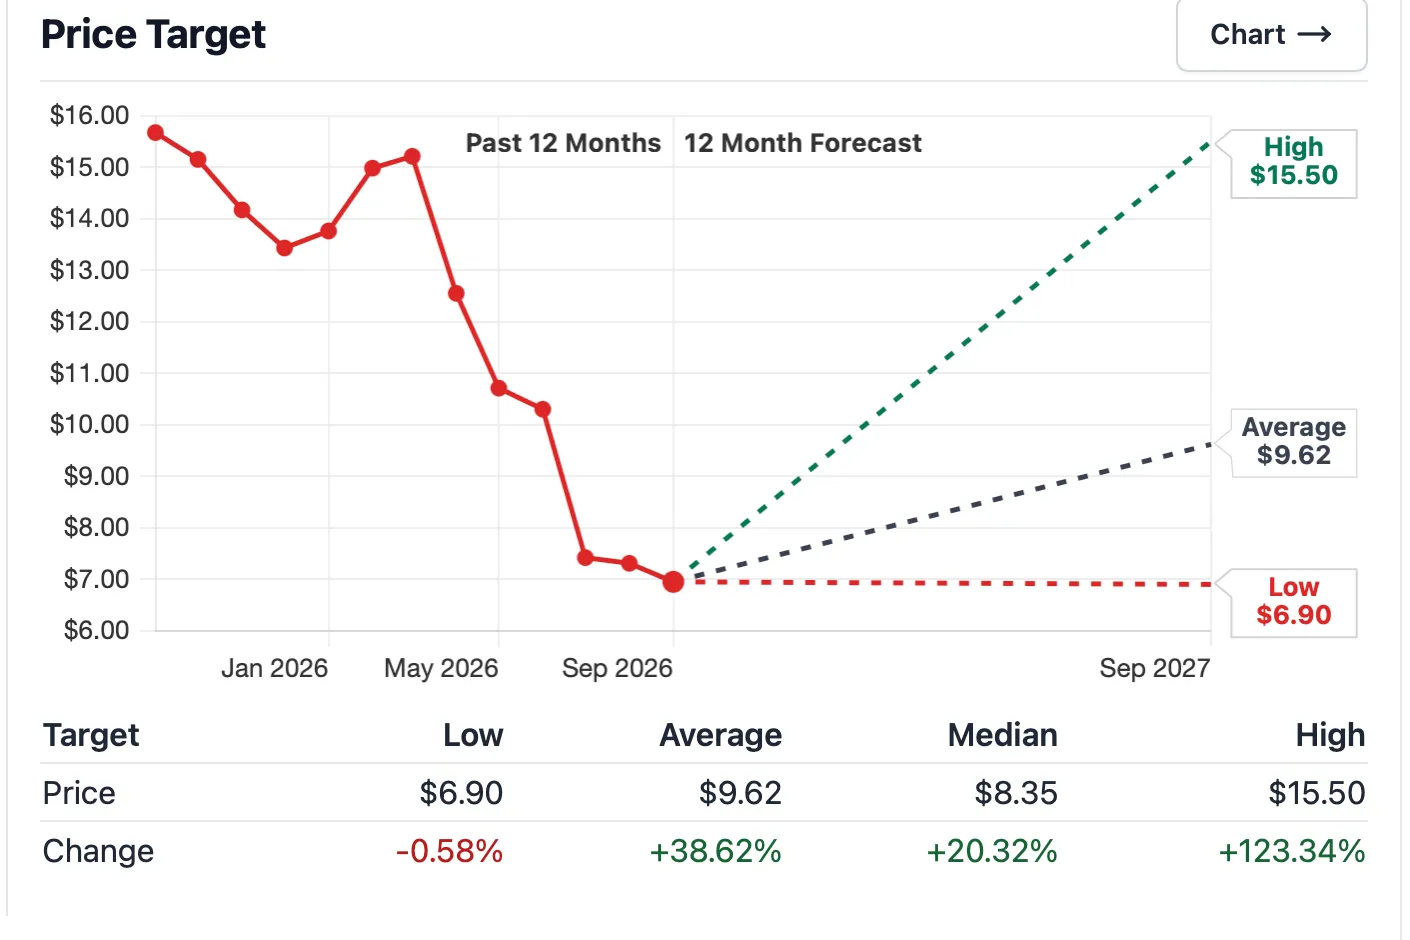
Current price is already close to worst outcome that street is anticipating and as bonus Directors have been buying the collapse,
-
1 Sep: Smith +10,550 at $7.17 (~$76k)
-
8 Sep: Lynch +12,064 at $7.45 (~$90k)
-
9 Sep: Richard +10,000 at $7.05 (~$71k)
To top this we are discounting the other “bets” wont pay off
-
PEXA clear
-
UK business
-
NZ entry
For me I will swing :)
This is a record of the author's thinking in September 2026, kept as written. It is not a recommendation to buy or sell, and the author may hold the securities discussed. See the disclosures.