Mini Dixon?
A $ invested in Dixon Technologies (NSE: DIXON) in 2019 has become $25 dollars in 2024, this from a contract manufacturer which operates at sub 5% net margin at best. What has been its secret sauce ?
-
Amazing scaling of operations (10X Sales from 2019)
-
Impeccable working capital management (Almost zero Cash Conversion Cycle)
-
Expansion of product categories and most importantly
-
Operating in India which is going to see massive uptake of consumer goods
One of the key consumer categories which is going to get 5-6X uptake in next decade is Air Conditioning (AC)
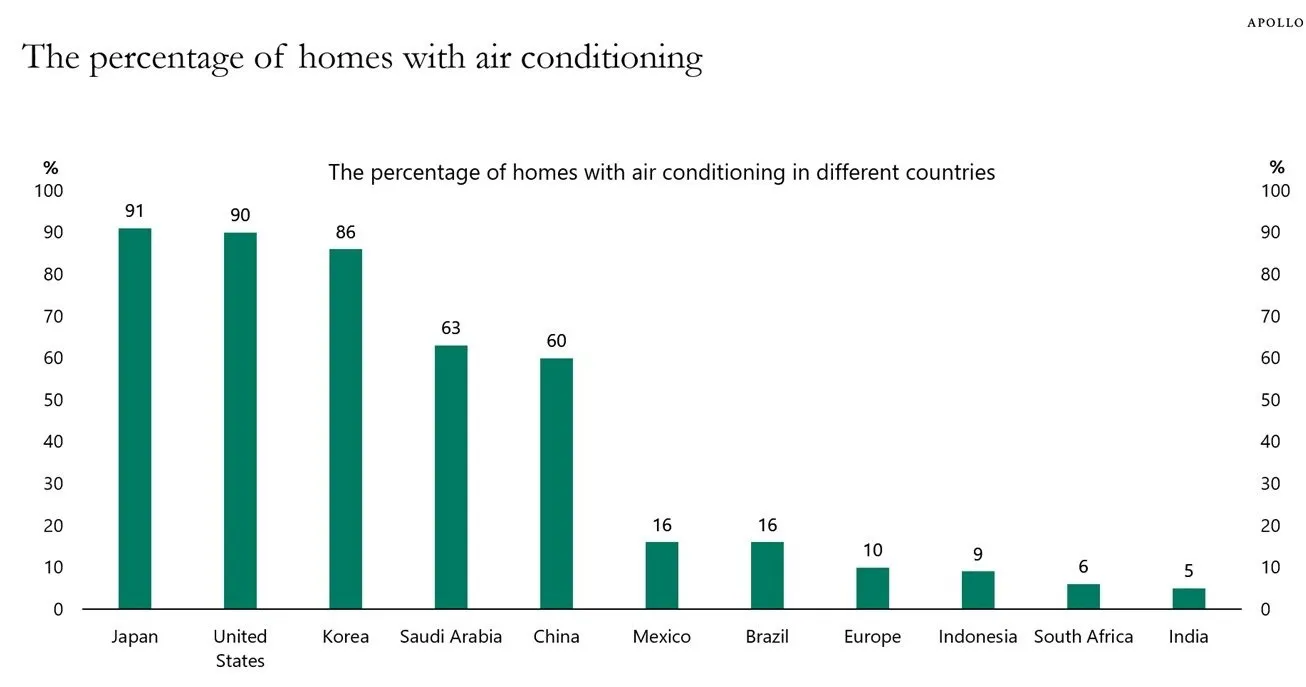
We will reach Mexico levels in about 8-10 years and may be China in 25-30 years, the opportunity size is humungous
So, on a long-term basis, we see the market is going to double every 4-5 years
EPACK Durable Limited is the second largest air-conditioned original design manufacturer (ODM) in India, The expertise of EPACK Durable lies in manufacturing a diverse portfolio of room air conditioners and small domestic appliances (SDAs). EPACK Durable works jointly with customer team and customizes the product according to their requirements
It has 3 manufacturing facilities located strategically in Dehradun, Bhiwadi, and Sri city. All the facilities enjoy strong backward integration offering cost competencies against its peers
There is significant lock in, once a customer is acquired it remains
They have 4 dedicated R&D centers and close to 70 plus employees in R&D team.
Revenue spilt
-
86% from ACs
-
14% from other appliances
New product launches
-
Air Coolers in January 2024
-
Fully Automatic Washing Machines, Room Oil Heaters, Air Fryer, Tower Fans, Induction Water Heaters and Hair Dryers in the coming quarters
Near term triggers from management commentary
This has been an exceptional quarter yet, but the best thing is even currently the market is selling the lowest amount of inventory. The inventories in the market are bare minimum. The forecast for next two quarters or our order book for next two quarters is also extremely healthy.
New Facility is not yet fully utilised at approximately 40-50% will ramp up to 80-90% next year
What are things an investor has to look out for?
-
Wafer thin profit margins, the net margins of the company are ~2%, so any operational mishap can make them unprofitable
-
In financial Q2 and Q3 of any year the company can’t utilise the capacity as ACs sales go down, management is trying to introduce other products so this should be key watch item for any investor
The company should do ~INR 2000 crores sales by March 2026 and should do ~100 crores of Net profit, When PG Electroplast Limited (NSE: PGEL) was at same level of sales and profitability it was valued at INR 4500 crores
Generally market is hungry for growth oriented business, With such strong tailwinds for Industry we expect company to do well.
I am invested
Happy Investing
This is a record of the author's thinking in September 2024, kept as written. It is not a recommendation to buy or sell, and the author may hold the securities discussed. See the disclosures.