Windlas Biotech Ltd
To get an introduction to this sector read below
Related: Indian Domestic CDMO Companies
Company History and Management
Windlas Biotech Ltd, incorporated on February 19, 2001, is a leading pharmaceutical contract development and manufacturing organization (CDMO) in India, headquartered in Dehradun, Uttarakhand. It has grown to become one of the top five players in the Indian CDMO industry, with four state-of-the-art manufacturing facilities and fifth one commenced in 2025
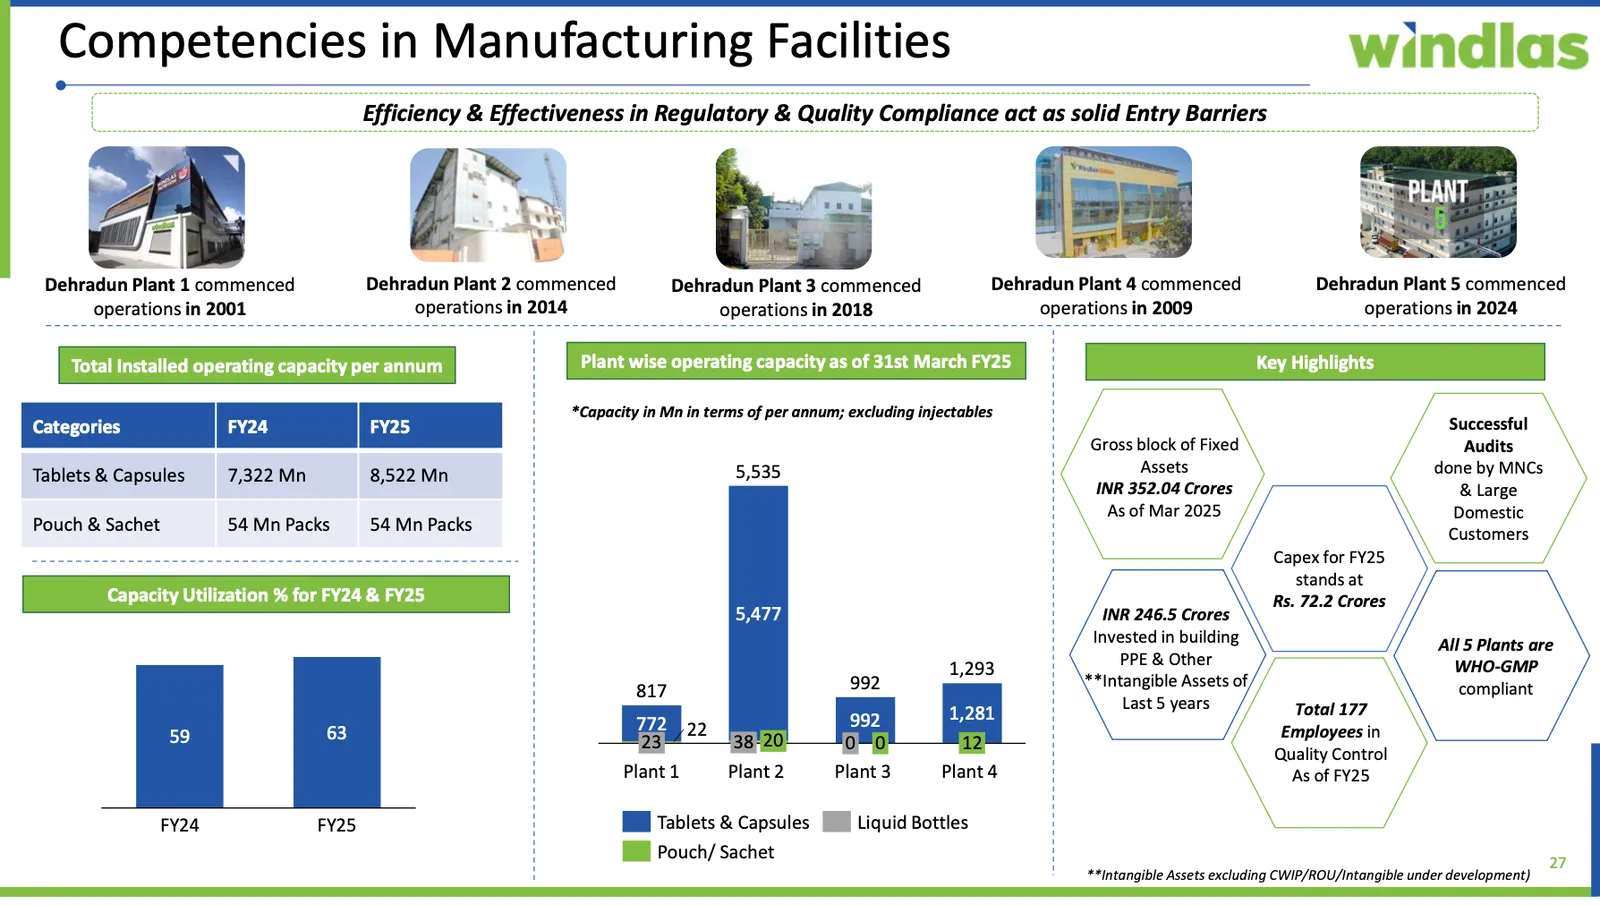
The management team comprises experienced professionals with significant industry expertise:
-
Hitesh Windlass: Managing Director, leading strategic initiatives.
-
Manoj Kumar Windlass: Joint Managing Director, overseeing operations.
-
Komal Gupta: CEO & CFO since 2015, driving financial strategy.
-
Vivek Dhariwal: Chairman & Independent Director, ensuring governance.
-
Other key members include Ashok Kumar Windlass (Whole Time Director), Pawan Kumar Sharma (Executive Director), and independent directors Gaurav Gulati and Srinivasan Venkataraman.
Business Model
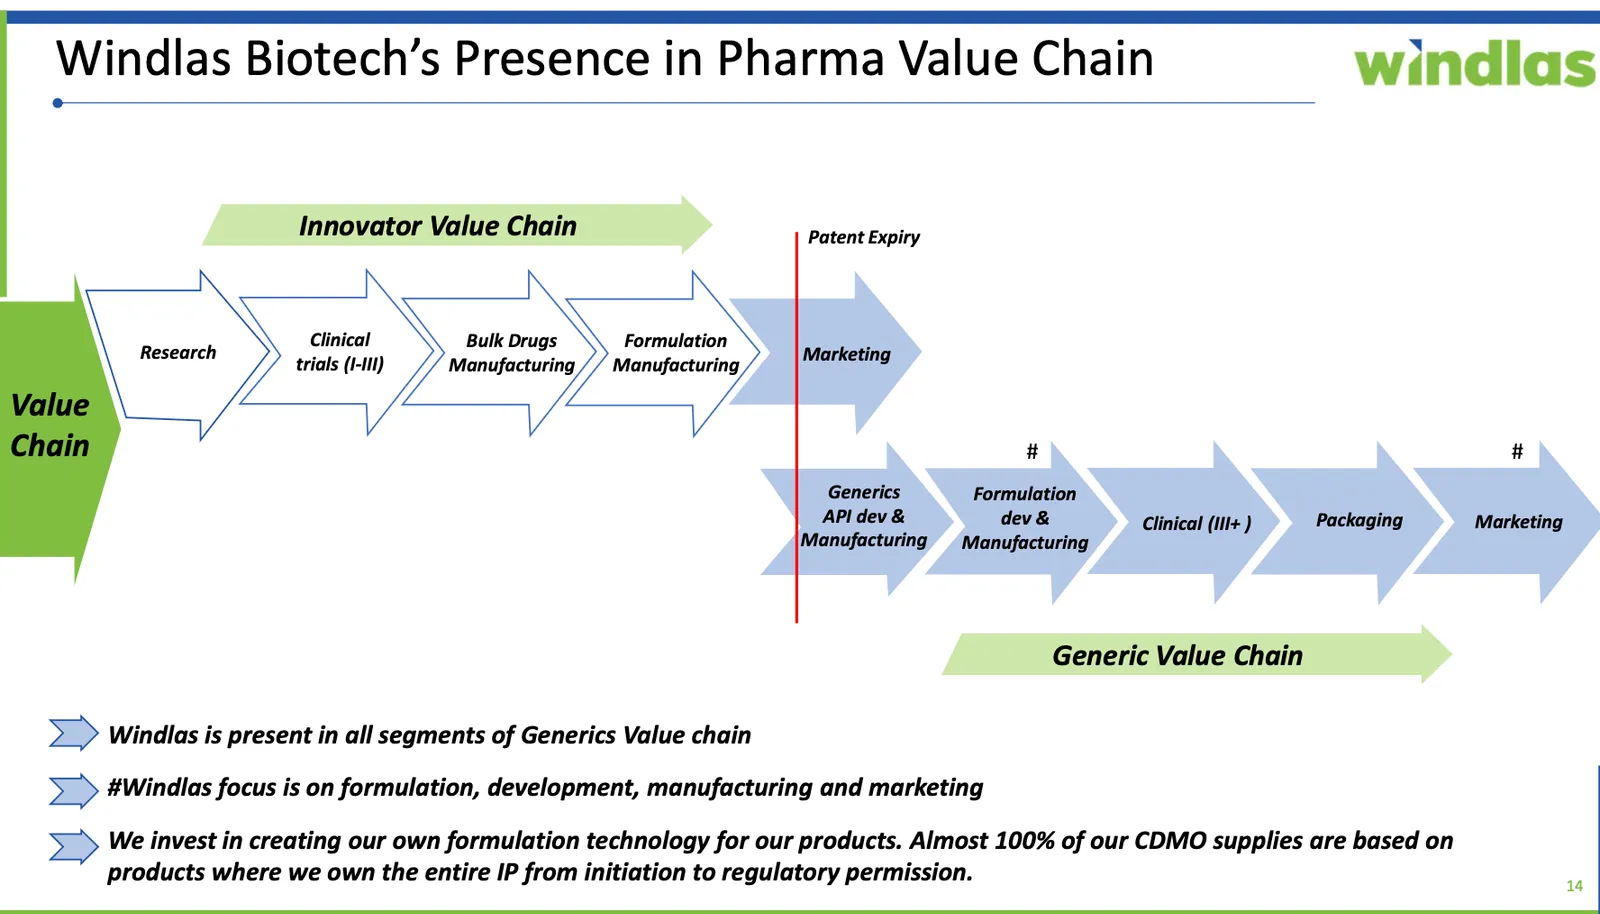
Windlas Biotech operates primarily as a domestic CDMO, offering services from product discovery to commercial manufacturing of generic products, including complex generics. It also markets its own branded products in trade generics and over-the-counter (OTC) markets and engages in exports.
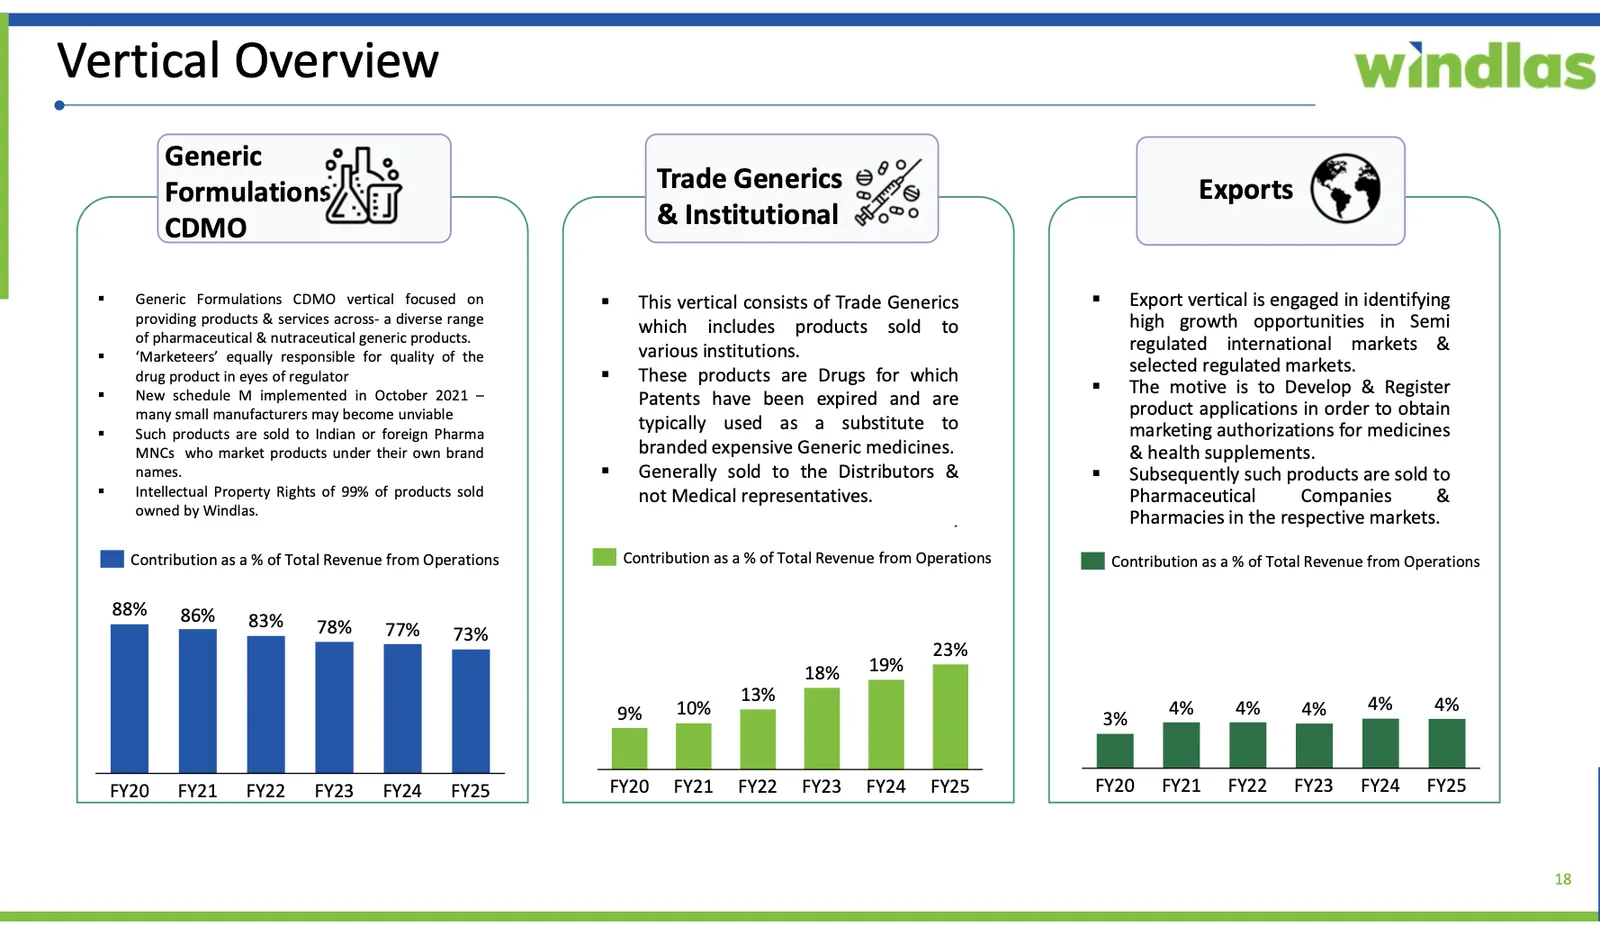
Revenue breakdown
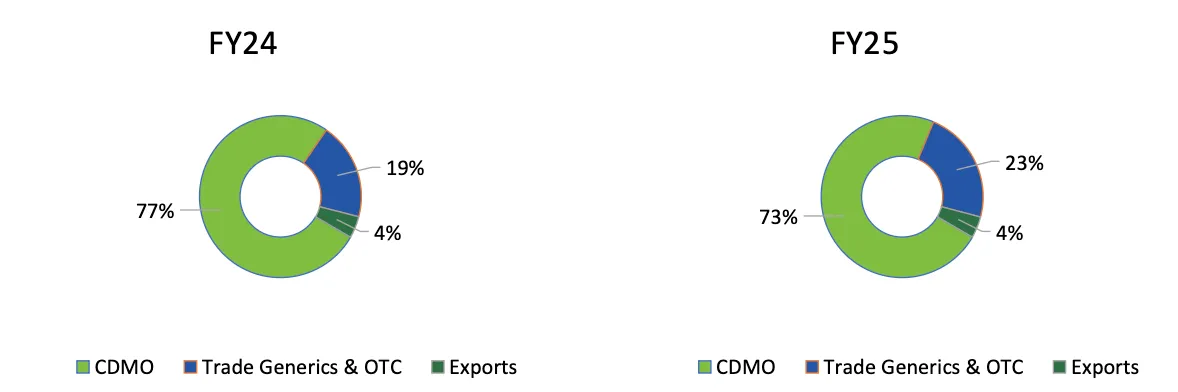
The company serves marquee clients like Pfizer, Sanofi, and Cadila, focusing on therapeutic categories such as anti-diabetic, cardiovascular, and respiratory therapies.
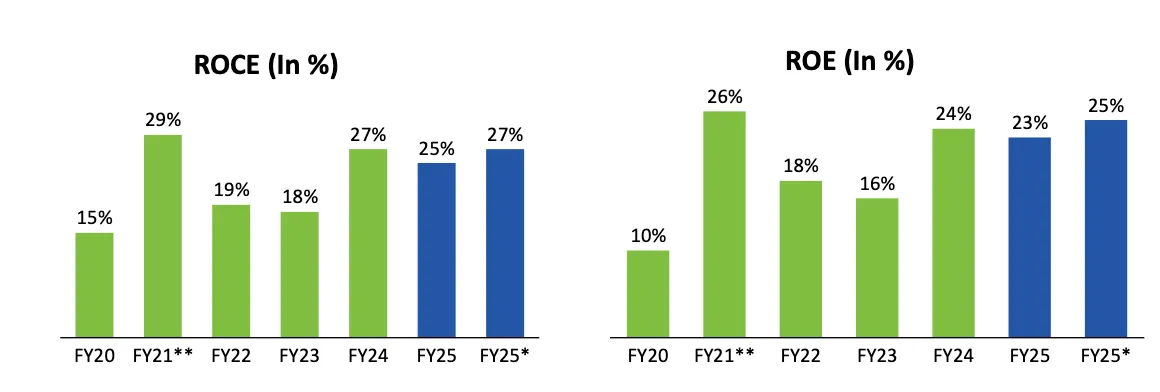
Windlas Biotech is consistently profitable with decent ROCE
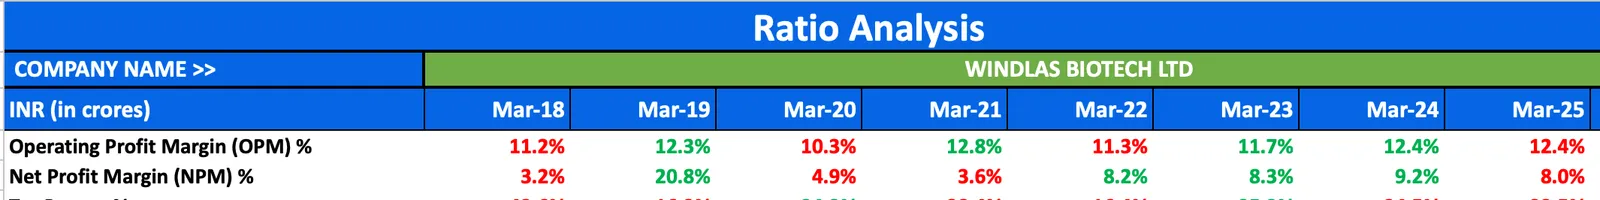
Windlas Biotech maintains stable margins:
Competitive Landscape and Regulation
The Indian domestic CDMO market is highly fragmented, with many small, unorganised players. However, the industry is expected to consolidate as larger CDMO companies with better infrastructure, technology, and regulatory compliance gain market share. This consolidation may be driven by factors like:
-
Cost optimization efforts by pharmaceutical companies
-
The need to provide a broader range of integrated services
-
Stringent regulatory norms like Schedule M, which encourage the adoption of Good Manufacturing Practices (GMP)
The increasing use of outsourcing by pharmaceutical companies, both in India and globally, is creating growth opportunities for CDMOs, including those focused on the domestic market.
Economic Moat
Windlas Biotech’s competitive advantages include:
-
Top-five position in India’s CDMO market.
-
Comprehensive service offerings from R&D to commercial manufacturing.
-
Focus on high-growth areas like complex generics and chronic therapies.
-
Extensive distribution network across 14 states.
-
Regulatory approvals for its manufacturing facilities, enhancing credibility.
Growth Plan and Sustainability
Windlas Biotech’s growth strategy includes:
-
Expanding manufacturing capacity, including a new injectables facility.
-
Investing in R&D for complex generics and chronic therapies.
-
Strategic acquisitions which have been committed but not executed
Management Analysis
-
No significant red flags regarding management integrity have been reported. The company maintains transparent financial reporting, as evidenced by regular disclosures on NSE and BSE.
-
The management team, with long tenures and industry expertise, has driven consistent growth and strategic expansions, such as the IPO and facility upgrades.
-
The leadership’s focus on R&D, capacity expansion, and complex generics reflects a growth-oriented mindset.
-
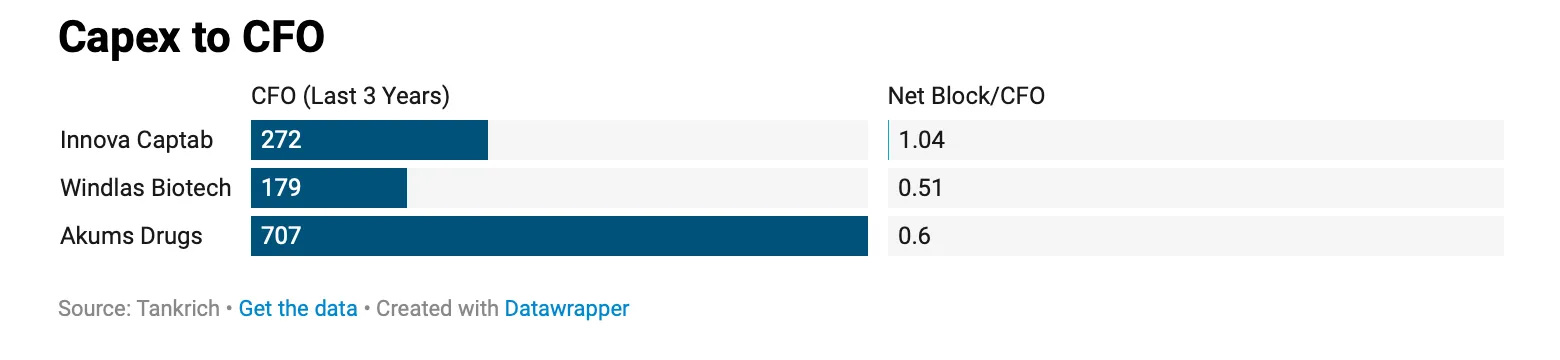
Windlas Biotech allocates capital rationally, balancing growth investments , unlike other peers which are rapidly expanding
-
The company has a robust structure with 954 employees across its facilities and a salesforce spanning 14 states, indicating operational depth.
-
Windlas Biotech emphasizes innovation, quality, and compliance, as seen in its digitalization initiatives and regulatory approvals (LinkedIn).
-
No significant share pledging by promoters has been reported, reducing financial risk.
Conclusion
Windlas is a contract manufacturer so is the key variable for us to track is operating leverage through capacity expansion
the company has expanded its asset base by 3 times in last 5 years revenue has not kept up!
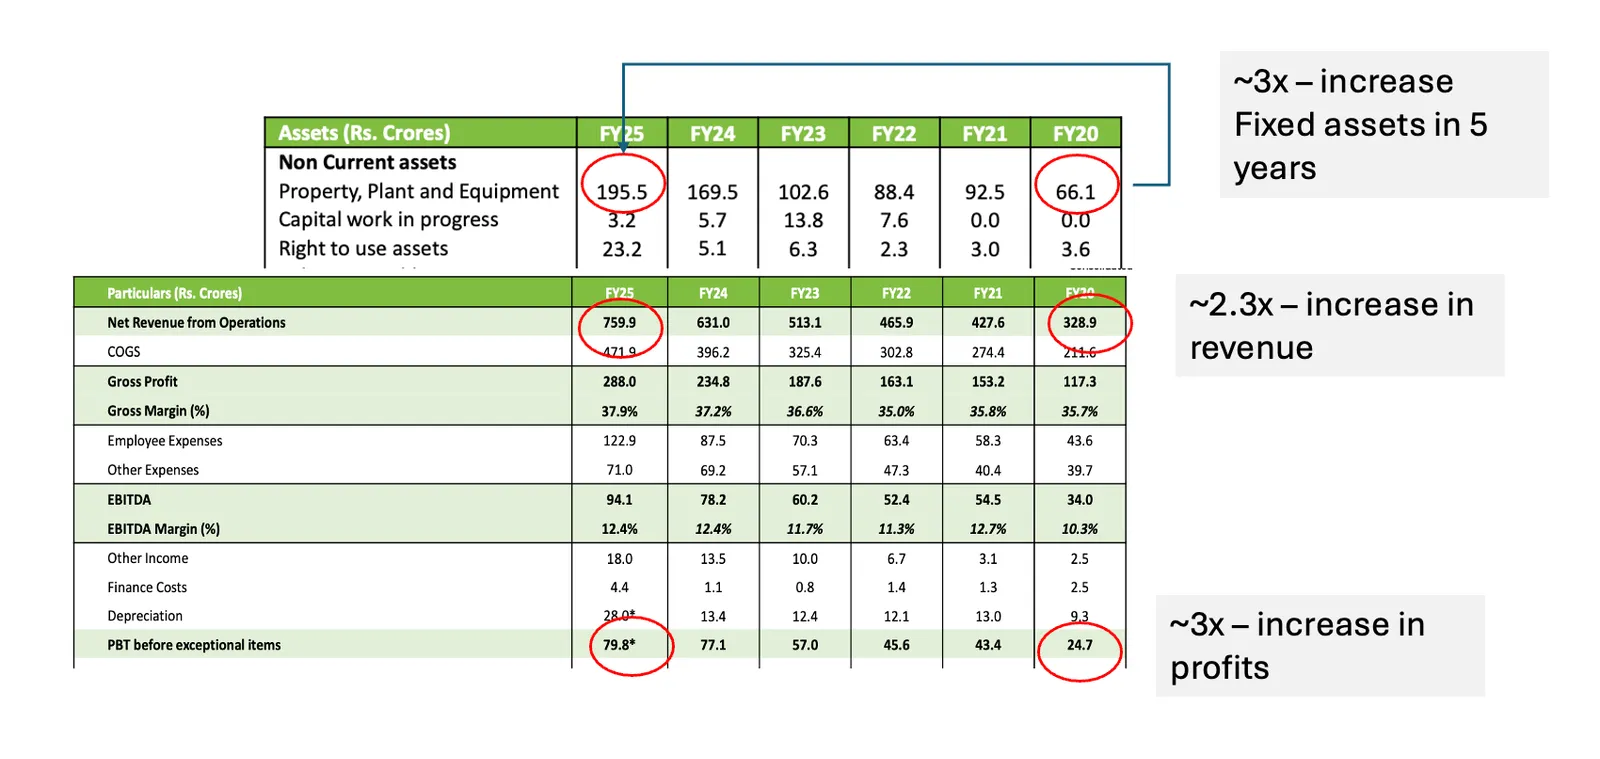
the bull thesis is company starts utilising its assets well and operating leverage plays out
in FY26 they are likely to ~900 crore sales and the current m-cap (May 2025) is 1900 crore so roughly 2x sales for a 20% grower is inexpensive
Related listen to this
Related: Windlas Biotech
Key Citations
This is a record of the author's thinking in June 2025, kept as written. It is not a recommendation to buy or sell, and the author may hold the securities discussed. See the disclosures.
Tankrich research on Windlas Biotech
2 posts from 2024 to 2025, oldest first.
- Windlas Biotech
- Windlas Biotech Ltd (this post)