Suven Life sciences - Demerger to create Value?
Written in July 2019. There is newer research on Suven Life Sciences: Novel Drug Discovery Company from India (August 2025).
Suven Life sciences is a company that I am tracking from 2014 This is what I wrote in 2014 on their optionality But as you would have seen expecting the company to not to commercialize any R&D work for 18 years would be a real surprise In 2015, I noted the possibility of monetizing their lead molecule in 2017 SUVN 502. For this molecule, we completed Phase-Ib trials and commenced preparations for the Phase-IIa (POC) trial. We hope to initiate patient trials during the second half of the current year and are hopeful of monetising this molecule post successful completion of the study in fiscal 2017 But few years with the company and I understood that Drug discovery is a long, hard and uncertain process and putting your odds is as good as throwing a dice. There are far few too many variables to model an outcome However we also observed that the company is building a different and more sustainable game plan For a company earning 12-15% ROE and growing at 10-15%, this seems to be fair or even above par, however, we need to be cognizant that Suven is building various verticals that are yet not contributing fully e.g. commercial supplies and technical services. And in 2018 we saw, for the first time that the new pillars of their growth have gained critical mass. I quote from post I am mightly impressed how this small company has built multiple pillars of growth, In space of 9 years they have built two revenue pillars while enhancing their core CRAMS offerings 2019 is another twist to this story, Suven has decided to demerge its CRAMS business from its Innovative NCE business, the management expects that demerger would help in
-
Profitability improvement for the base CRAMS unit as R&D expenses would be lower
-
Superior valuation for the high margin and high ROC CRAMS unit
-
Attract prospective investors for their high-risk business NCE business, I think especially large pharma companies may be interested to buy their matured pipeline
As part of this exercise, 300 crore cash would be retained in their NCE division (parent company) to allow them to continue R&D activity for the next 2-3 years. Another big event (or nonevent) would be clinical trial results for their lead molecule SUV-502. The results should have come by now (Jul 2019) however due to technical delays we need to wait for few more weeks. From the tone of the management, it seems that results may not be positive “Even as I am prepared mentally for an initial setback in our NCE journey, there remains a ray of hope for a positive outcome”
2019 Annual report
Additionally, Vishnu on twitter pointed to a very interesting podcast and summarised it very well
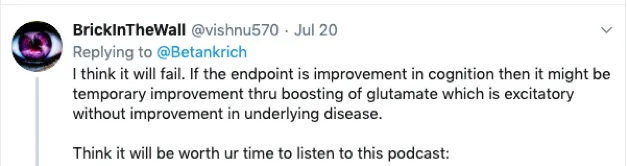
We need to wait for the official communication which should come in next 3-4 weeks The other major decision this year was they invested US$ 35 million (INR ~250 Crores) in Shore Suven Pharma, Inc., (now Rising Holdings, Inc.), a US-based company for a 25% stake in the Company. The management expects to benefit by
-
Turning around the operations of the company
-
Backward integration into India through Suven both in development and supply i.e. would increase Suven’s base CRAMS business 2-3 years down the line
-
Suven, being an earlier partner, will have the option to develop new products and supply on a profit-sharing basis
In 2019, The base business kept chugging along well in spite of steep fall in commercial supplies
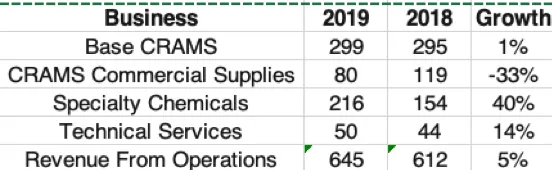
All figures in INR crore Management indicated their inability to secure raw materials from China as one of the main reasons for shortfall in CRAMS commercial supplies. For next year they expect overall topline growth of 10-15% in CRAMS space so overall Topline would be about INR ~700 crores in FY20 The new CAPEX would be for formulation development center in Vizag, a total outlay of INR ~200 crores since the majority of the reserves would be used for NCE business division this will be part-funded by debt How will the two companies look next year?
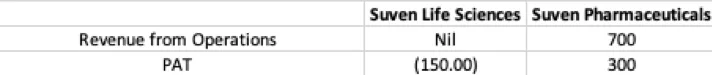
All figures in INR crore What does Mr. Venkat Jasti have to say about Suven Pharmaceutical?
I don’t need any cash to run the business, I am accruing money as you know quarter on quarter. Only thing I need is internally if we are expanding then we have to CAPEX for which we can go to the banks to get the debt.
From Earnings Transcript
By this demerger
-
Suven Pharmaceutical’s reported earnings would improve
-
High-profit margin CRAMS business would be carved out with optionality of improvement in Rising pharma Inc operations
-
Suven Life sciences can become a takeover target or partner through dilution for big pharma who is interested in IP of matured molecules
Current M-cap of INR ~3000 Crores ascribes Zero valuation to NCE business and gives a forward FY20 PE of 10X to Suven pharmaceuticals which in my view is a bargain
This is a record of the author's thinking in July 2019, kept as written. It is not a recommendation to buy or sell, and the author may hold the securities discussed. See the disclosures.
Tankrich research on Suven Life Sciences
8 posts from 2014 to 2025, oldest first.
- Suven Life Sciences - The Embedded Triggers
- Suven Life - Embedded Triggers Triggered
- Forecasting and Reality - Review of Suven Life sciences
- Suven Life Sciences - Building multiple pillars of growth
- Suven Life sciences - Demerger to create Value? (this post)
- Suven creates value through demerger
- Suven - A New Beginning
- Novel Drug Discovery Company from India