Suven Life Sciences - Building multiple pillars of growth
Written in September 2018. There is newer research on Suven Life Sciences: Novel Drug Discovery Company from India (August 2025).
I have written about Suven multiple times, you can read previous updates here to get familiar with the company
2014 - Introduction to company
2015 - Identifying multiple triggers embedded in company and way to value it
2017 - An annual update on the thesis last year
I am mightly impressed how this small company has built multiple pillars of growth, In space of 9 years they have built two revenue pillars while enhancing their core CRAMS offerings
All figures in INR cr except % 2010-11 2015-2016 2016-2017 2017-18 Base CRAMS [Balancing Figure] 87 244 253 324 CRAMS Commercial Supplies 0 0 34 119 Specialty Chemicals 40 224 224 154 Technical Services 24 32 33 27 Revenue From Operations 151 500 544 625 Other Income 1 19 21 23 Total Revenues 303 519 565 648 Consolidated Net Profit 10 71 87 124 Margin 3.43% 13.70% 15.40% 19.14% Research & Development Exp 31 90 99 90 Sales to R&D 10.22% 17.34% 17.52% 13.89%
For the year 2018
Base CRAMS
Projects Spilt
Phase
2013-14
2014-15
2015-16
2016-17
2017-18
Phase 1
52
57
64
70
72
Phase 2
46
52
48
41
36
Phase 3
3
1
1
2
1
Commericial
3
4
Total
101
110
113
113
113
There was an increase in the upward movement of CRAMS projects from Phase I to Phase II, which made the project increasingly profitable.As a result, even as the revenue from this segment increased, profits accelerated at a faster clip. More importantly, revenue share which is repetitive in nature (from existing global pharmaceutical innovators) has increased significantly over the last five years – a critical lead indicator from this segment
Commercial Supplies
They have successfully developed this business over last 5 years which has started yielding results. Every molecule which moves to commericial pipeline for innovator adds a annuity type of revenue for Suven
This is what we wrote in 2015
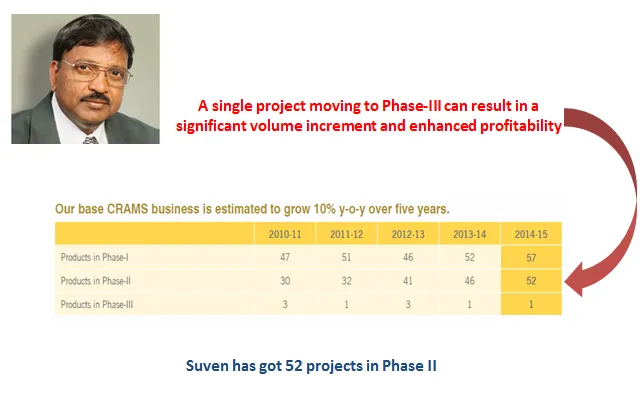
The most interesting thing to note in this year’s report was this positive statement from management
There is a pipeline of approved molecules (by the US regulators) for which we have supplied intermediates, which are yet to be launched in the world’s largest pharmaceutical market, Revenue from this vertical jumped by 251% over the previous year. And this is just the beginning. For we are among the select 2-3 suppliers globally for these intermediates product used in the approved molecules all through their patent validity
Specialty Chemical Supplies
There was a price erosion on customer side and management expects to continue at current run rate of ~150 crores for next year
Technical Services
This is smaller division and company is planning to file more ANDAs to ramp up revenue from this segment from FY20 onwards
Overall company has industriously built two pillars of revenue which were not existent 5 years back. Mr Jasti nicely explains there flywheel
Suven is not just a manufacturing company but a Contract Research Company and the results of research leads to manufacturing activity and then supplies to our customers.
The company continues to spend significantly on R&D to develop new molecules and finances them through internal cash flows
R&D expenses (consolidated basis) decreased from INR 99.14 crore in 2016-17 to INR 90.21 crore in 2017-18, however, they will increase to about INR 120 crores as Suv-502 completes its final leg of phase III trial next year.
The capital employed in business increased from INR 761.63 crore as on March 31, 2017 to INR 896.06 crore on March 31, 2018 owing to the Company’s expanding horizons and increasing scale.The cash and bank balance stood healthy at INR 293 crore as on March 31, 2018 . The company will be spending INR 150 crores over next 18 months on Capex on formulation manufacturing
Suven sweats its assets well (Below numbers are in INR crores)
2017-18
2014-15
Increase
Plant, Property, Equipment
305
171
Capita work in Progress
24
107
Total
329
278
51
Revenues
625
521
104
The current capex plan will double the fixed assets and easily add 300 crore to top line in next 3-4 years
NCE segment (Innovation business)
This is an Indian small pharmaceutical pursuing an extremely risky but lucrative drug discovery business, key updates on main molecules
SUVN-502
500 patients have been enrolled
Final results by Q2 FY20
Drug Safety Monitoring Board (DSMB) met during this last month and they have gone through the adverse event occurrence and they found not even a single serious adverse event related to the drug
10% of patients enrolled for Early Access Program - Another positive sign
SUVN-G3031 for excessive day time sleep disorder will get into Phase II trials next year
On succession planning
Both daughters are actively involved in the company’s operations and are learning about business.
The company sells for a market cap of INR ~3200 (ex-cash) crore as of Sep 2018, 26 times trailing earnings.
This is a record of the author's thinking in September 2018, kept as written. It is not a recommendation to buy or sell, and the author may hold the securities discussed. See the disclosures.
Tankrich research on Suven Life Sciences
8 posts from 2014 to 2025, oldest first.
- Suven Life Sciences - The Embedded Triggers
- Suven Life - Embedded Triggers Triggered
- Forecasting and Reality - Review of Suven Life sciences
- Suven Life Sciences - Building multiple pillars of growth (this post)
- Suven Life sciences - Demerger to create Value?
- Suven creates value through demerger
- Suven - A New Beginning
- Novel Drug Discovery Company from India