Sansera Engineering Ltd
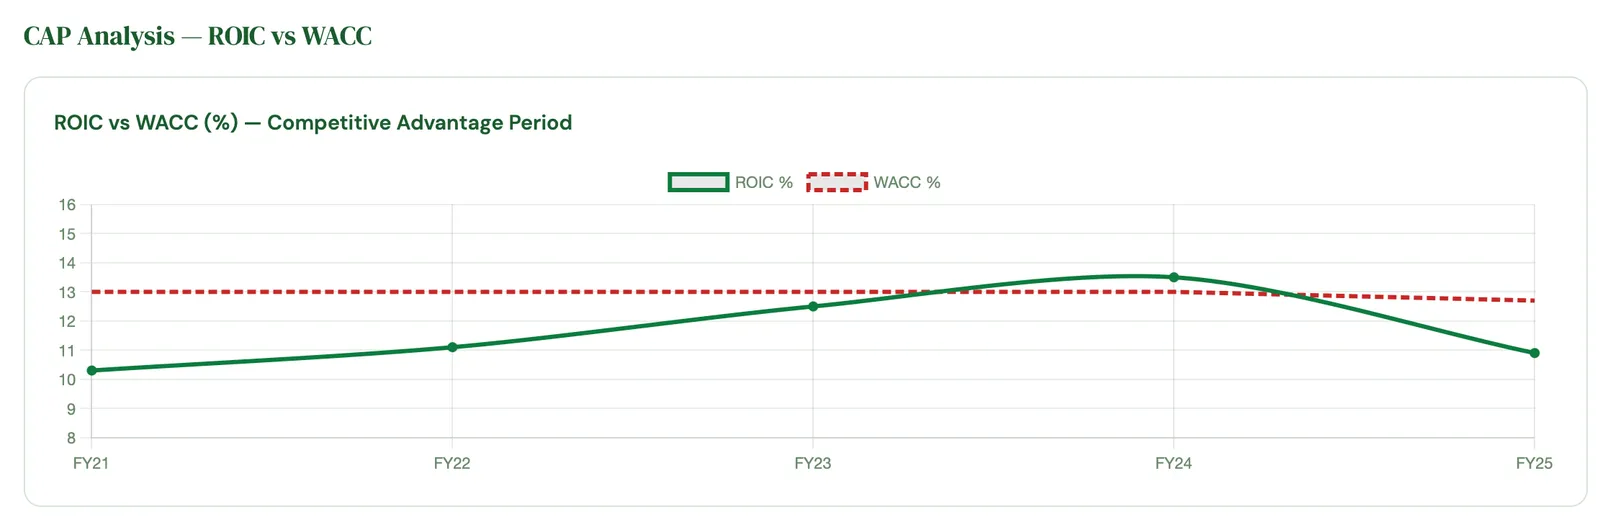
Sansera is undergoing a structural transformation from a predominantly ICE auto-component supplier into a diversified precision engineering platform.
A paid subscriber requested our AI analyst report, I found the transition interesting so sharing with all paid subscribers
every paid subscriber can request 1 report every quarter , become an
The ADS segment is Sansera’s strategic frontier. It serves Boeing, Airbus, ISRO, and a leading global wafer-fabrication equipment manufacturer. The company has received an initial order of USD 17 million from the semiconductor customer, with a ramp target of USD 30 million within three years, and has committed ₹1.2 billion in aerospace machining infrastructure with a second hangar (₹600 crore peak revenue capacity) planned for H2 FY27. The company’s JV with Nichidai (Japan) for broaching tools and its MMRFIC defence-tech investment (₹20 crore revenue, 40% EBITDA margin) further evidence the strategic pivot.
Revenue mix transformation is underway: ICE Auto has declined from 83.4% (FY21) to 71% (9MFY26), while Tech-Agnostic & xEV is at 14% (up from 5% in FY21) and Non-Auto (ADS) is at 15% (up from 12%). The management’s long-term aspiration is to bring non-ICE revenue to 40% — a goal that is structurally achievable but requires sustained order wins and execution over the next 3–4 years.
read the full report here
ensure you understand all risk by going through all tabs
Disclaimer
This report is for educational and informational purposes only. It does not constitute investment advice, a recommendation, or a solicitation to buy or sell any security. The analysis represents the author’s personal views based on publicly available information believed to be reliable, but no representation is made as to its accuracy or completeness.
Any fair value ranges, scenarios, or estimates shown are analytical model outputs based on assumptions that may not materialise — they are not price targets or guarantees of future performance. Markets price securities; this report is intended only to inform the reader’s own independent assessment.
Securities investments are subject to market risks, including the possible loss of principal. Past performance is not indicative of future results. Readers should conduct their own due diligence and consult a SEBI-registered investment adviser before making any investment decision.
The author may hold positions in the securities discussed. This report is not produced under any SEBI Research Analyst registration unless explicitly stated.
This is a record of the author's thinking in June 2026, kept as written. It is not a recommendation to buy or sell, and the author may hold the securities discussed. See the disclosures.