JM Financial
Written in October 2024. There is newer research on JM Financial: JM Fin - Blue Sky (July 2025).
First, Get a gem daily on WhatsApp
We wrote about finding ideas using long consolidation model here, one of ideas that popped up in my weekend screening few weeks back was JM Financial (NSE: JMFINANCIL)
The stock qualified long consolidation with no returns for 3+ years
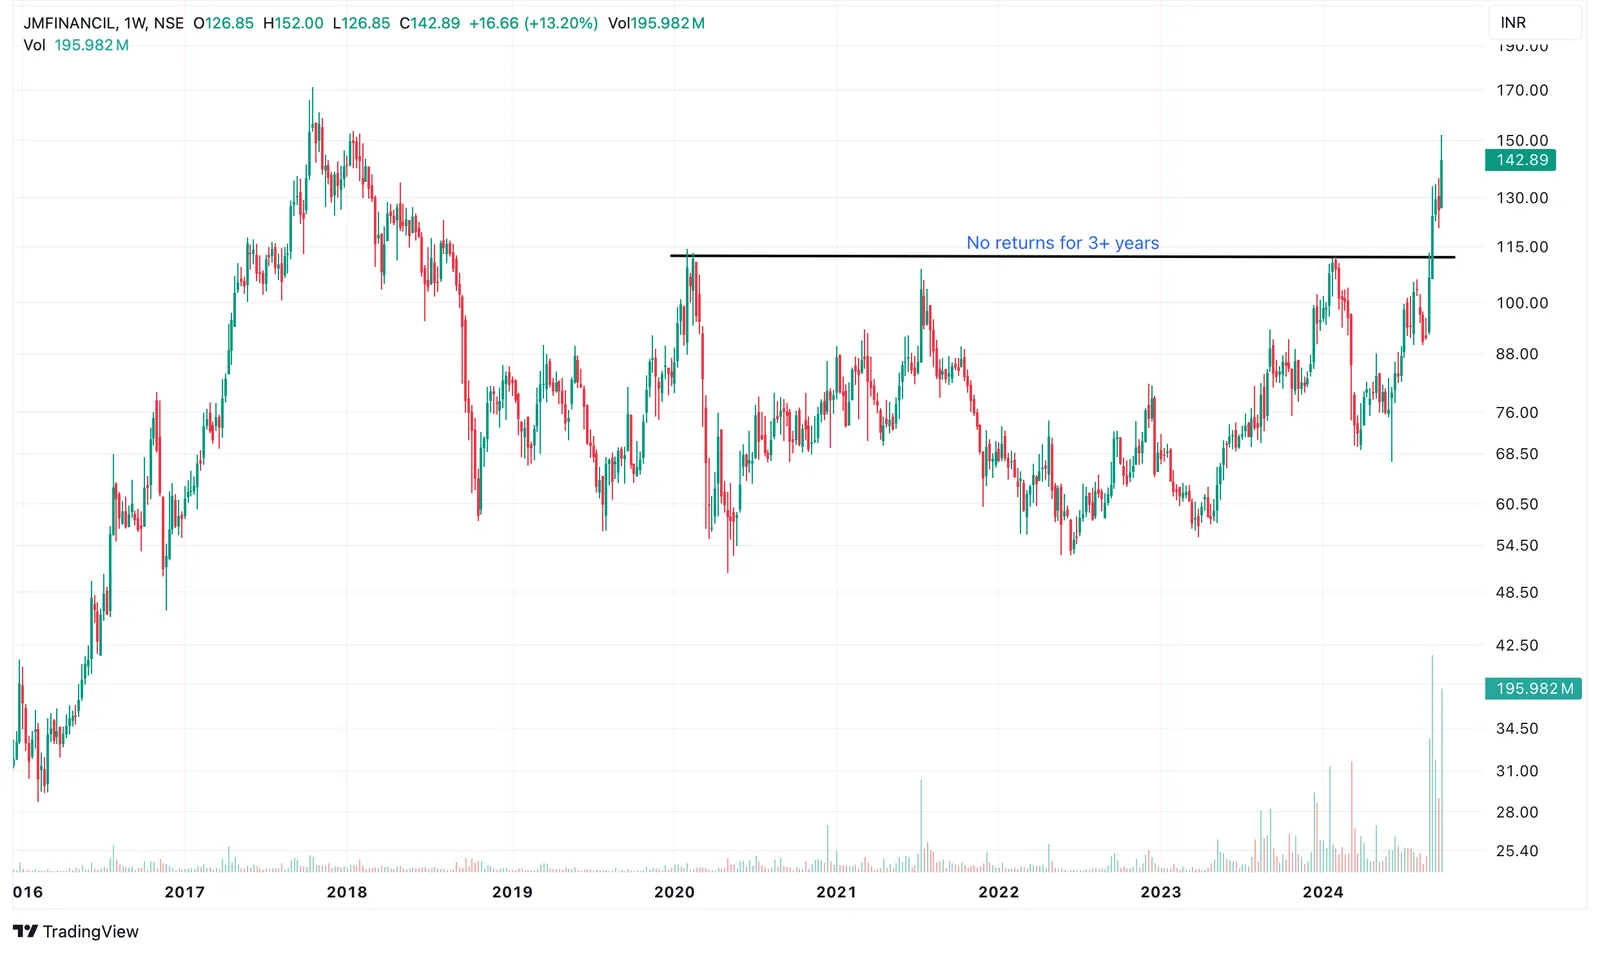
Normally when stock is range bound earnings are stagnant or declining , which is the case for this company, if the sales are also declining than usually I strike it off and dont do any more work on the idea,
but for JM Fin revenues have increased, this kept my interest going :)
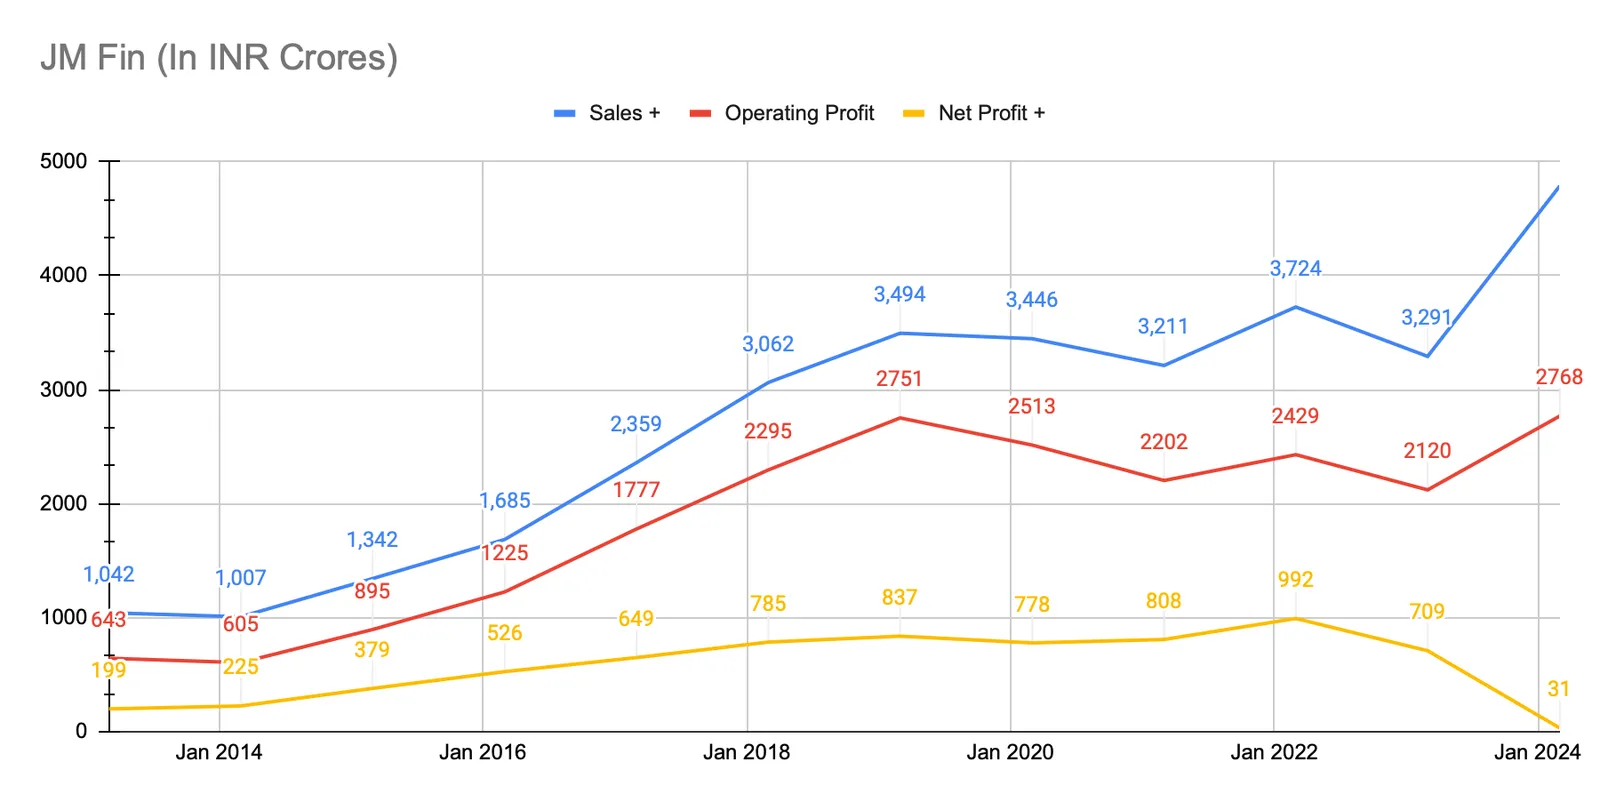
So next logical check why have revenues increased but profits remained flat/ decreased over years?
The answer lies when you check their business segment results, they clearly show what has been the problem
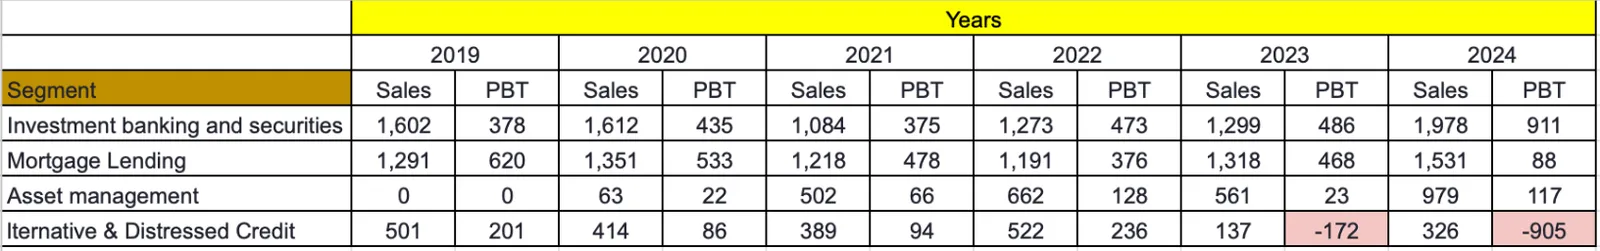
Mortgage lending and Distressed credit division have impacted overall profitability of the group considerably
Is anything going to change?
Unless there is a catalyst, there is not going to be any difference and the long consolidation in price will continue
However there is a strong catalyst at play here - the catalyst is
management action to reverse capital misallocation
-
In FY 2023-24, JM Financial acknowledged the increasing competitive pressures in the wholesale credit market and the impact of regulatory changes on their traditional lending business
-
Pivoting from On-Balance Sheet Lending This led to a strategic decision to shift from on-balance sheet lending towards a syndication and distribution-led model
Wholesale Credit: Instead of holding loans on their books, they aimed to syndicate these transactions to other investors, generating fee-based income and reducing their risk exposure.
Distressed Credit: Similarly, their approach to distressed credit evolved to include more co-investment opportunities and a focus on full-cash acquisitions to mitigate risk and create a balanced revenue model
- Scaling Fee and Commission Generating Businesses: They emphasised expanding their Investment Banking, Institutional Equities, Wealth Management, and Asset Management businesses, all of which generate fees and commissions with lower leverage requirements
The organisation would focus on their four core business segments
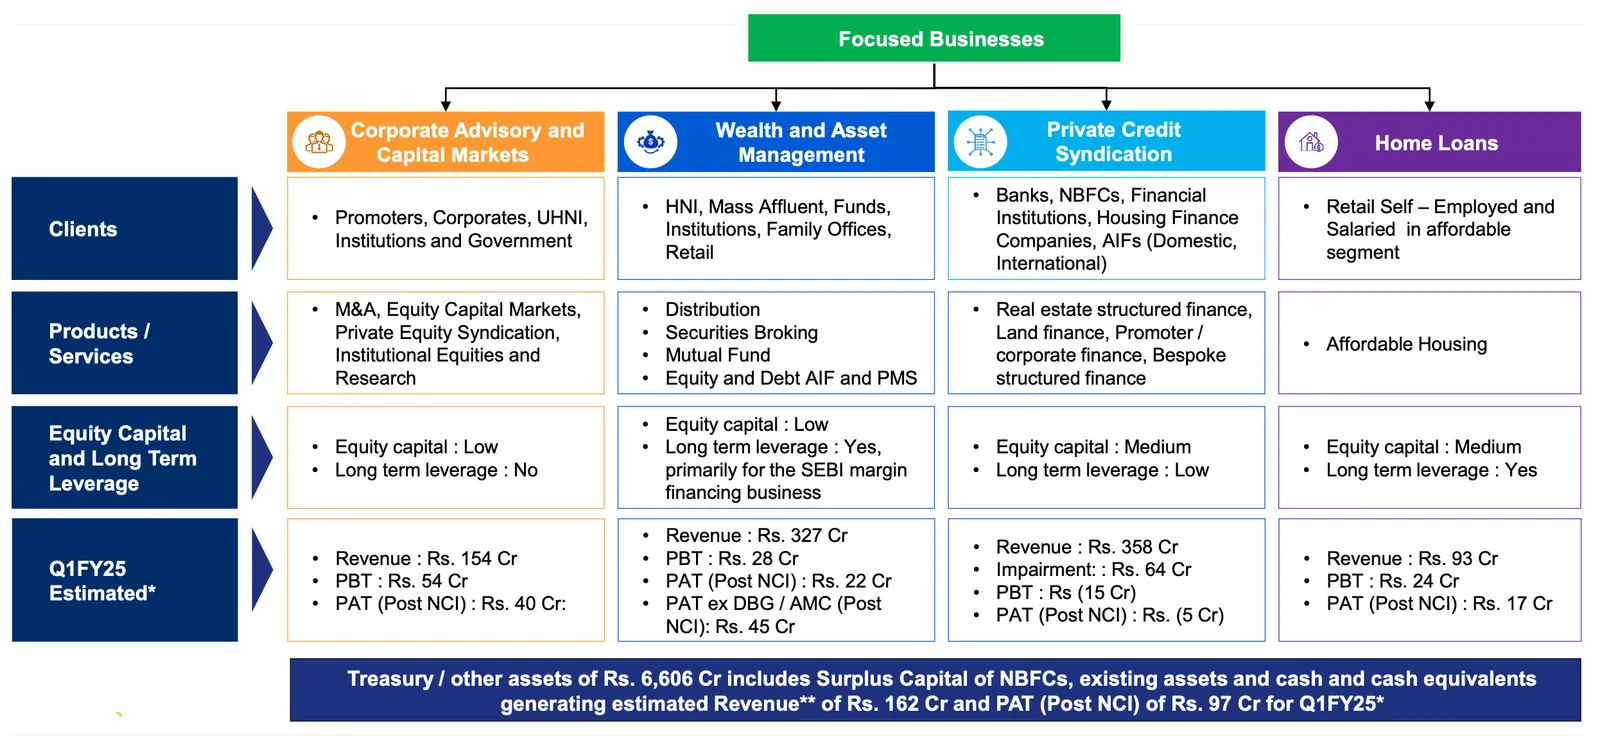
The company is trying to reverse its capital misallocation , JM Financial anticipates a substantial amount of cash returning to the company as a result of its strategic shift away from on-balance sheet lending and towards fee-based income models. Here’s a breakdown of the key sources and estimations of cash inflow:
-
Rundown of Loan Book: JM Financial plans to gradually reduce its wholesale lending book in both JM Financial Products and JM Financial Credit Solutions. As these loans mature and are repaid, the cash will flow back to the company. While the concalls don’t specify the exact amount expected from the full rundown, they do provide some figures
-
JM Financial Products: The projected cash and cash equivalents increase from INR 639 Crore to INR 2,500 Crore in 2 years, suggesting a cash inflow of approximately INR 1,861 Crore from loan repayments within this period.
-
JM Financial Credit Solutions: Similarly, JM Financial Credit Solutions projects cash and cash equivalents to increase from INR 1,800 Crore to INR 4,200 Crore, indicating an inflow of INR 2,400 Crore in 2 years.
-
Overall Rundown: The presentation highlight that the rundown of the loan book in these two entities is expected to generate around INR 6,500 Crore by June 2026.
-
-
Incremental Cash Release: In addition to the loan book rundown, JM Financial projects an incremental cash release of approximately INR 2,000 Crore over the next 3-4 years. This cash release is attributed to the transition from on-balance sheet lending to a distribution and alternative structure.
-
Resolution of Non-Performing Assets (NPAs): While not explicitly included in their cash flow projections, JM Financial expects additional cash inflow from the resolution of NPAs.
- Potential Recovery: They estimate a potential recovery of INR 600-700 Crore on a gross NPA basis, with a more conservative estimate of at least INR 200-250 Crore in JM Financial Credit Solutions if they recover only the unprovided amounts.
-
Sale of Stake in JM Financial Credit Solutions: In July 2024, JM Financial approved the acquisition of a 42.99% stake in JM Financial Credit Solutions from International Housing Finance Co. Ltd. for INR 1,281.95 Crore. While this is an outflow in the short term, it positions the company for greater control and potential future monetization of this subsidiary, which could lead to further cash inflows.
Total Estimated Cash Inflow:
Based on these , a conservative estimate suggests that JM Financial could see a total cash inflow exceeding INR 6,000 to 8,700 Crore over the next 2-4 years.
Important Notes:
-
These figures are based on projections and estimations provided within the con calls, which are subject to market conditions, regulatory changes, and the success of their strategic initiatives.
-
The actual cash inflow might vary from these estimations.
How JM Financial Plans to Utilize the Returning Cash:
The management indicate that JM Financial intends to allocate the returning cash towards several strategic priorities:
-
Distributions to Shareholders: The company plans to increase payouts to shareholders through dividends and potential buybacks as the surplus capital becomes available.
-
Investments in AIFs: A portion of the cash will be directed towards their own alternative investment funds (AIFs), leveraging their expertise in credit and seeking higher returns.
-
Growth Investments: JM Financial will continue investing in their fee-based businesses, including Investment Banking, Asset Management, Wealth Management, and digital initiatives, to drive future growth and profitability.
With company expected to throw this amount of cash at its current market cap of INR 13000 crore , I am invested and tracking this in my portfolio.
We just need to be wary of that they dont go overboard and start pumping most of the cash in Growth Investments
We will be tracking their execution
Happy Investing
This is a record of the author's thinking in October 2024, kept as written. It is not a recommendation to buy or sell, and the author may hold the securities discussed. See the disclosures.
Tankrich research on JM Financial
2 posts from 2024 to 2025, oldest first.
- JM Financial (this post)
- JM Fin - Blue Sky