GRUH Finance - Mr Consistent
Virat Kohli picture is not a coincidence he is *“*Mr Consistent” run-scoring machine for Indian cricket team just like GRUH finance the money making top-notch HFC.
I have done the comparative analysis of Housing Finance Companies (GRUH/REPCO/CANFIN) in past, you can read them here and here
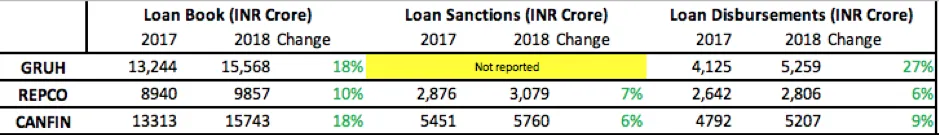
In 2018 (At Q4 Mar 2018) GRUH Finance and Canfin grew their loan book by 18% and REPCO’s loan book grew by 10% with GRUH having healthy growth in disbursements. The yearly growth had slowed down (from last year levels) for both Canfin home and REPCO while GRUH maintained its consistency
Both GRUH and Canfin homes had better bottom line growth as well
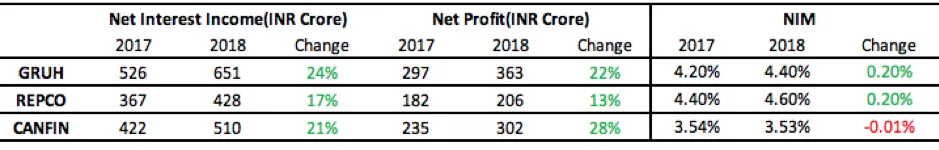
This was driven due to
-
Cheaper costs of funds
-
Significant improvements in cost to income ratio, branch employee productivity gains
-
Improving and retaining net interest margin
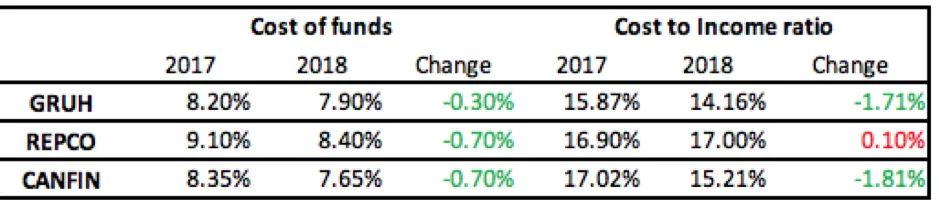
GRUH is setting benchmarks on running tight operations its Cost to Income ratio is best in Industry and has improved 4-5 percentage points in the last 5-6 years.
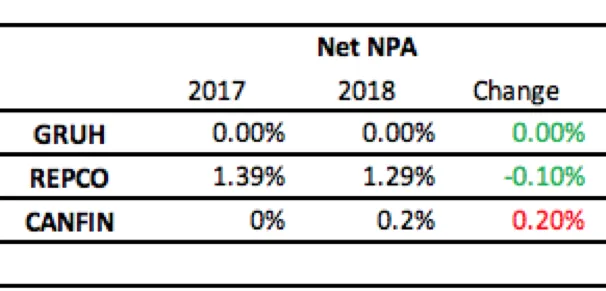
GRUH also had the best asset quality out of three with Net NPAs of Zero, The numbers for Canfin homes and REPCO were not alarming, given in REPCO’s case management clarified
The ebb and flow of asset quality showed an aberration in FY17 owing to a Tamil Nadu State specific factor (interpretation of Madras High Court order pertaining to registration of unapproved plots) and the macroeconomic impact of the landscape altering demonetization drive ~ REPCO Annual report
It also maintained the best return ratios out of three, however, Canfin homes have improved ROA in the last 5 years and is fast catching up aided by improvements in cost to income ratio and broadening branch base outside Karnataka
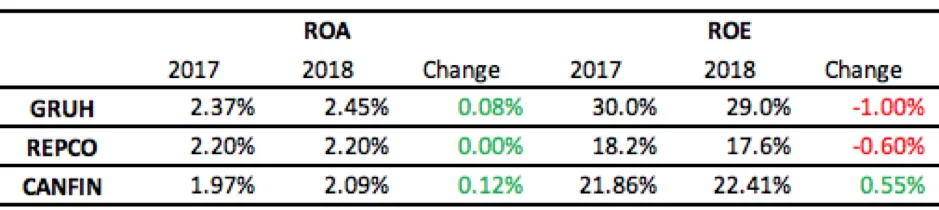
However Mr. Market has is valuing these businesses very differently, Yes GRUH is priced almost 5-6 times of its peers
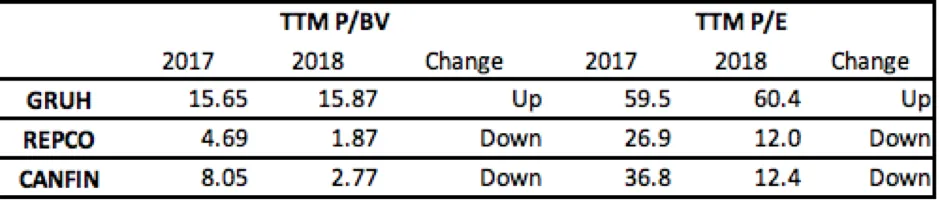
In my mind, the premium is due to
-
Consistency - Even Q1, Q2 FY19 results from GRUH were good with 20% growth
-
REPCO’s over-reliance on one state and inability to improve cost to income ratio
-
Canara’s bank unsuccessful attempt to sell of Canfin homes
-
The HDFC pedigree of GRUH
Whether the premium is justified?
I think is the market is bit pessimistic with Canfin homes. For the real estate market, there is hope of the demand as well as the supply improving going forward which should benefit the stronger and efficient players and Canfin homes having exposure largely to salaried workforce should do well.
This is a record of the author's thinking in November 2018, kept as written. It is not a recommendation to buy or sell, and the author may hold the securities discussed. See the disclosures.
Tankrich research on GRUH Finance
2 posts from 2015 to 2018, oldest first.
- Annual Review - GRUH Finance
- GRUH Finance - Mr Consistent (this post)