Twitter Tips
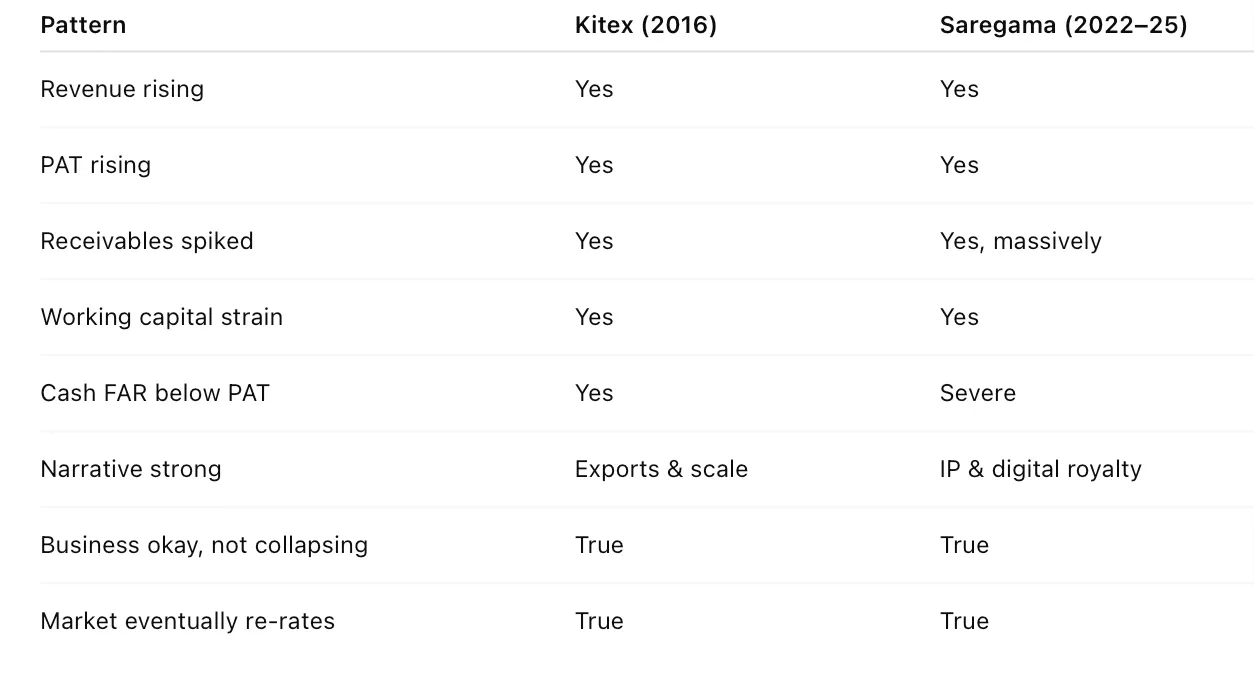
In 2016, Kitex Garments delivered a brilliant annual report on paper profits up, margins stable, and the narrative compelling. But when we looked deeper, the signals were clear:
receivables rising, cash not keeping up, working capital quietly absorbing value.
In 2025, the closest modern equivalent is Saregama India Ltd.
Another hot twitter stock
A celebrated “IP compounding” story that experienced the same silent shift beneath the surface one that every investor should learn from
You need to be very careful when a stock becomes too hot on twitter , the blue arrows are when we got tweets from well followed accounts
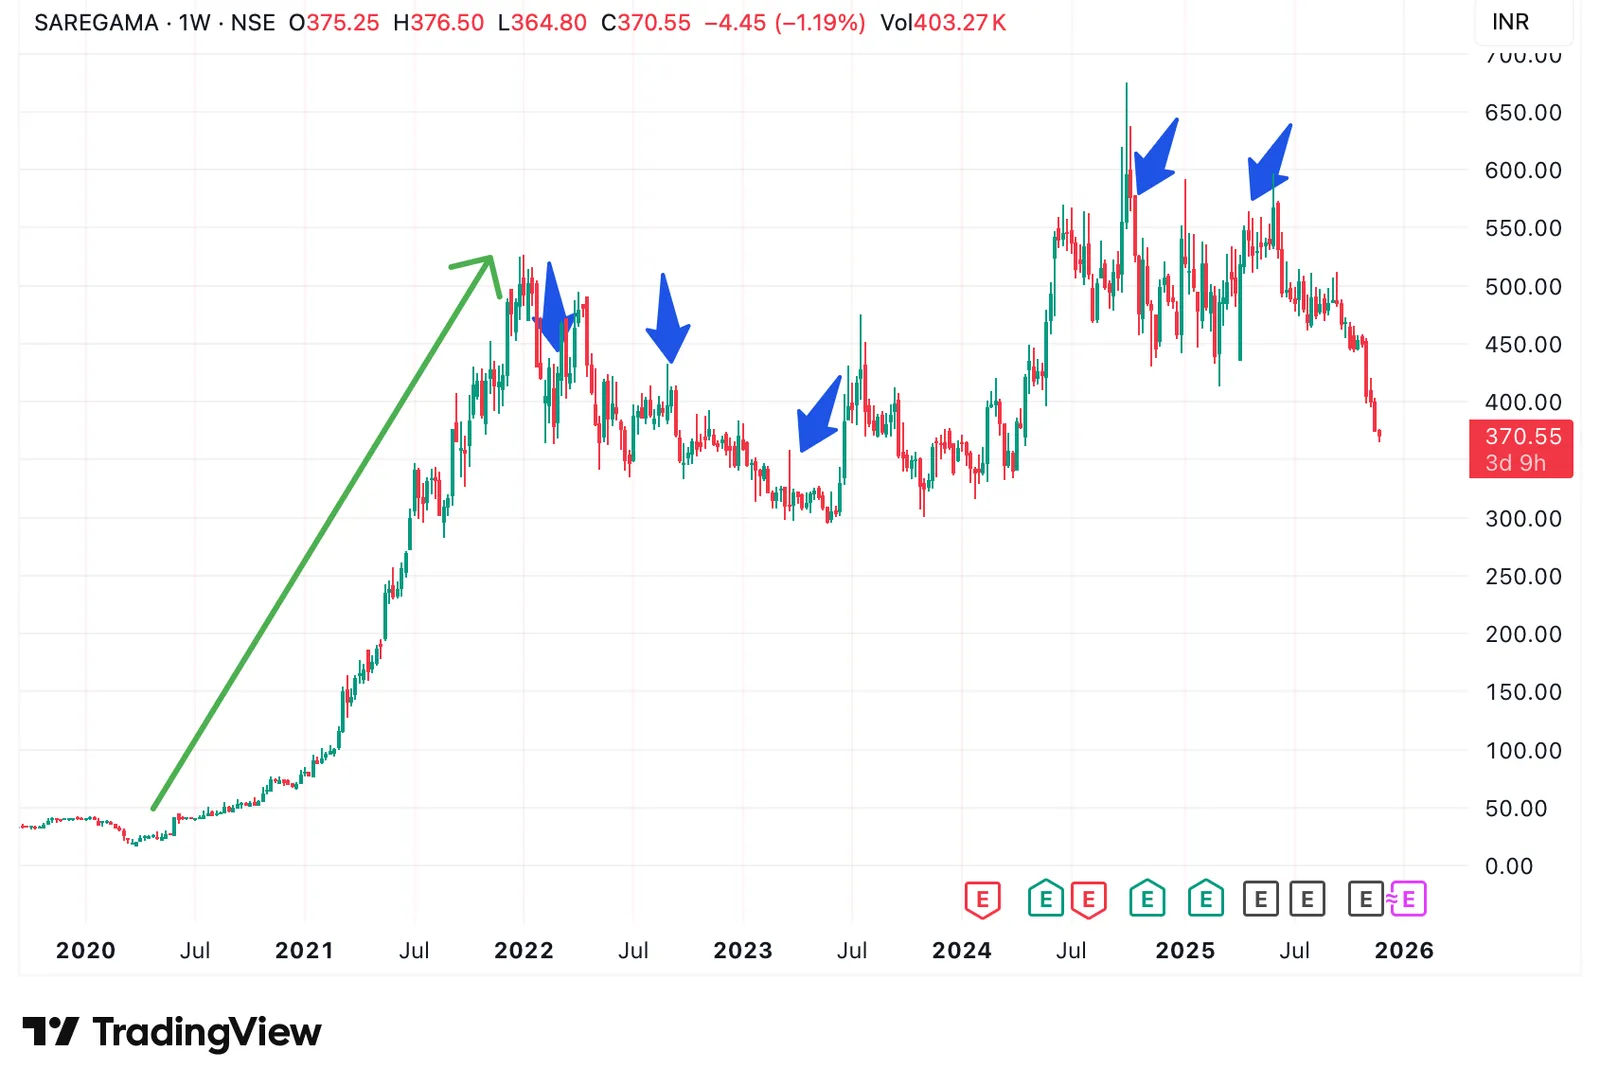
I am not critical of the any individual accounts but you will find this hot trend every time a stocks does 10X in short time like Saregama did between 2019 and 2021
Give most of top bold top picks on twitter a miss
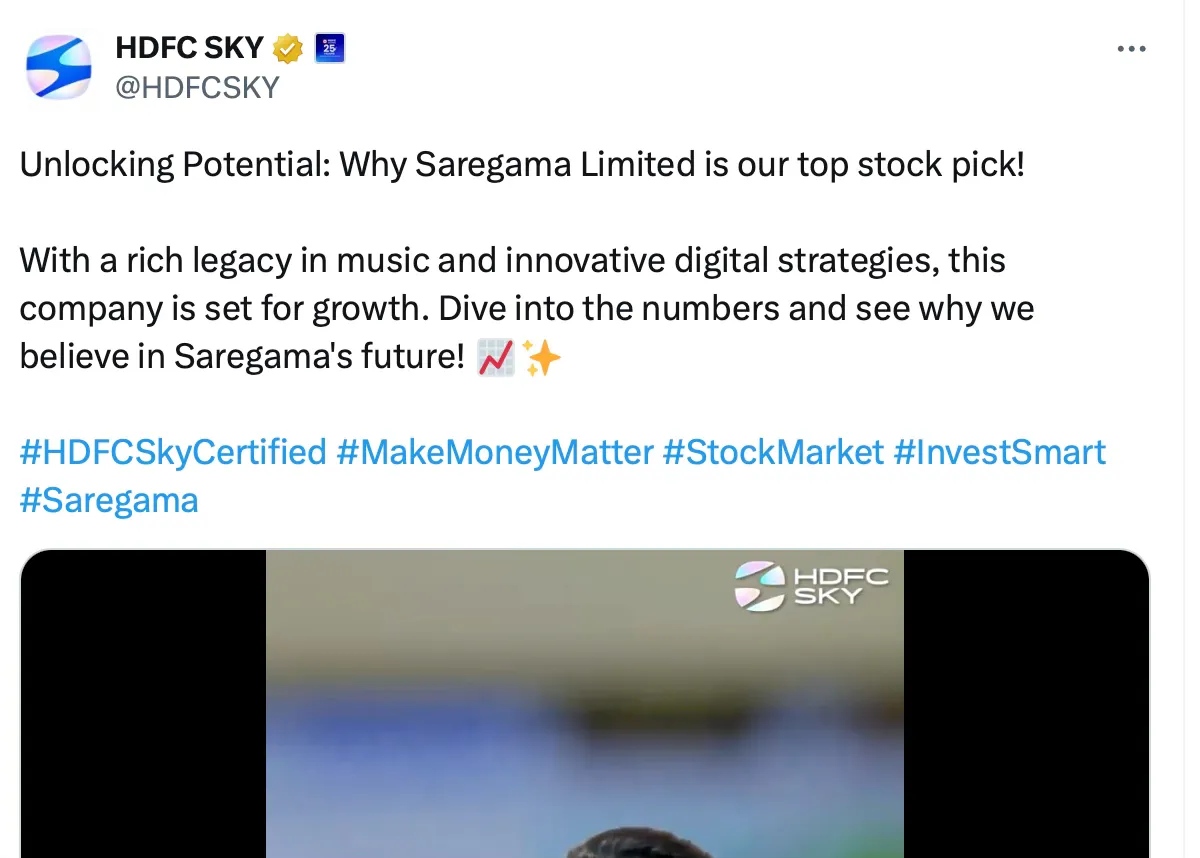
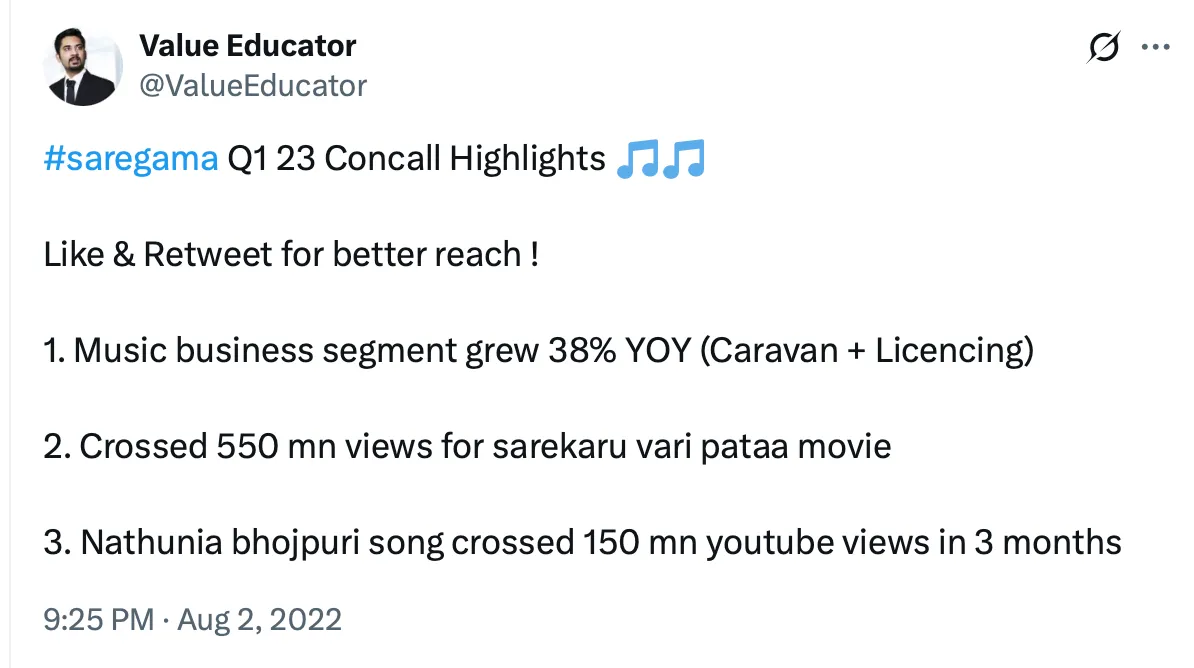
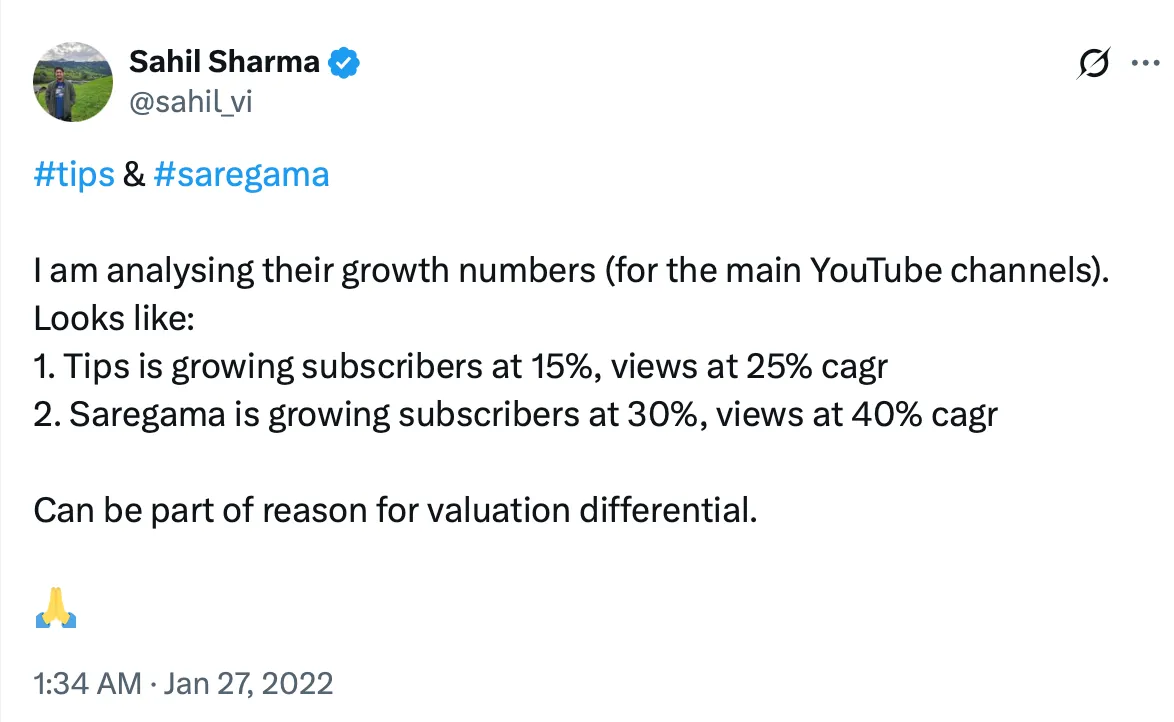
If just listening on twitter and investing would make money then there would be many millionaries
The Surface Story Looked Fantastic (2022–2024)
For three consecutive years, Saregama delivered headline numbers that would excite any investor.
Revenue growth:
₹542 cr → ₹742 cr → ₹927 cr
PAT growth:
₹159 cr → ₹218 cr → ₹256 cr
EBITDA margins:
Stable and strong, largely supported by high-margin music licensing.
Narrative tailwinds:
-
IP monetisation
-
OTT boom
-
Yoodlee Films
-
Carvaan revival attempts
-
YouTube/short-form monetisation
-
Catalogue acquisition
Everything looked perfectly aligned.
Just like Kitex in 2016—“high growth, high margins, high confidence.”
But Working Capital Started Quietly Bloating
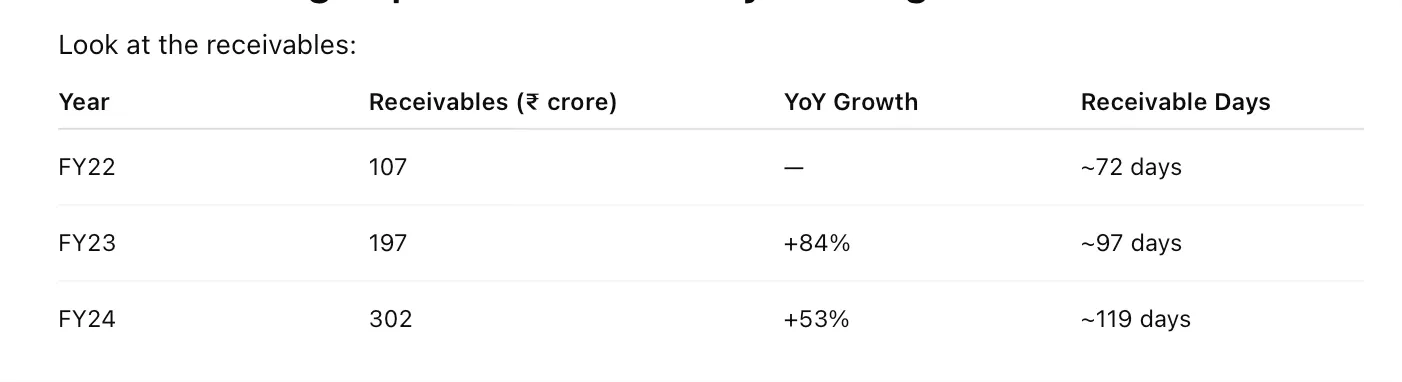
Why this matters:
-
Revenue was growing ~20–25%
-
But receivables grew much faster
-
This tells you growth required more credit, not more efficiency
When receivables rise faster than sales, accrual EPS becomes unreliable as a measure of true economic health.
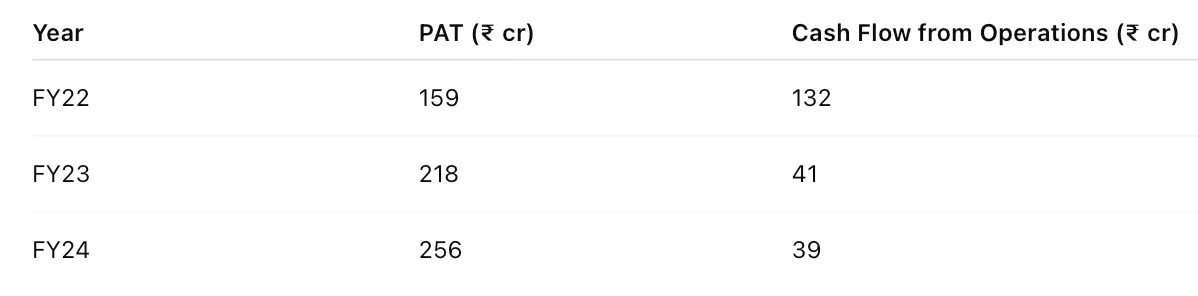
Even bigger problem is cash flow divergence
Over ₹630+ crore in reported profit over three years…
but only ~₹212 crore in operating cash.
That’s 33 paise of cash for every ₹1 of reported profit.
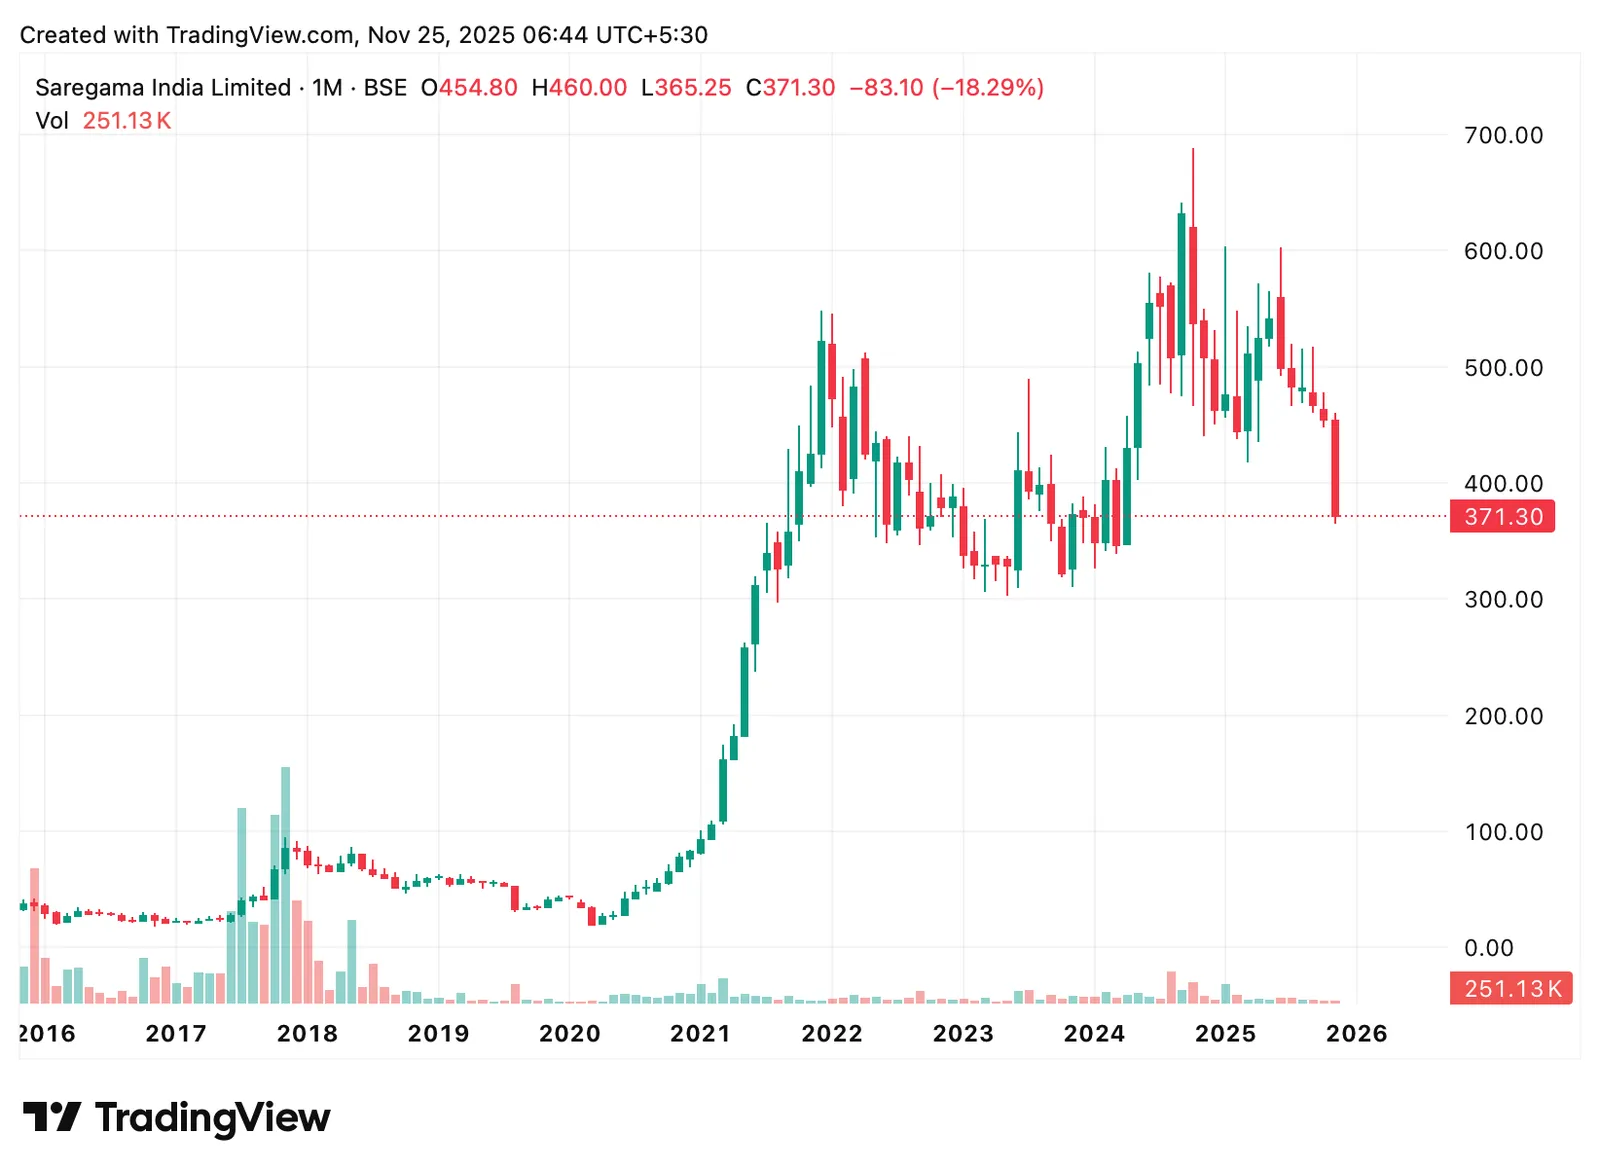
At the peak of optimism, Saregama touched valuations of a premium digital IP business.
But as the cash-profit gap widened,
and working capital kept eating value,
the market repriced the story.
From peak to trough:
steep correction.
as revenue collapsed.
as the company deteriorated operationally.
as “IP compounding” narrative couldn’t hide the underlying economics anymore.
History repeats!
Learning Twitter is not where you go for stock picks especially large followed accounts