PGINVIT - Updates!
For Introduction to PGINVIT read below article
Related: Powergrid InvIT
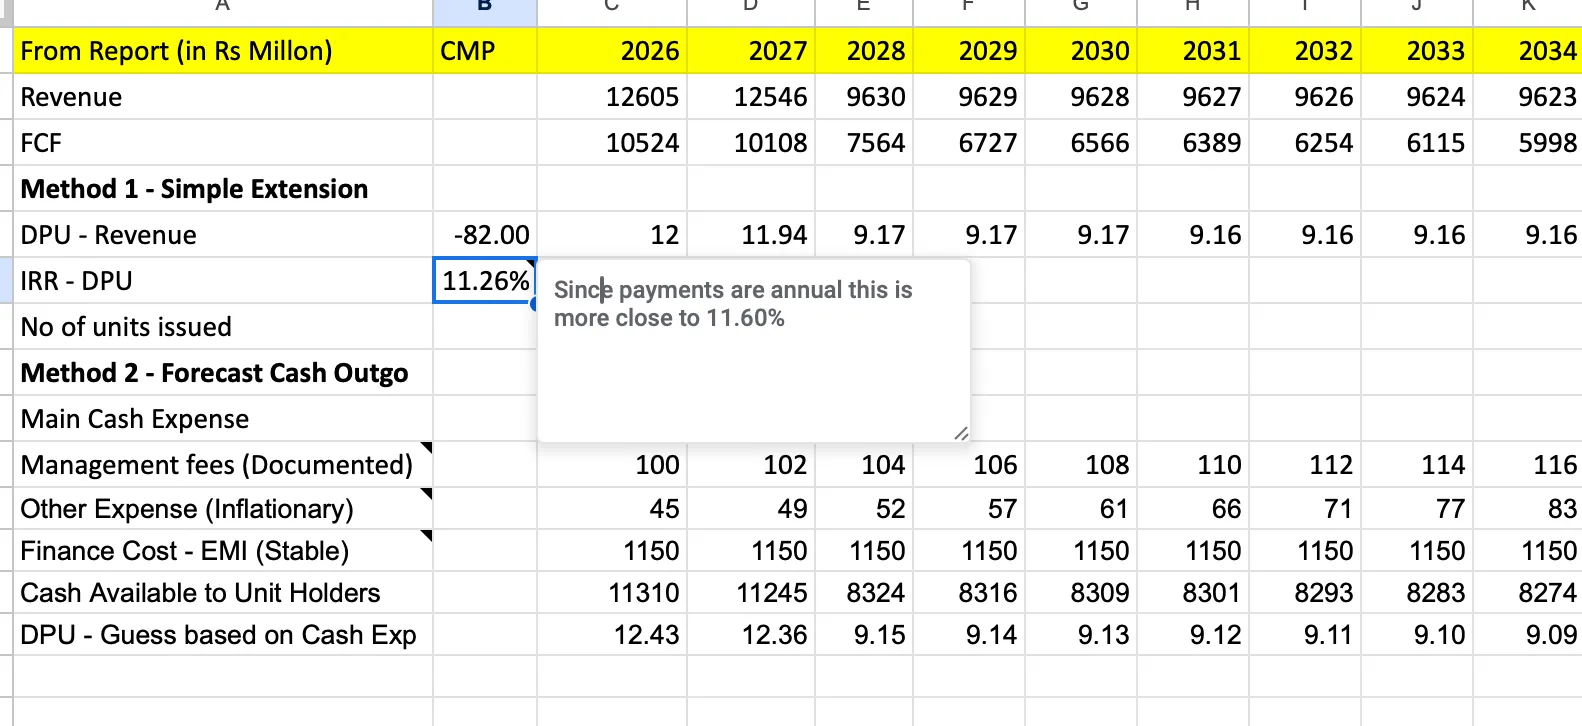
In above article I used FCF available to arrive at DPUs, I think a better approach is to link it to revenue and arrive at potential forecasted DPU, in same sheet not published in last article I had DPU projections linked to revenue and actuals in FY26 (DPU guidance of INR 12) are closer if I had used revenue linkage instead of FCF, it would have been better to analyse the DPU
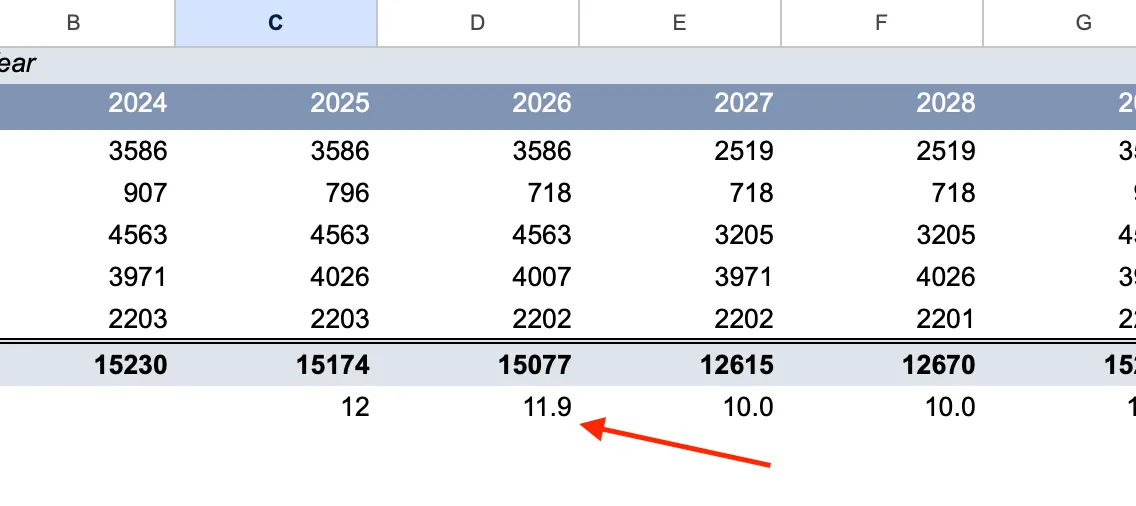
So with new valuation report available to us I have extracted revenue projections from all projects and tried to model DPU projections , if you want to do it yourself here are all important extracts from report
DPU is likely to drop to ~9 from FY2028 onwards, unless management is able to add more assets
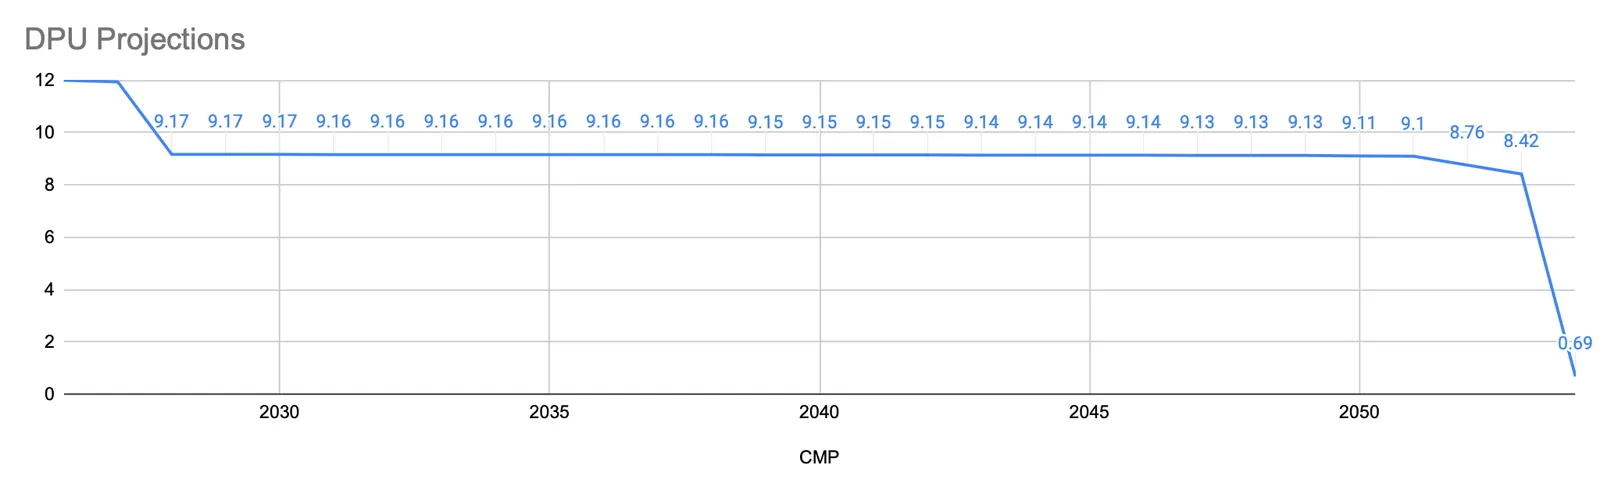
IRR at CMP of 81 is between ~11.5% to 12%
happy to hear your comments below
This is a record of the author's thinking in June 2025, kept as written. It is not a recommendation to buy or sell, and the author may hold the securities discussed. See the disclosures.
Tankrich research on PowerGrid InvIT
2 posts from 2025 to 2025, oldest first.
- Powergrid InvIT
- PGINVIT - Updates! (this post)