IREN, Six Months Later
Back in Feb, I argued IREN was a disciplined, renewable-first miner with a pragmatic “sell-BTC, fund growth” playbook. Since then the company has delivered 50 EH/s, secured NVIDIA Preferred Partner status, and is scaling an AI Cloud that could reach a $200–$250m annualised run-rate by year-end without leaning hard on equity. The stock has rerated, so the debate shifts from “can they execute?” to “what’s the payoff if BTC and AI both work and what’s my downside if either leg stalls?”
it is part of our US Live Folio
TL;DR (since Feb 23, 2025)
-
Scale: IREN actually hit its 50 EH/s mid-year target anchored by its 750MW Childress, TX campus.
-
Mix shift: The AI Cloud side went from ~1.9k GPUs in Q1 to a plan for ~10.9k GPUs (majority Blackwell) and earned NVIDIA “Preferred Partner” status; financing is largely non-dilutive (leases/vendor)
-
Financials: FY25 reported record revenue ~$501m and net income ~$87m; August update shows mining output of 668 BTC and AI Cloud revenue ~$2.4m for the month
-
Pipeline: Power/capacity keeps expanding—Sweetwater 2 (600MW) grid connection signed; BC (Prince George) being prepped for liquid-cooled GB300 NVL72
-
Stock moved a lot: Big run since spring on the dual Bitcoin + AI story.
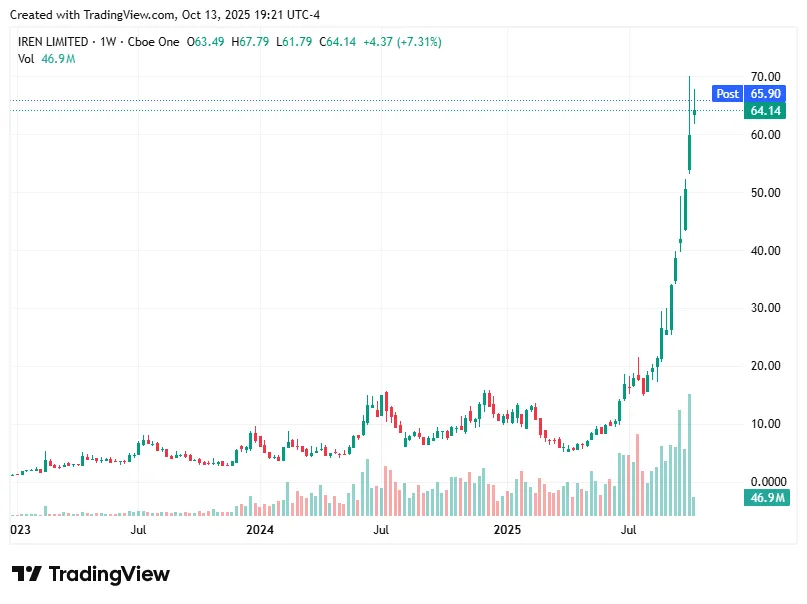
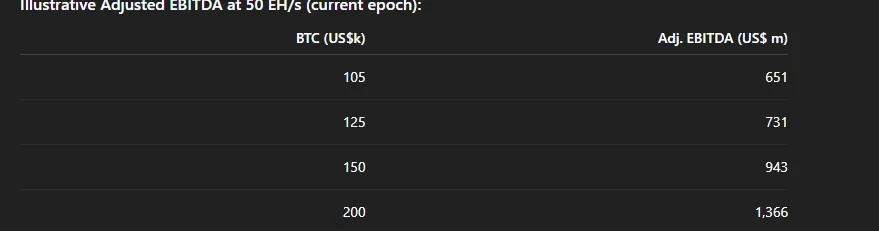
I am Trying to do a SOTP valuation by looking at both BTC mining business , note with ramping bull markets it wont matter but you should know your anchors
Anchor: the company’s 50 EH/s EBITDA sensitivity (mining leg)
AI Cloud: what we know and what we’ll assume
-
Supply & footprint: NVIDIA-aligned, liquid-cool capable sites (Texas, British Columbia) with a plan to deploy ~10.9k GPUs , in latest update they increased to ~23k GPUs
-
Commercial lens: Early customer names have been mentioned; earlier commentary framed US$200–250m annualised; later investor updates raised ambition toward US$500m+ ARR.
-
EBITDA margins (assumed): leased GPU clouds typically run ~35–55% adjusted EBITDA depending on utilisation, ARPU, term mix, and power. In SOTP below we use 35% (bear), 40% (base), 45% (bull)
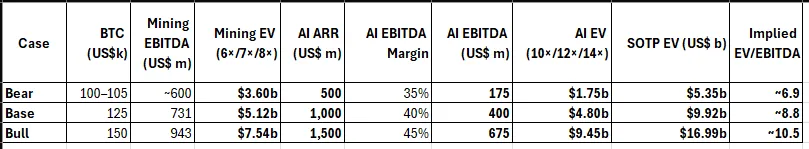
So bull estimates of USD 17bn market cap wile market cap crossed 18bn already on 15th October
There is X thread on valuation I have copied it below for your reference
What do you think about this In January, I called $IREN, an AI datacenter company with insanely valuable assets (power/permits/compute), a “Picasso at a garage sale” and one of the best ways to hedge against AI risk. If you didn’t buy it, you might think you’ve missed the train after it went up 336% from $11 to $48. That’s not the case. It’s still massively undervalued. The real move hasn’t even started yet and I’m not selling a single share. The current price is $48. But my target price is $300 (⬆7.2x higher). Why do I think it’s worth so much? Because I can do math. IREN is about to control more power than the Hoover Dam. 2,910 megawatts. That’s enough electricity to power San Francisco 3 times over. And they’re selling it to the most desperate buyers on Earth: AI companies. For each MW they secure, I estimate they can make $1.5M in profit annually. IREN has 2,910 of them. If they lease that to AI hyperscalers or inference players, they should be able to get about $180/kWM monthly. That’s $2.16 million in revenue per MW/year. Now apply typical datacenter margins of 70%, and we have $1.5 million in Funds From Operations (FFO) per MW. Datacenter businesses of this class typically trade at around 20-25x FFO. Let’s do the math: 2,910 MW × $1.5M = $4.4B annual FFO × 25 = $110B enterprise value Minus 25% debt (i.e ~$10M/MW in construction costs) = $83B equity value Current market cap: $13B My estimate of intrinsic value as purely a traditional co-location datacenter: $83B That’s still 7.2x from here. If the team continues to execute, the stock could hit $300. But this is where the story gets even better… Not only are they crushing it on execution but they also announced this past earnings release that they plan to become their very own Cloud Services Provider (CSP), just like Amazon, Google or Microsoft. They’ve got the largest amount of power of any datacenter company out there, and they’re about to become their own cloud provider. That puts IREN on a path to become the single largest AI datacenter company in the world. So, my $300 per share could be a lay-up. But let’s argue the bear case. What could go wrong? 1. This whole AI thing turns out to be a giant nothing-burger and nobody wants IREN’s power, land, datacenters and servers. Jesen Huang, the CEO of NVIDIA, just announced that demand for their chips has been insatiable. Then we heard the same thing from Meta, Oracle, Microsoft, Google, OpenAI, and X AI…you get the idea. Power is the bottleneck and IREN has a massive amount of cheap power right now. 2. IREN continues to have a tons of demand but is unable to capitalize on it because they build poor quality datacenters. The pivot from being a bitcoin miner to an AI powerhouse is no small feat. The good thing is that IREN’s founders, Dan and Will Roberts, have done this before. In fact, they’ve been building infrastructure projects like this for decades at one the world’s leading infrastructure banks. If they can’t get it done, I find it hard to believe anyone else can. 3. What if IREN’s competition outsmarts them on strategy and locks in large customers quicker? This has to be on any investor’s mind given what CoreScientific has done with CoreWeave, or what TeraWulf has done with Fluidstack (i.e. Google), or what Nebius has done with Microsoft. While the market has been fixated on a co-location deal, IREN has retained that option while pivoting to an even more lucrative CSP model. The next few quarters will be telling as they prove this out but you can already see in their recent quarterly earnings that they are lining up A-listers like Fluidstack as Cloud Service clients. NVIDIA isn’t handing out chips to the likes of IREN without a clear path to serving customer demand. Only 2% of their nearly 3,000MW of power has been converted to AI, so the best is yet to come, and there isn’t enough power to go around for years into the future. What’s it worth in a downside scenario if these things go wrong? We know that the market builds datacenters at a cost of roughly $10M per MW. So, 2,910MW x $10M = $29 billion in market value. That means, in a bear case, where all my assumptions are wrong, IREN is still worth around $106 dollars per share (or 2.2x higher than where they’re trading now). IREN is unique in that they’ve been efficiently building at a cost of $4M per MW, and they’ve done all of it by utilizing their Bitcoin profits, which are approaching $1B per year at current BTC prices without any debt. Simply put, it would cost someone $29B to replace the assets that IREN is currently building, so that’s still a double from here, give or take. The Picasso at the garage sale is is still underpriced - they raised the price from $11 to $48, but it’s worth at least $106 and more likely $300 if demand for AI continues to rip. PS: Not investment advice, just math. Do your own research.
My take
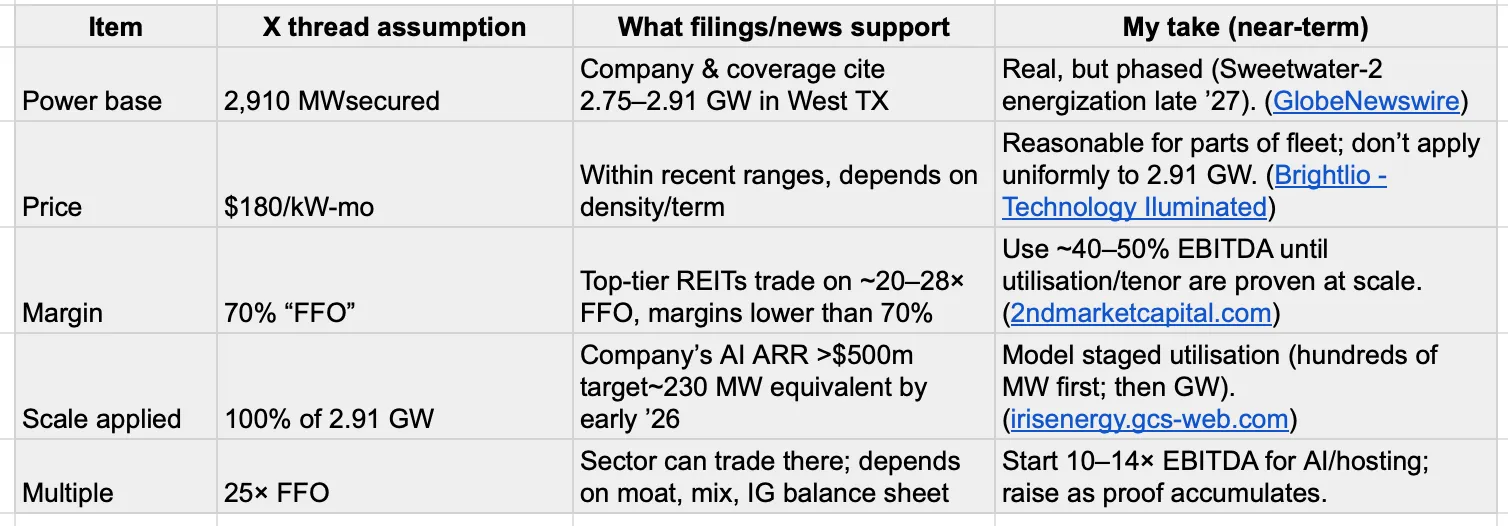
Happily riding momentum !
This is a record of the author's thinking in November 2025, kept as written. It is not a recommendation to buy or sell, and the author may hold the securities discussed. See the disclosures.
Tankrich research on IREN (Iris Energy)
2 posts from 2025 to 2025, oldest first.
- Iris Energy Limited
- IREN, Six Months Later (this post)