Annual Review - Ajanta Pharma 2019
Written in June 2019. There is newer research on Ajanta Pharma: Ajanta Pharma - Pivoting its fortunes (July 2020).
To get yourself familiar with Ajanta Pharma read my opening post about the company. In last year review sent to premium subscribers, we had projected below
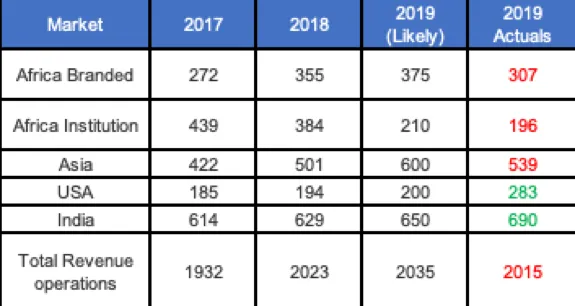
There was steep degrowth in Africa Institutional business and Branded generics, Also in Asia, they underperformed their own expectations resulting in modest growth. India business outperformed their own expectations (even mine) and USA business did very well too.
Three reds meant that they had their first topline decline in the last 15 years. The beauty of doing predictions is to get humbled very quickly in markets. In my 2017 review (link now broken) send to subscribers I had pasted projections from brokerage houses in the end note, I am reproducing them below
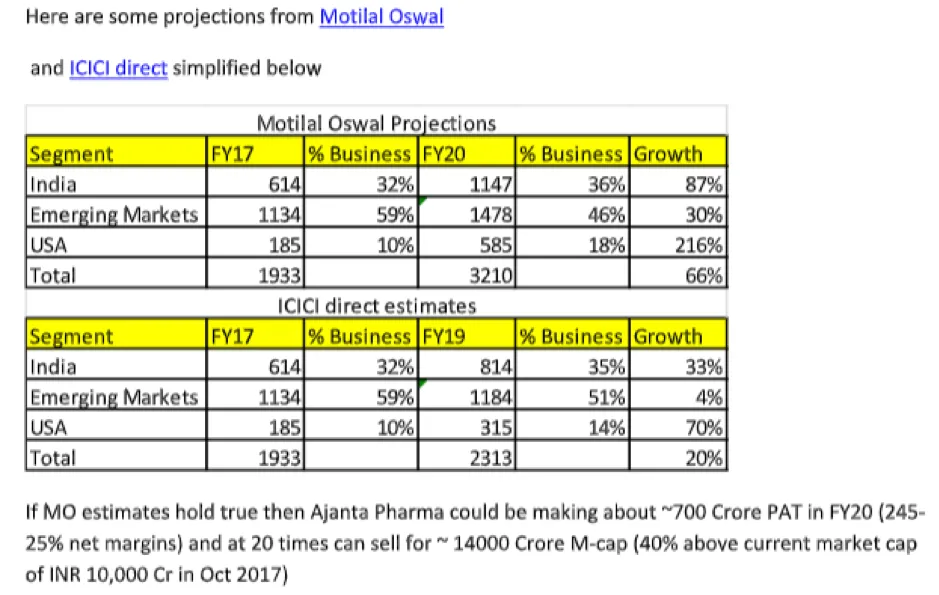
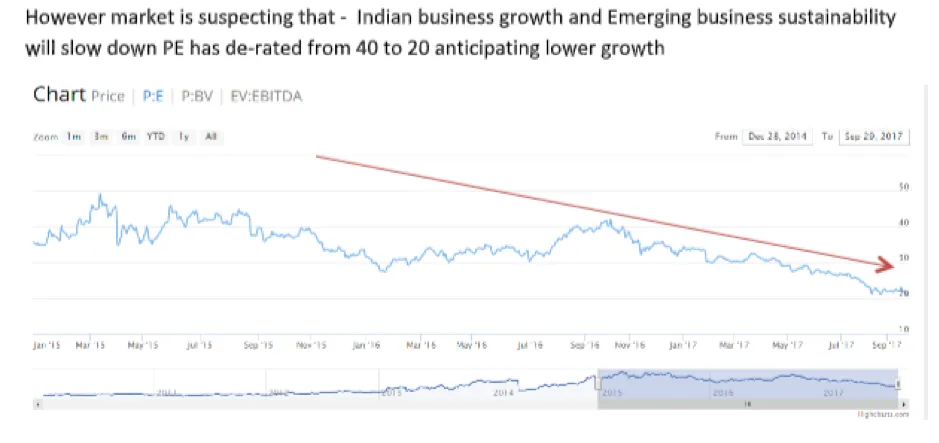
What was not baked in estimates was visible in price, The PE derating clearly told in advance that market doesn’t expect company do well and as it happens many times price discounts the performance for next 24-36 months in advance
Having spent enough time on past lets now review the current year
India business
FY 2019 was a very good year and Ajanta was back on track, they fixed their de-growth in dermatology segment from last year
-
Ophthalmology (14% growth vis-à-vis segment growth of 9%)
-
Cardiology (18% growth visà-vis segment growth of 10%)
-
Pain Management (22% growth vis-à-vis segment growth of 9%)
-
Dermatology (13% growth vis-à-vis segment growth of 13%)
Ajanta also launched 28 new products (9 first to market), The management continues to be focussed to grow this business at 15-20% clip for the next few years
Emerging Markets
Management indicated that in FY 2019 they brought down inventories to a reasonable level, by taking lower growth / de-growth in Asian markets
The African antimalaria institutional business was down by 50% as overall allocation saw significant contraction from funding bodies this was anticipated, it was not expected so sharply. This segment is going to down even further in FY20
USA
US business growth was very robust with 8 new product launches during the year, taking their total on-shelf products to 25. US has played a key role in recouping part of impact in the Africa institution business, they plan to file 10 to 12 ANDAs annually and expect 8 to 10 product launches in the next financial year. This is going to be the growth engine of the company while it grapples with the slow down in other areas
CAPEX
The CAPEX cycle is continuing even though the existing facilities are running at below capacity. The company proposes to spend further INR 350 cr. in FY 2020, mainly on Guwahati, Pithampur and corporate office in Mumbai. The new manufacturing facility is being set up in Pithampur SEZ, District Dhar, Madhya Pradesh.
The company has reinvested most of its cash generated from operations (Last 5 years) back in the building infrastructure (~70%) and capability (INR ~1350 crores out of ~2000 crores). I assumed that the Capex will be lower for this year however management is possibly foreseeing growth and that’s why investing now. We need to wait and watch if this is value accretive expenditure
Future
From ICICI Direct research report (link now broken) there is some guidance available as I could not get anything from Annual report and company doesn’t do any conference calls
The company guided for 10-11% of revenues growth for FY20.
-
India, Africa and Asia branded expected to grow 10-11% in FY20.
-
Africa tender business expected to decline 15%
-
US business expected to grow 25% in FY20
Margins would improve from the current levels of 19% as capacity utilization improves. So we are looking at about INR ~2300 crores topline and INR ~460 crores bottom line. The Market is valuing it fairly and It will become a tempting add at ~INR 7000 - 7500 Crore M-cap (Current Mcap at time of writing this in June 2019 is INR ~8300 Crores)
This is a record of the author's thinking in June 2019, kept as written. It is not a recommendation to buy or sell, and the author may hold the securities discussed. See the disclosures.
Tankrich research on Ajanta Pharma
3 posts from 2015 to 2020, oldest first.
- Annual Review - Ajanta Pharma
- Annual Review - Ajanta Pharma 2019 (this post)
- Ajanta Pharma - Pivoting its fortunes