Annual Review - Ajanta Pharma
Written in June 2015. There is newer research on Ajanta Pharma: Ajanta Pharma - Pivoting its fortunes (July 2020).
Firstly pharmaceutical is a space which I have started learning recently (2 years) and therefore it’s obvious that some of inferences that I will make in below review could be wrong
Secondly , Ajanta pharma as a business kept coming to my radar for last 3-4 years but I kept ignoring it due to my limited knowledge in pharma space, its only last year when I did earnings power box analysis and found that this company is in wealth maximising quadrant 2 then I became owner
Ajanta Pharma is a speciality pharmaceutical company engaged in development, manufacture and marketing of quality finished dosages in domestic and international markets.
For someone new a key snapshot to understand company, Keep it handy
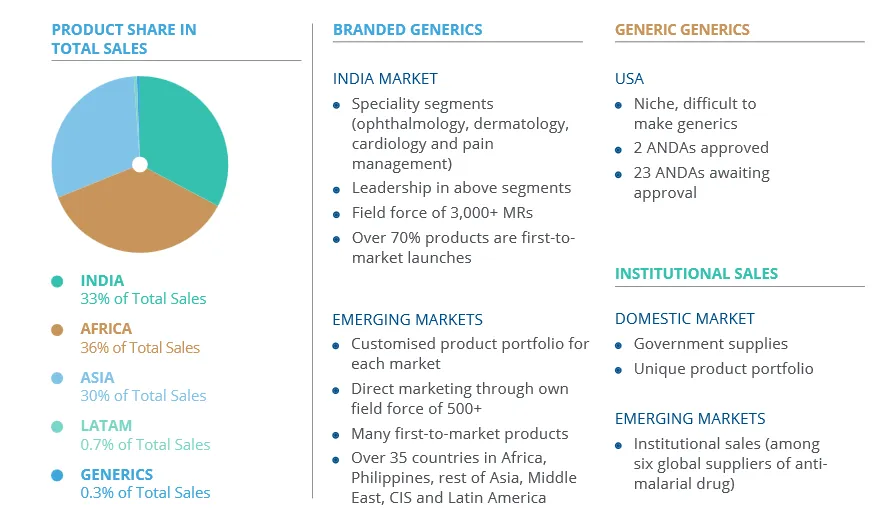
The company has clear strategy is each of the above markets
-
India, Asia, Africa – Would drive incremental growth (which has been decent for past decade)
-
LATAM & USA – Would drive exponential growth if the management gets its strategy right
Focus of the company
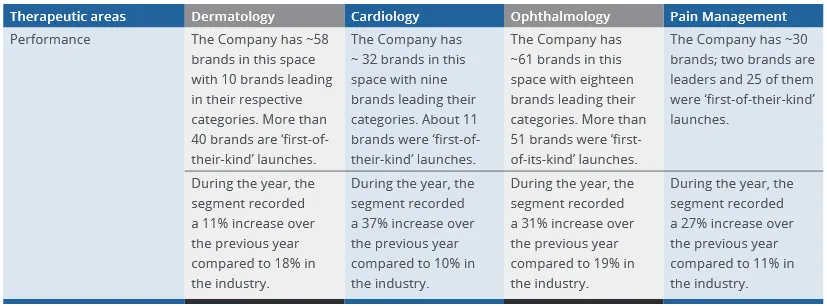
Therapy segments which include cardiology, dermatology, ophthalmology and pain management in India market and anti-malarial, anti-biotics etc. in Emerging markets, sharpen our focus on specialised segments
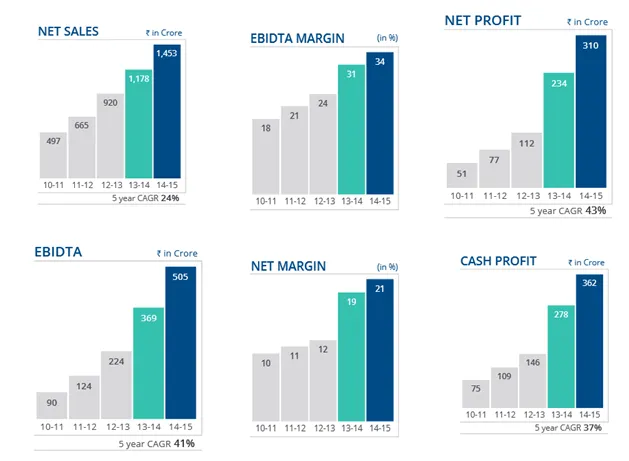
One of the few companies where all financial parameters – Tick in the box
Competitive strength
-
Strong brand portfolio of more than 400 products
-
127 First-to-market launches in India over last 10 years
-
1400+ product registration in emerging markets
One of the competitive strength has been first to market products in India and that continued with more products last year
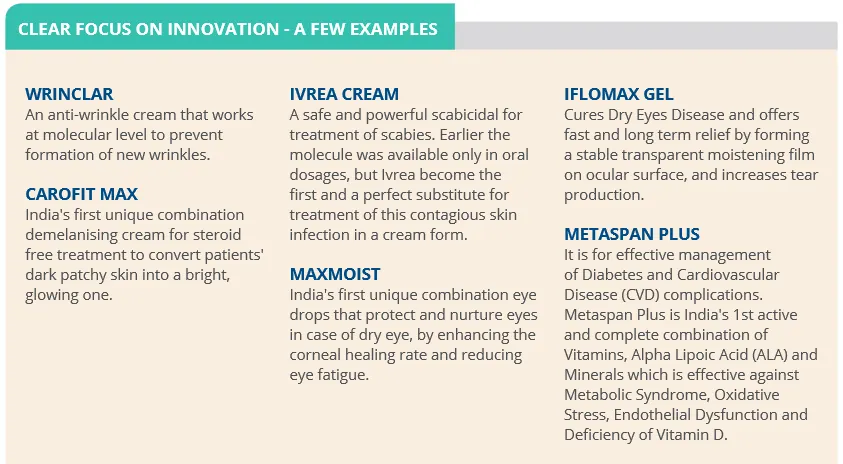
Products that got special mention by Rajesh Agarwal Joint Managing Director
Our new products like Wrinclar, an anti-wrinkle cream that works at molecular level to wipe off wrinkles, and Ketriplin C-efficiently treats Diabetic Peripheral Neuropathy, are breakthrough innovations that we brought into India in 2014 -15
Continues effort on R&D continued
During the year, expenditure on R&D was 77 Crore, signifying about 5% of total salesR&D efforts, the Company launched 24 new products in domestic market, 48 in emerging markets and 1 product in the U S market.The Company also filed 2 more ANDAs with the USFDA
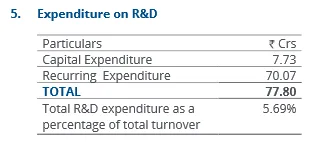
Best thing is most of it is expensed reducing PAT
Management’s view on Indian market size ~ Approx 80,000 Crore or roughly $16 Billion USD
India is a huge market worth over 80,000 Crore. We are choosing the right speciality segments, such as ophthalmology, cardiology, dermatology, where our innovations are helping us succeed. 127 products out of our overall 181 actively marketed brands in India, are first time launches in the country
Capex planned
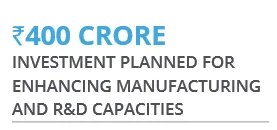
Kicker in earnings and sales would come from the newly created facility at Dahej to cater to US Market
The annual report had below update
We have 23 ANDA’s pending approval from USFDA and further planning to file 6-8 ANDA’s every year. As these approvals will start coming in, we will have our new Dahej facility ready to service the US market. It is the example of building right capabilities at right time. The facility has been fully constructed with the latest, state-of-the-art equipment and procedures meeting the stringent requirements of the FDA. This facility was completed in a record time of 24 months and regulatory
filing batches are expected to be starting from quarter starting July 2015. This is our largest facility, spread over 400,000 square feet. The facility will cater to the US markets and manufactures oral solid dosages, with a capacity of Tablets - 1,740 million annually, Capsules - 216 million annually, Powder - 150 million annually
Looking at the growth requirement 2 years down the line our proactive management has already planned for one more facility for India and Emerging markets. This facility is expected to be ready by FY 2017-18 Over last few years 220 Crores has been spent on Dahej for US market
Growth
Robust volume growth Revenues from operations increased by 23%, from 1,208.34 Crore in 2013-14 to 1,480.56 Crore in 2014-15. This increase was driven by growth in volumes in domestic business of 25% and export business of 23% along with niche and new launches of products
India business
Which areas did well – India business
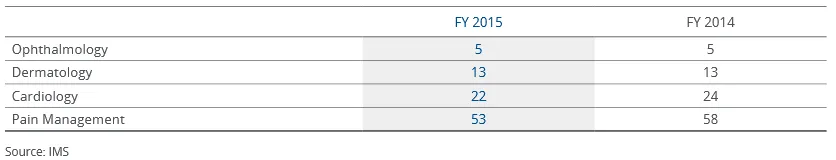
Improvement in ranking – India business
Other tit- bits
Turkmenderman Ajanta Pharma Ltd, an associate company, operates under severe restriction that significantly impairs its ability to transfer the funds. Company has been making efforts to divest this investment since last few years without any success. Hence, during the year, Company has fully provided 6.95 Crore, being permanent diminution in value of said investment and is shown under exceptional item.
Ajanta promoters have other business interest like Infra and renewable energy (solar), Check this website for more details
This year they brought some assets from a group company, nothing alarming in terms of value

In addition to above
- No Accounting gimmicks
- No Auditor Qualifications
- No alarming off balance sheet item
- No alarming related party transactions
Overall another fantastic year for an amazing growth machine
This is a record of the author's thinking in June 2015, kept as written. It is not a recommendation to buy or sell, and the author may hold the securities discussed. See the disclosures.
Tankrich research on Ajanta Pharma
3 posts from 2015 to 2020, oldest first.
- Annual Review - Ajanta Pharma (this post)
- Annual Review - Ajanta Pharma 2019
- Ajanta Pharma - Pivoting its fortunes