Paying for growth - Symphony
We did post on Symphony in April taking a leap of faith by paying for growth and adding it to then our public portfolio. This is going to be a very short post as we examine how valuation changes in high growth companies
Flash back April 2014 - Symphony per share valuation on 2013 reported numbers
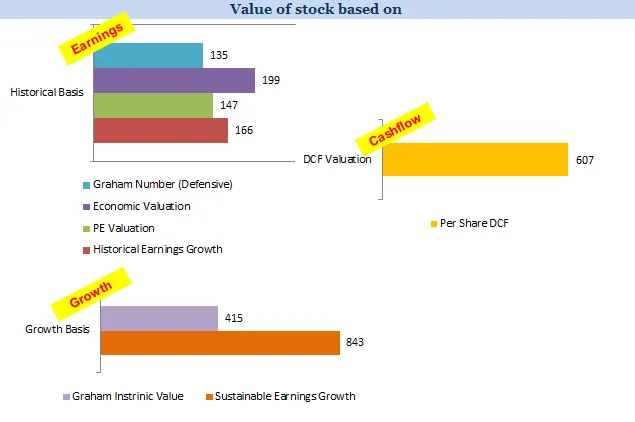
Our logic to add Symphony to model porfolio was simple , Sustainable growth basis per share value was calculated at 843 as per 2013 reported numbers (Note Symphony reports June to June FY) which was well below market price that time giving us an adequate margin of safety if company kept growing
Now lets come back to Symphony per share valaution based on 2014 reported numbers
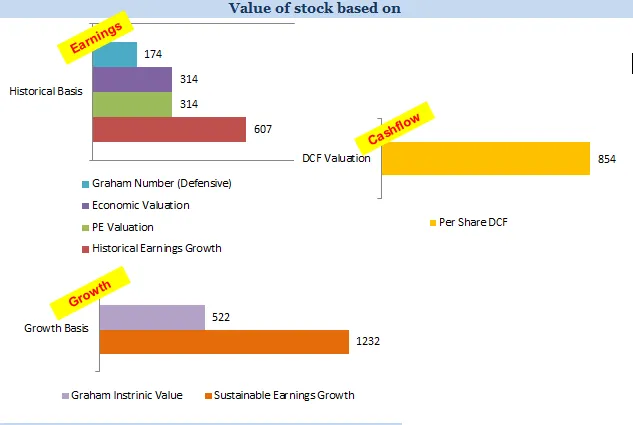
Now pay close attention to per share instrnic value a whopping 50+% increase in sustainable earnings per share value , followed by a very close 47%+ increase in instrnic value per share on FCF basis Market rewarded and recongnised it very fast in bull market this year
Learning
For fast growers always add sustaianble growth per share value as an additional item in your checklist before buying, you may find bargains when PE ratio will imply it is expensive
Caution
However a buy at current prices would not give any margin of safety to the investor, even if company repeats 2014, the 2015 Sustainable earnings growth per share value would be around INR 1905 which is roughly same as today’s market price
Hope this short post gives you a perspective to on how to value fast growers
Happy Investing
This is a record of the author's thinking in October 2014, kept as written. It is not a recommendation to buy or sell, and the author may hold the securities discussed. See the disclosures.
Tankrich research on Symphony
3 posts from 2014 to 2014, oldest first.
- Why I bought Symphony at a high PE ?
- Symphony - Understanding Competitive advantages
- Paying for growth - Symphony (this post)